 Whole Slide Imaging Market
: Size, Share & 2031 Outlook
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Whole Slide Imaging Market

Amit Mardhekar
Research Analyst

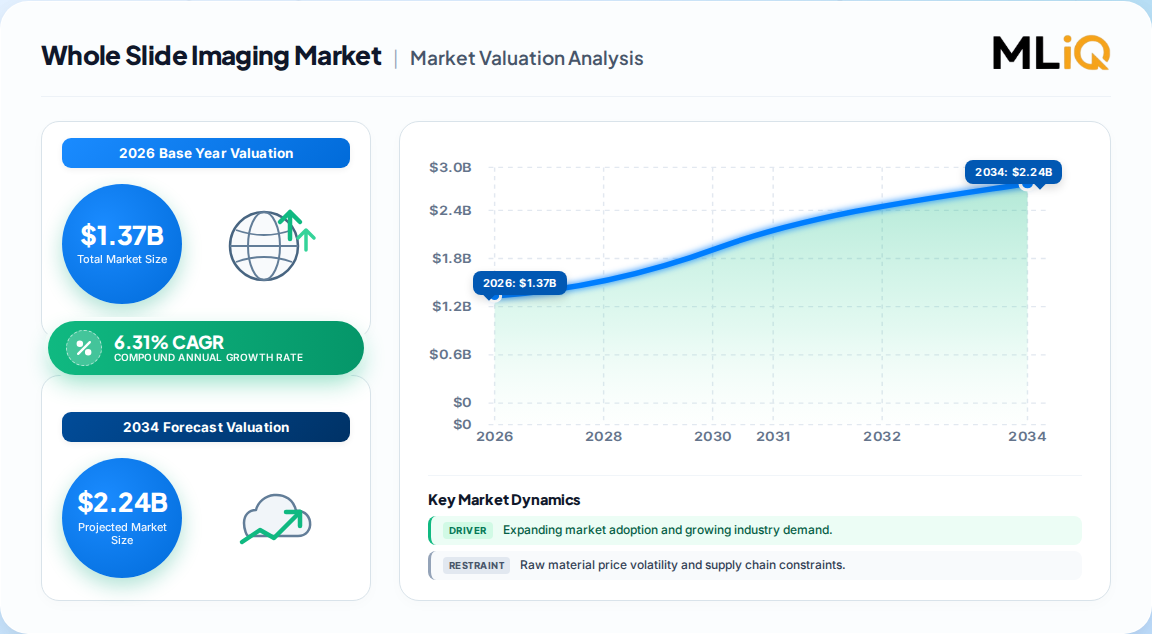
| Year | Market Size |
|---|---|
| 2025 | 1.290 B |
| 2026 | 1.370 B |
| 2027 | 1.460 B |
| 2028 | 1.550 B |
| 2029 | 1.650 B |
| 2030 | 1.750 B |
| 2031 | 1.860 B |

Whole slide imaging is the digitization of an entire glass histology slide into a high-resolution, multi-gigapixel virtual slide using automated scanners, paired with image-management and viewing software. It enables remote diagnosis, AI-assisted analysis, digital archiving and telepathology, replacing the optical microscope at the centre of the pathology workflow.
This analysis covers the global Whole Slide Imaging market: hardware (brightfield and fluorescence scanners, IT infrastructure, viewers), image-management software, applications (telepathology, cytopathology, immunohistochemistry, hematopathology) and end users (hospitals, diagnostic laboratories, research and pharma). This analysis does not cover adjacent markets such as laboratory information systems, standalone digital pathology AI software sold outside WSI platforms, or conventional optical microscopes.
Estimates diverge sharply, and the spread is definitional rather than empirical: hardware-only sizing produces ~USD 0.5 billion, while full digital-pathology ecosystem sizing approaches USD 1.3–1.4 billion.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.37 Billion → 1.86 Billion | 2026 | 2031 | 6.31% | Full WSI value: hardware + software, all applications | One published estimate |
| USD 486.2 Million → 866.3 Million | 2026 | 2033 | 8.6% | WSI systems only (scanners + services) | A competing analysis |
| USD 1,314.35 Million → 6,140 Million | 2026 | 2034 | 21.25% | Broad digital-pathology framing incl. IT infrastructure | A competing analysis |
| USD 1,300.46 Million → 2,640.59 Million | 2026 | 2033 | 12.7% | WSI incl. IT infrastructure, viewer and IMS | A competing analysis |
Our analysis suggests the 6–9% band is the most defensible for the core WSI category. The 21.25% figure implies a seven-year revenue increase of nearly five-fold, which is inconsistent with a market already generating USD 1.1 billion in 2025 and constrained by capital-budget cycles and pathologist retraining. The 8.6% systems-only estimate is credible for scanners but understates the software and services layer where growth is fastest.
Segmentation matters because growth rates differ by nearly two percentage points between the slowest hardware tier and the fastest software and end-user tiers.
| Parent segment | Children | 2025 share / growth |
|---|---|---|
| Component | Hardware, Software | Hardware 64.45%; software 6.63% CAGR |
| Scanner type | Brightfield, Fluorescence | Brightfield 51.62%; fluorescence 6.90% CAGR |
| Application | Telepathology, Cytopathology, Immunohistochemistry, Hematopathology | Telepathology 37.35%; IHC 7.28% CAGR |
| End user | Hospitals & clinical labs, Pharma & biotech, Academic & research | Hospitals 46.10%; pharma 6.48% CAGR |
North America leads with roughly 41–44% of global value, but Asia-Pacific is the fastest-growing region at a 7.02% CAGR, and the two dynamics imply very different commercial playbooks.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.25% |
| Asia-Pacific | 0.24% |
| South America | 0.04% |
| Middle East & Africa | 0.06% |
| Region | Share (approx.) |
|---|---|
| North America | 41% |
| Europe | 25% |
| Asia-Pacific | 24% |
| Middle East & Africa | 6% |
| South America | 4% |
Growth is driven by clinical necessity — rising cancer caseloads and pathologist shortages — while being restrained by capital intensity, and the two forces are roughly in balance at the current 6–7% trajectory.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Digital pathology for remote diagnostics | Growth (+1.8%) | High | Turns scarce pathologists into multi-site assets; China's national network logged 16,000+ consults |
| Rising cancer incidence | Growth (+1.5%) | High | WHO projects 35M+ annual cases by 2050, a ~77% rise |
| Declining scanner costs | Growth (+1.2%) | Medium-High | CCD-to-CMOS migration cuts price; 40x scan under 60 seconds |
| AI image-analysis integration | Growth (+1.0%) | High | Cleared algorithms reach 92.4% sensitivity vs 73.2% for pathologists on micrometastasis |
| Upfront capital expenditure | Restraint (−1.5%) | High | Full digitization runs USD 100,000–200,000 per site |
| Data-privacy and cross-border rules | Restraint (−0.8%) | Medium | GDPR and APAC fragmentation constrain cloud archiving |
| Limited reimbursement | Restraint (−0.6%) | Medium | Digital reads not uniformly reimbursed |
Our analysis suggests the restraint most often overstated is capital cost; scanner prices are falling faster than procurement documents assume, and pay-as-you-go cloud storage converts capex into opex. The restraint most often understated is reimbursement — it is the single factor most likely to delay routine clinical adoption outside North America.
The competitive field is medium-concentration, with scanner incumbents competing against software-led entrants; the decisive battleground is open analytical ecosystems, not optics.
| Vendor | Core strength | Strategic position |
|---|---|---|
| Olympus Corporation | Optics and brightfield scanner heritage | Installed-base defence |
| Leica Microsystems (Danaher) | End-to-end pathology workflow and reagents | Ecosystem integrator |
| Hamamatsu Photonics | High-throughput scanners (e.g. NanoZoomer S540MD) | Pharma and research volume |
| 3DHISTECH | Scanner breadth and software | Value-tier challenger |
| Koninklijke Philips | First FDA clearance for primary diagnosis (2017) | Clinical-trust anchor |
Differentiation is shifting from scan speed and resolution toward software openness and AI partnerships. Vendors that lock AI algorithms to their own platform create switching costs that buyers increasingly resist; those offering open APIs capture the faster-growing software tier.
Buyers should treat scanner selection as a ten-year interoperability decision, not a capital purchase. Prioritise systems with published, non-proprietary image formats and validated AI marketplaces; image-format incompatibility is the leading cause of stranded investment when labs later add analytics.
Regulatory validation is non-negotiable for primary diagnosis. In the US, FDA clearance plus College of American Pathologists self-validation (typically 60 cases) governs go-live; in Europe, GDPR and cross-border image transfer rules shape cloud architecture choices. Procurement risk concentrates in three areas: total cost of ownership beyond year three (storage, maintenance, retraining), vendor stability in a consolidating field, and workflow disruption during parallel glass-and-digital operation.
Switching costs are highest at the image-management layer, not the scanner. Labs that standardize on an open IMS preserve optionality across scanner generations; those that bundle both from a single vendor trade flexibility for integration convenience.
The balance of evidence favors the 6–9% growth band, with the 21.25% figure reflecting an over-broad definition that bundles IT infrastructure and general digital-pathology spend. Investors should anchor valuations to the core WSI category and treat the higher figures as a signal of adjacent-market enthusiasm rather than a forecast for scanners and imaging software alone.
The strongest counter-argument is that AI reimbursement, once established, could compress the adoption timeline dramatically — several national health systems are already piloting AI-assisted primary reads, and a single favorable reimbursement decision could push growth toward the mid-teens. We regard this as a plausible upside scenario, not a base case, because reimbursement cycles historically lag regulatory clearance by three to five years.
Actionable strategy:
What would change our conclusion: sustained reimbursement approval for AI-assisted primary diagnosis in two or more major markets, or a verified sub-USD 50,000 scanner price point reaching mid-tier hospitals at scale.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including scanner and optics manufacturers, image-management software vendors, laboratory information system integrators, AI algorithm developers and hospital procurement groups. Decision-maker designations interviewed included Heads of Digital Pathology, Laboratory Operations Directors, Procurement and Capital Equipment Leads, and Regulatory Affairs Managers.
Secondary validation drew on official multilateral and regulatory sources: FDA digital pathology clearances, College of American Pathologists validation guidance, WHO cancer incidence data, Eurostat and UN Comtrade trade flows, corporate annual filings (10-K, investor presentations) from listed vendors, and patent databases tracking scanner and AI imaging innovation.
Market sizing triangulates a top-down allocation from healthcare capital expenditure and pathology laboratory counts against a bottom-up model of scanner unit shipments, average selling prices, software attachment rates and cloud storage consumption per site.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up shipment and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.31% from 2020-2034 |
| Segmentation |
|
The global Whole Slide Imaging market is estimated at USD 1.37 billion in 2026, up from USD 1.29 billion in 2025. It is projected to reach USD 1.86 billion by 2031, representing a 6.31% CAGR over the forecast period.
The most defensible consensus CAGR is 6.31% for 2026–2031. Published estimates range from 6.3% to 21.3%, with the spread driven by whether IT infrastructure and broader digital-pathology spend are included in the definition.
North America leads with roughly 41–44% of global revenue, supported by FDA clearances for primary diagnosis and mature laboratory infrastructure. Asia-Pacific is the fastest-growing region at a 7.02% CAGR through 2031.
Telepathology is the largest application at 37.35% share in 2025, driven by remote diagnosis and specialist consultation. Immunohistochemistry is the fastest-growing application at a 7.28% CAGR through 2031.
Major vendors include Olympus Corporation, Leica Microsystems, Hamamatsu Photonics, 3DHISTECH and Koninklijke Philips. Philips holds the first FDA clearance for primary diagnosis, while Hamamatsu leads in high-throughput research scanning.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including scanner and optics manufacturers, image-management software vendors, laboratory information system integrators, AI algorithm developers and hospital procurement groups. Decision-maker designations interviewed included Heads of Digital Pathology, Laboratory Operations Directors, Procurement and Capital Equipment Leads, and Regulatory Affairs Managers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of Digital Pathology | 35% |
| Laboratory Operations Directors | 30% |
| Procurement & Capital Equipment Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Scanner & Optics Manufacturers | 40% |
| Imaging Software & IMS Vendors | 30% |
| AI Algorithm Developers | 18% |
| Hospital & Laboratory Procurement Groups | 12% |
Secondary validation drew on official multilateral and regulatory sources: FDA digital pathology clearances, College of American Pathologists validation guidance, WHO cancer incidence data, Eurostat and UN Comtrade trade flows, corporate annual filings (10-K, investor presentations) from listed vendors, and patent databases tracking scanner and AI imaging innovation.
Market sizing triangulates a top-down allocation from healthcare capital expenditure and pathology laboratory counts against a bottom-up model of scanner unit shipments, average selling prices, software attachment rates and cloud storage consumption per site.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up shipment and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |