 Dental Carpule Market
 Size, CAGR & Forecast 2026
Updated On : Nov 18, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Dental Carpule Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.200 B |
| 2026 | 2.370 B |
| 2027 | 2.560 B |
| 2028 | 2.760 B |
| 2029 | 2.980 B |
| 2030 | 3.220 B |
| 2031 | 3.470 B |

The dental carpule market covers prefilled anesthetic cartridges—typically glass or plastic—that seat inside dental aspirating syringes to deliver local anesthesia during restorative, endodontic, and surgical procedures. It spans the cartridge itself, the contained anesthetic formulation, and the sterile filling and packaging ecosystem that supplies dental clinics and hospitals.
This analysis covers dental anesthetic carpules by material, contained anesthetic agent, end user, and distribution channel, across global regions. It tracks manufacturers, sterile fill-finish capacity, and clinic-level procurement behavior. This analysis does not cover dental syringes and injector hardware, topical anesthetics, general anesthesia equipment, or implant and restorative materials beyond their anesthesia consumption linkage.
Estimates diverge sharply because publishers define the boundary differently—some count the cartridge only, others bundle the anesthetic fill. That definitional gap, not underlying demand, explains most of the spread across published figures.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.20 Billion | 2025 | 2033 | 7.92% | Global; carpule plus contained anesthetic | One published global analysis |
| USD 384.8 Million | 2025 | 2035 | 4.35% | United States only; cartridge-level | A competing US-focused analysis |
| USD 1.87 Billion | 2025 | 2034 | 4.5% | Global dental anesthesia incl. topicals | A third published analysis |
The USD 2.20 Billion figure is the most defensible global anchor, but our analysis suggests its 7.92% CAGR is inflated by base-year scope widening rather than true unit expansion. Cross-checking against the anesthesia-drug estimates (4.3–4.8%) implies a realistic underlying volume CAGR near 4.5–5.5%, with the residual attributable to premiumization.
Segmentation is best read along two axes: material economics (glass versus plastic) and anesthetic agent (lidocaine versus the articaine growth pocket). End user and channel then determine procurement behavior and price sensitivity.
| Parent segment | Children |
|---|---|
| By Material | Glass, Plastic, Metal |
| By Anesthetic Agent | Lidocaine, Articaine, Mepivacaine, Bupivacaine, Prilocaine, Etidocaine, Ropivacaine, Others |
| By End User | Dental clinics, Hospitals, Home care, Others |
| By Distribution Channel | Online, Offline |
Lidocaine holds roughly 41.5% of revenue on entrenched habit, but articaine is the fastest-growing agent. Our analysis suggests the articaine shift is a genuine formulation substitution, not a reporting artifact—and it is the single most important mix signal for cartridge fillers.
North America leads the global dental carpule market with approximately 38.7% of 2025 revenue, underpinned by high procedure volumes, dense private-practice infrastructure, and domestic manufacturing presence.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.27% |
| Asia-Pacific | 0.24% |
| South America | 0.06% |
| Middle East & Africa | 0.04% |
| Region | 2025 share | Growth posture |
|---|---|---|
| North America | ~39% | Mature, premiumization-led |
| Europe | ~27% | Stable, compliance-heavy |
| Asia-Pacific | ~24% | Fastest-growing |
| South America | ~6% | Emerging, price-sensitive |
| Middle East & Africa | ~4% | Nascent, import-dependent |
Asia-Pacific's growth premium is structural: expanding dental infrastructure, urbanization, and rising disposable income. This divergence implies multinationals should localize fill capacity rather than export, given cartridge freight economics.
Growth rests on rising procedure volumes tied to untreated oral disease and aging populations, with regulatory quality assurance acting as both gate and moat. Restraints are subtler: clinician habit, sterile-capacity limits, and price pressure in emerging markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising dental procedure volumes | Driver | High | Direct anesthesia consumption per visit |
| Minimally invasive procedure shift | Driver | Moderate | More, shorter procedures requiring precise dosing |
| Articaine clinician preference | Driver | Moderate | Formulation mix upgrade per cartridge |
| Sterile fill capacity constraints | Restraint | Moderate | Caps supply elasticity, supports pricing |
| Staffing shortages in dental practices | Restraint | Moderate | Slows procedure throughput |
| Regulatory compliance burden | Restraint | High | Raises entry cost, favors incumbents |
The balance favors incumbents. Our analysis suggests compliance is a net positive for established fillers because it converts a cost into a barrier—but it also slows new-market entry in Asia-Pacific precisely where growth is fastest.
The competitive field splits into vertically integrated anesthetic manufacturers and distribution-led players. Moats sit in sterile manufacturing certification and clinical familiarity, not in the cartridge itself.
| Company | Position | Core moat |
|---|---|---|
| Septodont | Integrated manufacturer | Sterile fill capacity and anesthetic portfolio |
| Dentsply Sirona | Device plus consumable | Chairside ecosystem lock-in |
| Pierrel Pharma | Specialty manufacturer | Formulation and regulatory depth |
| Inibsa | Regional manufacturer | European and LATAM channel reach |
| Nipro | Cartridge manufacturing | Precision glass and plastic forming |
| Henry Schein | Distribution | Clinic-level account breadth |
| Patterson Dental | Distribution | Practice workflow integration |
Our analysis suggests distribution-led players hold pricing power at the clinic level, while manufacturers hold it at the formulation level. Buyers negotiating across both tiers can extract more than single-tier deals allow.
Procurement decisions hinge on more than unit price. Cartridge dimensional tolerance determines syringe compatibility, and a non-conforming lot can halt a clinic's entire anesthesia workflow mid-day. Buyers should qualify at least two cartridge suppliers per anesthetic agent to avoid single-source exposure during sterile-capacity crunches.
Regulatory compliance is the second gate. Carpules are regulated as drug-device combinations in most jurisdictions, meaning supplier qualification requires validated sterility, extractables data, and traceability. Switching suppliers mid-contract carries real revalidation cost—often underestimated by clinic groups consolidating spend.
Finally, watch the glass-to-plastic transition. Plastic carpules reduce breakage and sharps risk but may raise extractables scrutiny. Operators adopting plastic early should secure documentation depth, not just price concessions.
The balance of evidence favors a mix-upgrade thesis over a volume thesis. The headline 7.92% CAGR is not credible as pure unit growth when the underlying anesthesia-drug market grows near 4.5%; the spread reflects formulation premiumization and cartridge-format substitution. Investors pricing this market on volume alone will overpay for commodity glass capacity.
The strongest counter-argument is that Asia-Pacific volume growth could genuinely accelerate the whole market past 8% if dental infrastructure expansion outpaces expectations. That is plausible but contingent on reimbursement and practitioner supply, both of which lag equipment investment by years.
What would change this conclusion: sustained double-digit procedure-volume data from China and India, or a regulatory pathway that commoditizes sterile filling. Absent either, premiumization remains the defensible growth engine—and the full report quantifies that mix shift segment by segment.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
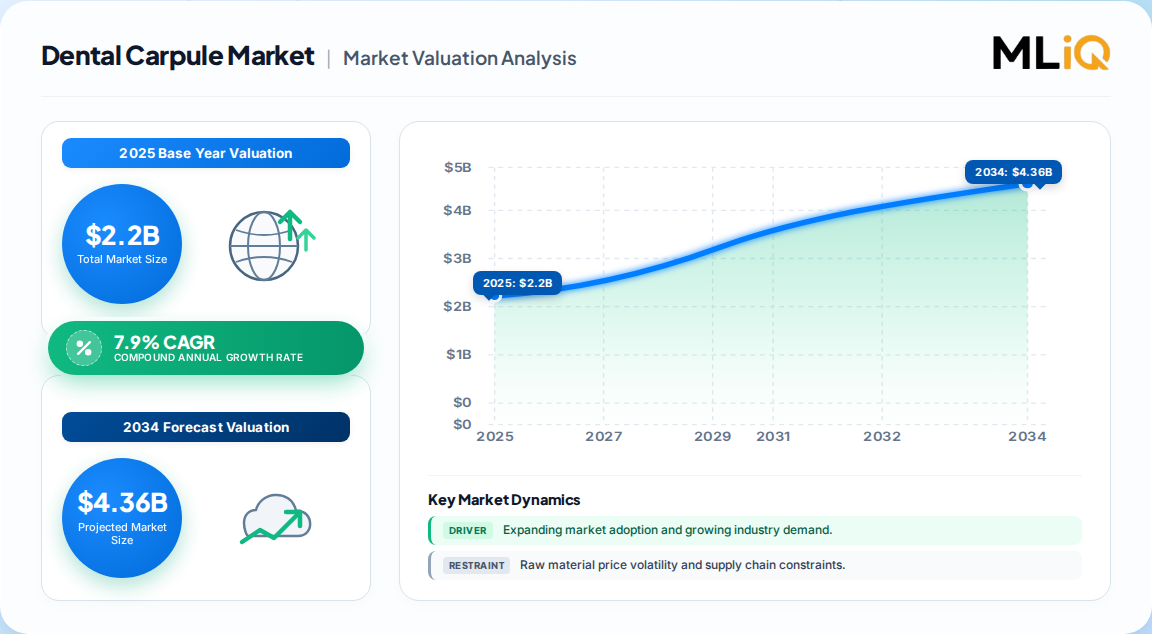
The global dental carpule market was valued at approximately USD 2.20 Billion in 2025, covering prefilled anesthetic cartridges and their contained formulations across dental clinics, hospitals, and other end users worldwide.
Published estimates cluster around a 7.9% CAGR through 2033. Our analysis suggests underlying volume growth is closer to 4.5–5.5%, with the remainder coming from formulation premiumization and cartridge-format substitution.
North America leads with roughly 38.7% of 2025 revenue, driven by high procedure volumes and dense private-practice infrastructure. Asia-Pacific is the fastest-growing region, supported by expanding dental care access and rising disposable incomes.
Lidocaine-based carpules hold approximately 41.5% of 2025 revenue due to entrenched clinical habit and broad suitability. Articaine is the fastest-growing agent, reflecting clinician preference for predictable infiltration in routine procedures.
Key suppliers include Septodont, Dentsply Sirona, Pierrel Pharma, Inibsa, Nipro, Henry Schein, and Patterson Dental. Moats rest on sterile fill-finish certification and formulation breadth rather than cartridge molding alone.
Plastic carpules are the fastest-growing material class, valued for reduced breakage and sharps risk. Glass still dominates volume, and the transition pace depends on extractables documentation and clinician acceptance rather than price alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the dental carpule value chain, spanning pharmaceutical-grade glass and polymer suppliers, specialized cartridge producers, contract sterile-fill formulators, and global dental distributors. Interview programs targeted designated decision-makers including VP-level Sourcing leads, Heads of Formulation R&D, Technical Directors overseeing sterility validation, and Commercial Operations Leads managing clinic-level channel economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Directors | 35% |
| Formulation & Technical R&D Heads | 30% |
| Quality & Regulatory Affairs Leads | 20% |
| Commercial & Channel Operations | 15% |
| Company Type | Representation (%) |
|---|---|
| Glass & Polymer Cartridge Producers | 40% |
| Sterile-Fill & Anesthetic Formulators | 35% |
| Dental Distributors & Wholesalers | 25% |
Findings were cross-validated against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings and investor presentations, patent filings covering cartridge geometry and self-aspirating designs, and recognized technical standards bodies governing medical device sterility and packaging. No third-party market research publications were used as validation anchors.
We ran simultaneous Top-Down allocation from macroeconomic dental expenditure and procedure-volume data, and Bottom-Up modeling from manufacturer sterile-fill capacity, cartridge pricing tiers, and end-use consumption per procedure. Divergence between the two approaches was reconciled through segment-level elasticity checks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |