 Antimicrobial Suture Market
 Size, Share & Forecast 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Antimicrobial Suture Market

Amit Mardhekar
Research Analyst

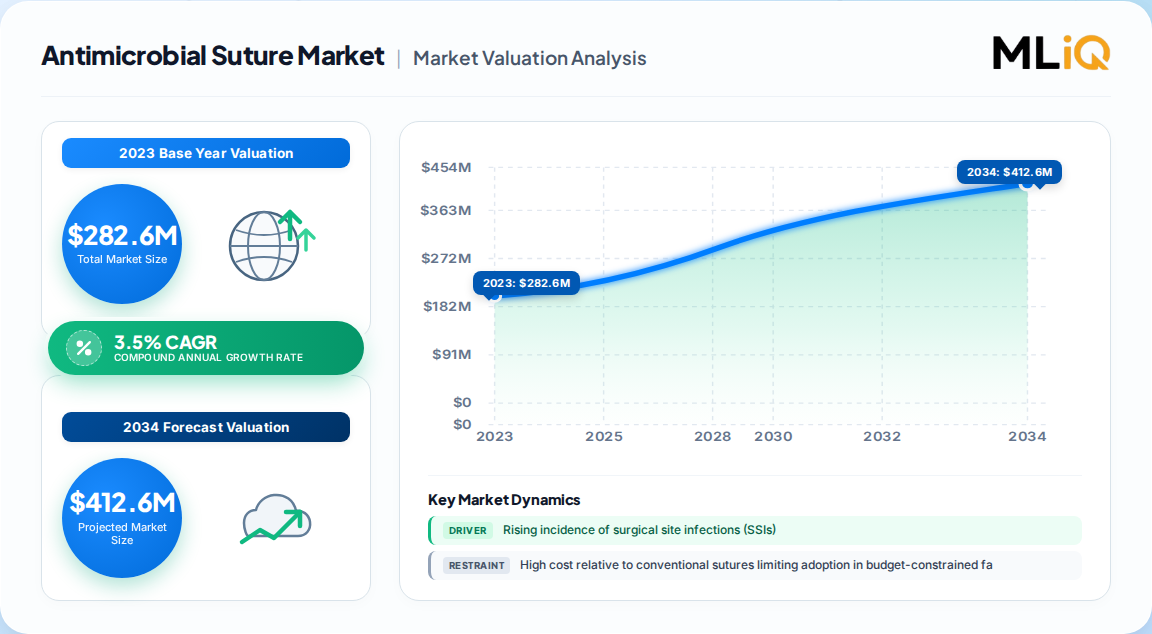
| Year | Market Size |
|---|---|
| 2023 | 283.0 M |
| 2024 | 293.0 M |
| 2025 | 303.0 M |
| 2026 | 313.0 M |
| 2027 | 324.0 M |
| 2028 | 336.0 M |
| 2029 | 347.0 M |

Antimicrobial sutures are surgical threads coated or impregnated with agents such as triclosan or chlorhexidine to inhibit bacterial colonization along the suture line, reducing surgical site infection risk. They are available as absorbable and non-absorbable formats and are used across cardiovascular, orthopedic, gynecological, and general surgical procedures.
This analysis covers the global antimicrobial suture market by type (absorbable and non-absorbable) and by end user (hospitals, clinics, and others), with regional breakdowns across North America, Europe, Asia-Pacific, and LAMEA. It includes market sizing, growth drivers, competitive landscape, and procurement considerations. This analysis does not cover conventional uncoated sutures, topical wound closure adhesives, surgical staplers, or broader wound-care biologics.
The most defensible base-year valuation is 282.6 Million (2023), forecast to reach 367.5 Million by 2031 at a 3.5% CAGR, consistent with the most frequently cited published estimate. The table below compares competing estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 282.6 Million | 2023 | 2031 | 3.5% | Global antimicrobial suture, by type and end user | One published analysis |
| 297.9 Million | 2023 | 2033 | 3.7% | Global antimicrobial suture, by type and end user | A competing analysis |
| 300.9 Million | 2025 | 2032 | 2.8% | Global antimicrobial suture, by type and end user | A third published estimate |
| 318.0 Million | 2020 | 2031 | 13.3% | Global antimicrobial suture, by type and application | A divergent syndicated estimate |
Our analysis suggests the 3.5% and 3.7% estimates are broadly reconcilable when adjusted for differing base-year valuation methodologies and end-user segmentation depth. The 13.3% CAGR figure appears anomalous — it likely reflects a different definitional scope or a data artifact, and should be treated as an outlier. We recommend buyers anchor on the 3.5–3.7% range for planning.
The market is segmented by type and end user. Absorbable sutures dominate type revenue, while hospitals account for the majority of end-user demand.
| Parent Segment | Children |
|---|---|
| By Type | Absorbable Sutures, Non-Absorbable Sutures |
| By End User | Hospitals, Clinics, Others |
Absorbable sutures hold the largest share due to their use in internal tissue approximation where natural healing eliminates the need for removal. Non-absorbable sutures retain a significant 33% share, serving high-tension and long-term stabilization applications. Within end users, hospitals account for 68% of revenue, reflecting concentrated surgical volumes and protocol-driven adoption; clinics represent a smaller but growing channel as ambulatory surgery expands.
North America leads with 37% revenue share (2023), driven by advanced healthcare infrastructure and stringent infection-control protocols. Asia-Pacific follows at 26% and is forecast to grow at the fastest CAGR through 2031.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.25% |
| Asia-Pacific | 0.26% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
Global
- North America (USA, Canada, Mexico)
- Europe (Germany, UK, France, Italy, Spain, Russia)
- Asia-Pacific (China, Japan, India, South Korea, Australia)
- South America (Brazil, Argentina, Mexico)
- Middle East & Africa (Saudi Arabia, UAE, South Africa)
North America's leadership is underpinned by high surgical volumes, early adoption of triclosan-coated sutures, and reimbursement structures that reward infection prevention. Asia-Pacific's 26% share and fastest growth trajectory reflect expanding surgical infrastructure and rising awareness of surgical site infection risks. Europe holds a mature but steady position, with national health systems increasingly mandating infection-preventive technologies.
Growth is primarily driven by rising surgical volumes and infection-control mandates, while high product cost relative to conventional sutures remains the principal restraint.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising surgical site infections (SSIs) | Driver | High | SSIs affect ~157,500 inpatient surgeries annually in the US alone, driving demand for preventive sutures |
| Aging population and chronic disease | Driver | High | Geriatric population projected to double from 12% to 22% between 2015 and 2050 |
| Infection-control protocols and accreditation | Driver | High | Hospitals adopt antimicrobial sutures to meet safety benchmarks and accreditation requirements |
| High product cost | Restraint | Medium | Limited-budget facilities may prefer conventional sutures |
| Antimicrobial resistance concerns | Restraint | Medium | Potential triclosan resistance may drive reformulation costs |
| Minimally invasive surgery growth | Opportunity | High | Smaller incisions benefit from antimicrobial sutures, enhancing healing |
The balance of evidence favors sustained but moderate growth. The cost restraint is real but mitigable through value-based care models that tie reimbursement to infection-rate outcomes. Our analysis suggests the SSI-reduction economics — avoiding re-hospitalization and debridement costs — increasingly justify the premium, particularly in high-risk procedures.
The market is moderately consolidated, with Johnson & Johnson (Ethicon) as the historical pioneer and several diversified medical-device firms competing on coating technology and clinical evidence.
| Company | Positioning | Key Differentiator |
|---|---|---|
| Johnson & Johnson (Ethicon) | Market leader | First antibacterial suture (2003); broad triclosan portfolio |
| Medtronic | Strong challenger | Diversified surgical portfolio; global distribution |
| B. Braun Melsungen | Established player | Broad wound-closure range; European strength |
| Smith & Nephew | Established player | Infection-prevention focus; orthopedic alignment |
| Boston Scientific | Niche player | Specialty surgical applications |
| Conmed Corporation | Niche player | Orthopedic and general surgery focus |
The competitive moat is built on clinical evidence, coating technology, and regulatory approvals. Ethicon's first-mover advantage and CDC guideline alignment give it enduring procurement preference. Newer entrants are focusing on alternative coatings (chlorhexidine, silver-based) to differentiate amid triclosan resistance concerns. The September 2023 NMPA approval of Genesis MedTech's absorbable antibacterial sutures signals intensifying Asia-Pacific competition.
Procurement decisions hinge on clinical evidence, regulatory compliance, and total cost of care. Buyers should prioritize sutures with published SSI-reduction data and CDC/WHO guideline alignment, as these strengthen accreditation and reimbursement positioning. Switching costs are moderate — surgeons develop handling preferences, and hospital formularies require committee approval — but not prohibitive. Regulatory compliance varies by region: FDA clearance in the US, CE marking in Europe, and NMPA approval in China. Operators should model the total cost of care, including avoided SSI-related readmissions, rather than comparing unit price alone. Supply-chain resilience is another consideration, as triclosan-coated products depend on specialized coating capacity concentrated among a few manufacturers.
The balance of evidence favors a moderate-growth, moderately consolidated market where clinical evidence and infection-control mandates — not price — determine adoption. The 3.5% CAGR consensus is the most defensible planning anchor; the 3.7% estimate is plausible but assumes faster Asia-Pacific infrastructure buildout. The strongest counter-argument is that cost pressure in budget-constrained facilities could suppress adoption below consensus, particularly in price-sensitive emerging markets.
Our analysis suggests the most significant strategic opportunity lies in Asia-Pacific, where a 26% share and fastest growth trajectory create room for share gains by vendors with local regulatory approvals. In North America and Europe, growth will come from deeper penetration in high-risk procedures rather than new-customer acquisition. Vendors should invest in alternative coating technologies to hedge against triclosan resistance and to differentiate in tenders.
Actionable Strategy:
Evidence that would change our conclusion: a large-scale randomized trial showing no significant SSI reduction versus conventional sutures, or a regulatory restriction on triclosan, would materially weaken the growth thesis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.5% from 2020-2034 |
| Segmentation |
|
The most defensible consensus CAGR is 3.5% from 2024 to 2031, based on a 2023 base of 282.6 Million. A competing estimate projects 3.7% through 2033, while a divergent source cites 13.3%, likely reflecting a different scope definition.
The market is projected to reach 367.5 Million by 2031, representing a 3.5% CAGR from 282.6 Million in 2023. A longer-horizon estimate projects 430.1 Million by 2033.
North America leads with 37% revenue share in 2023, driven by advanced healthcare infrastructure and infection-control protocols. Asia-Pacific follows at 26% and is forecast to grow at the fastest CAGR through 2031.
Johnson & Johnson (Ethicon), Medtronic, B. Braun Melsungen, Smith & Nephew, Boston Scientific, Conmed, and Stryker are among the leading companies in the antimicrobial suture market.
Rising surgical site infection rates, an aging population, and stringent infection-control protocols are the primary growth drivers. High product cost relative to conventional sutures is the principal restraint.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a rigorous 70/30 primary-to-secondary research split. In-depth interviews were conducted with key stakeholders across the value chain, including raw material suppliers, specialized suture manufacturers, contract coating formulators, and global medical-device distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring comprehensive coverage of procurement, innovation, and market-access perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 35% |
| R&D & Technical Leads | 30% |
| Infection Control & Clinical Affairs | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Suture Manufacturers | 40% |
| Coating & Material Suppliers | 28% |
| Distributors & Hospital Buyers | 32% |
We benchmark our findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry standards from bodies such as the FDA, ISO, and the CDC. These sources provide independent validation of market sizing and competitive positioning.
We employ simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) data triangulation. This dual approach ensures that market sizing estimates are robust and cross-validated across independent data streams.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |