Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Breast Reconstruction Market Outlook 2026: Size, CAGR & Forecast
Breast Reconstruction Market Outlook 2026: Size, CAGR & Forecast
Breast Reconstruction Market
Breast Reconstruction Market Outlook 2026: Size, CAGR & Forecast
Breast Reconstruction Market by Product (Breast Implants, Tissue Expanders, Acellular Dermal Matrix, Other Products), by Shape (Round, Anatomical), by Technology (Inframammary, Peri-Areolar, Trans-Axillary, Trans-Umbilical), by Placement (Submuscular, Subglandular, Dual-Plane), by End-Use (Hospitals, Cosmetology Clinics, Ambulatory Surgery Centers, Other), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
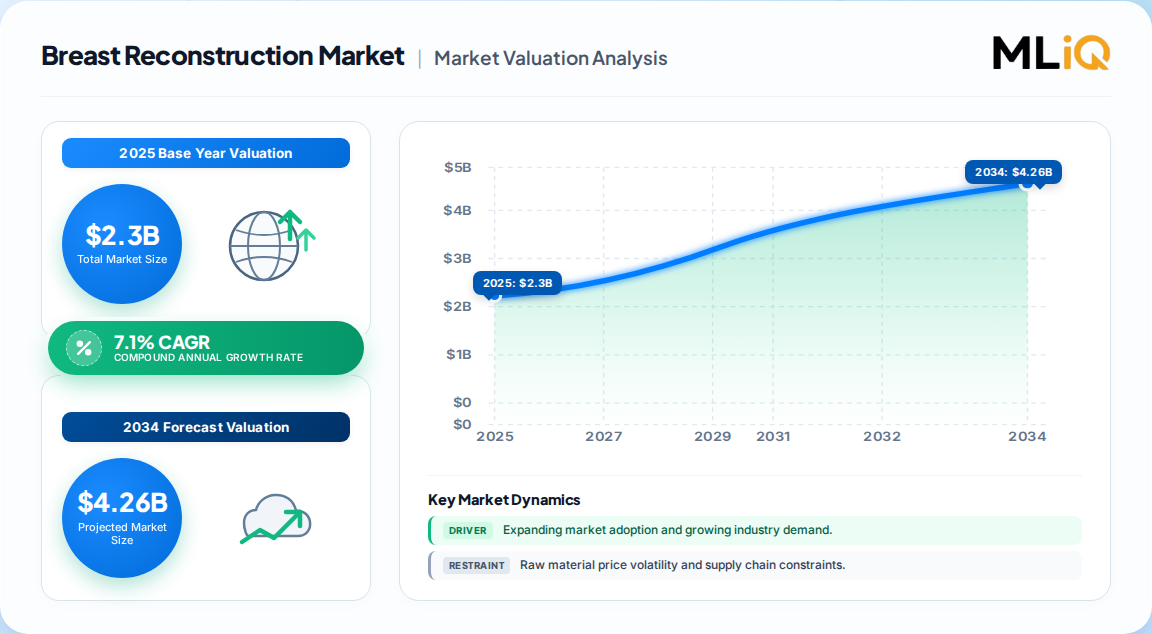
The global breast reconstruction market was valued at 2.3 Billion in 2025 and is projected to reach 3.9 Billion by 2033, expanding at a 7.1% CAGR (2026–2033).
Breast implants dominate product demand with a 60.4% revenue share in 2025, anchored by silicone gel innovation and premium aesthetic positioning.
North America remains the largest regional market at 61.0% share (2025); Asia Pacific is the fastest-growing region on rising cancer incidence and expanding surgical capacity.
Hospitals lead end-use with 46.7% share, though ambulatory surgery centers are gaining as outpatient reconstruction protocols mature.
Round implants hold 54.9% of shape demand, but anatomical designs are growing faster on aesthetic-outcome preference.
Key vendors include Johnson & Johnson (Mentor), Sientra, Allergan/AbbVie, GC Aesthetics, Integra LifeSciences, and Zimmer Biomet.
Why this matters for decision-makers: Implant-heavy revenue concentration means vendor strategy must shift toward differentiated biomaterials (ADM, robotic-assisted flap) to defend margins as non-surgical alternatives and price competition intensify.
Breast Reconstruction Market Size (In Billion)
4.0B
3.0B
2.0B
1.0B
0
2.300 B
2025
2.400 B
2026
2.600 B
2027
2.800 B
2028
3.000 B
2029
3.200 B
2030
3.400 B
2031
Breast Reconstruction Market Size (In Billion)
Year
Market Size
2025
2.300 B
2026
2.400 B
2027
2.600 B
2028
2.800 B
2029
3.000 B
2030
3.200 B
2031
3.400 B
What is the Breast Reconstruction Market?
The breast reconstruction market encompasses surgical products and procedures used to rebuild breast shape after mastectomy or trauma. Core categories include breast implants, tissue expanders, and acellular dermal matrix (ADM), delivered across hospitals, clinics, and ambulatory surgery centers worldwide.
Scope: what this report covers and excludes
This analysis covers implants, tissue expanders, and acellular dermal matrices across shape, placement, technology, and end-use segments in five global regions. It quantifies procedure-adjacent device revenue from 2025 through 2033. This analysis does not cover cosmetic breast augmentation alone, external prostheses as a standalone category, or oncology therapeutics.
How big is the market for Breast Reconstruction Market?
Published estimates diverge materially, largely because of scope differences. The most defensible baseline treats implants, expanders, and ADM together, consistent with standard industry segmentation.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
2.3 Billion (→3.9 Billion)
2025
2033
7.1%
Implants, expanders, ADM; full device revenue
One published estimate
1.76 Billion (→2.48 Billion)
2025
2030
7.0%
Implants, expanders, ADM, other products
A competing analysis
554.5 Million (→810.1 Million)
2023
2030
6.54%
Narrow product-scope, possibly device-manufacturer only
A third analysis
The 2.3 Billion figure is most defensible for total addressable device revenue because it explicitly includes ADM and expanders. The 554.5 Million figure likely reflects a narrower manufacturer-level slice. Our analysis suggests the divergence reflects scope, not demand disagreement.
How is the market segmented?
Segmentation follows product, shape, technology, placement, and end-use, each with distinct growth trajectories.
Parent Segment
Children
By Product
Breast Implants, Tissue Expanders, Acellular Dermal Matrix, Other Products
Hospitals, Cosmetology Clinics, Ambulatory Surgery Centers, Other
Implants and round shapes dominate today, but ADM and anatomical designs are the higher-growth sub-segments, signaling a shift toward aesthetic precision and outcome-driven purchasing.
Which region leads in Breast Reconstruction Market?
North America leads with 61.0% revenue share in 2025, driven by high cancer prevalence, favorable reimbursement, and advanced surgical infrastructure. Asia Pacific is the fastest-growing region.
Breast Reconstruction Market Regional Market Share
Loading chart...
Breast Reconstruction Market Regional Market Share
Region
Market Share (%)
North America
0.61%
Europe
0.17%
Asia-Pacific
0.14%
Latin America
0.05%
Middle East & Africa
0.03%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy
Asia Pacific — China, Japan, India, South Korea
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
Region
2025 Share
North America
61%
Europe
17%
Asia Pacific
14%
Latin America
5%
Middle East & Africa
3%
What is driving growth — and what is holding it back?
Growth is anchored by rising breast cancer incidence and procedure volume, while restrained by non-surgical alternatives and cost barriers.
Factor
Direction
Evidence strength
Mechanism
Rising breast cancer incidence
Driver
High
More mastectomies expand eligible candidates
Favorable reimbursement
Driver
High
Medicare and national programs fund reconstruction
Robotic-assisted surgery
Driver
Medium
Precision and recovery gains lift adoption
Aesthetic outcome emphasis
Driver
High
Premium implants and anatomical designs grow
Non-surgical alternatives
Restraint
Medium
Prostheses and flat closure reduce procedures
High implant cost
Restraint
Medium
Limits access in price-sensitive markets
The balance favors growth. Our analysis suggests reimbursement expansion in Asia Pacific could offset restraint pressure faster than most forecasts assume, particularly for ADM-supported procedures.
Who are the leading vendors?
Company
Positioning
Notable Strength
Johnson & Johnson (Mentor)
Global implant leader
FDA-approved MemoryGel Boost; broad portfolio
AbbVie (Allergan)
Premium implants
Strong brand equity and surgical relationships
Sientra
Specialty implants
Focused reconstruction portfolio and philanthropic reach
GC Aesthetics
International implants
Emerging-market penetration
Integra LifeSciences
ADM specialist
Dermal matrix leadership
Zimmer Biomet
Reconstruction devices
Orthopedic and surgical channel breadth
Differentiation rests on implant material innovation, surgeon training ecosystems, and reimbursement navigation. Moats are strongest where regulatory approval and clinical evidence combine.
What do buyers and operators need to know? (Decision Support)
Procurement decisions hinge on three factors: implant safety and long-term clinical evidence, reimbursement alignment, and total cost of ownership including revision rates. Regulatory compliance is non-negotiable, with FDA and EU MDR imposing rigorous post-market surveillance.
Switching costs are substantial. Once a hospital standardizes on an implant platform, surgeon familiarity, inventory systems, and training investments create friction. Buyers should evaluate ADM suppliers carefully, as material origin (human, porcine, bovine, synthetic) affects both outcomes and regulatory burden. Our analysis suggests multi-source strategies reduce supply risk but complicate surgeon preference management.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors sustained 7% growth, driven by cancer incidence and reimbursement rather than aesthetic demand alone. The strongest counter-argument holds that non-surgical alternatives and flat-closure preference could erode procedure volume in mature markets; however, rising incidence likely offsets this effect meaningfully.
Our analysis suggests implant revenue concentration is a strategic vulnerability, not just a strength. Vendors overly reliant on standard silicone implants face margin compression as ADM, robotic-assisted flap, and anatomical designs capture premium demand. Regional diversification into Asia Pacific is the clearest volume-growth lever.
Actionable Strategy:
Vendors should prioritize ADM and anatomical implant portfolios to capture premium, faster-growing sub-segments.
Operators should build reimbursement-navigation capability to accelerate adoption in emerging markets.
Investors should weight exposure toward companies with differentiated biomaterials and robotic-surgery partnerships.
Evidence that would change this conclusion: a sharp rise in flat-closure adoption in North America or reimbursement retrenchment would materially soften the forecast. Precise sub-segment forecasting and country-level procedure modeling require the full report.
Breast Reconstruction Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Breast Reconstruction Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.1% from 2020-2034
Segmentation
By Product
Breast Implants
Tissue Expanders
Acellular Dermal Matrix
Other Products
By Shape
Round
Anatomical
By Technology
Inframammary
Peri-Areolar
Trans-Axillary
Trans-Umbilical
By Placement
Submuscular
Subglandular
Dual-Plane
By End-Use
Hospitals
Cosmetology Clinics
Ambulatory Surgery Centers
Other
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Breast Reconstruction Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Breast Reconstruction Market Executive Summary
2.1. Market Snapshot
3. Breast Reconstruction Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Breast Reconstruction Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Breast Reconstruction Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product
5.1.1. Breast Implants
5.1.2. Tissue Expanders
5.1.3. Acellular Dermal Matrix
5.1.4. Other Products
5.2. Analysis, Insights and Forecast - by Shape
5.2.1. Round
5.2.2. Anatomical
5.3. Analysis, Insights and Forecast - by Technology
5.3.1. Inframammary
5.3.2. Peri-Areolar
5.3.3. Trans-Axillary
5.3.4. Trans-Umbilical
5.4. Analysis, Insights and Forecast - by Placement
5.4.1. Submuscular
5.4.2. Subglandular
5.4.3. Dual-Plane
5.5. Analysis, Insights and Forecast - by End-Use
5.5.1. Hospitals
5.5.2. Cosmetology Clinics
5.5.3. Ambulatory Surgery Centers
5.5.4. Other
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Breast Reconstruction Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product
6.1.1. Breast Implants
6.1.2. Tissue Expanders
6.1.3. Acellular Dermal Matrix
6.1.4. Other Products
6.2. Analysis, Insights and Forecast - by Shape
6.2.1. Round
6.2.2. Anatomical
6.3. Analysis, Insights and Forecast - by Technology
6.3.1. Inframammary
6.3.2. Peri-Areolar
6.3.3. Trans-Axillary
6.3.4. Trans-Umbilical
6.4. Analysis, Insights and Forecast - by Placement
6.4.1. Submuscular
6.4.2. Subglandular
6.4.3. Dual-Plane
6.5. Analysis, Insights and Forecast - by End-Use
6.5.1. Hospitals
6.5.2. Cosmetology Clinics
6.5.3. Ambulatory Surgery Centers
6.5.4. Other
7. Breast Reconstruction Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product
7.1.1. Breast Implants
7.1.2. Tissue Expanders
7.1.3. Acellular Dermal Matrix
7.1.4. Other Products
7.2. Analysis, Insights and Forecast - by Shape
7.2.1. Round
7.2.2. Anatomical
7.3. Analysis, Insights and Forecast - by Technology
7.3.1. Inframammary
7.3.2. Peri-Areolar
7.3.3. Trans-Axillary
7.3.4. Trans-Umbilical
7.4. Analysis, Insights and Forecast - by Placement
7.4.1. Submuscular
7.4.2. Subglandular
7.4.3. Dual-Plane
7.5. Analysis, Insights and Forecast - by End-Use
7.5.1. Hospitals
7.5.2. Cosmetology Clinics
7.5.3. Ambulatory Surgery Centers
7.5.4. Other
8. Breast Reconstruction Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product
8.1.1. Breast Implants
8.1.2. Tissue Expanders
8.1.3. Acellular Dermal Matrix
8.1.4. Other Products
8.2. Analysis, Insights and Forecast - by Shape
8.2.1. Round
8.2.2. Anatomical
8.3. Analysis, Insights and Forecast - by Technology
8.3.1. Inframammary
8.3.2. Peri-Areolar
8.3.3. Trans-Axillary
8.3.4. Trans-Umbilical
8.4. Analysis, Insights and Forecast - by Placement
8.4.1. Submuscular
8.4.2. Subglandular
8.4.3. Dual-Plane
8.5. Analysis, Insights and Forecast - by End-Use
8.5.1. Hospitals
8.5.2. Cosmetology Clinics
8.5.3. Ambulatory Surgery Centers
8.5.4. Other
9. Breast Reconstruction Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product
9.1.1. Breast Implants
9.1.2. Tissue Expanders
9.1.3. Acellular Dermal Matrix
9.1.4. Other Products
9.2. Analysis, Insights and Forecast - by Shape
9.2.1. Round
9.2.2. Anatomical
9.3. Analysis, Insights and Forecast - by Technology
9.3.1. Inframammary
9.3.2. Peri-Areolar
9.3.3. Trans-Axillary
9.3.4. Trans-Umbilical
9.4. Analysis, Insights and Forecast - by Placement
9.4.1. Submuscular
9.4.2. Subglandular
9.4.3. Dual-Plane
9.5. Analysis, Insights and Forecast - by End-Use
9.5.1. Hospitals
9.5.2. Cosmetology Clinics
9.5.3. Ambulatory Surgery Centers
9.5.4. Other
10. Breast Reconstruction Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product
10.1.1. Breast Implants
10.1.2. Tissue Expanders
10.1.3. Acellular Dermal Matrix
10.1.4. Other Products
10.2. Analysis, Insights and Forecast - by Shape
10.2.1. Round
10.2.2. Anatomical
10.3. Analysis, Insights and Forecast - by Technology
10.3.1. Inframammary
10.3.2. Peri-Areolar
10.3.3. Trans-Axillary
10.3.4. Trans-Umbilical
10.4. Analysis, Insights and Forecast - by Placement
10.4.1. Submuscular
10.4.2. Subglandular
10.4.3. Dual-Plane
10.5. Analysis, Insights and Forecast - by End-Use
10.5.1. Hospitals
10.5.2. Cosmetology Clinics
10.5.3. Ambulatory Surgery Centers
10.5.4. Other
11. Breast Reconstruction Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Breast Reconstruction Market Research Methodology
List of Figures
Figure 1: Breast Reconstruction Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Breast Reconstruction Market Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Breast Reconstruction Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Breast Reconstruction Market Revenue (Billion), by Shape 2026 & 2034
Figure 5: North America Breast Reconstruction Market Revenue Share (%), by Shape 2026 & 2034
Figure 6: North America Breast Reconstruction Market Revenue (Billion), by Technology 2026 & 2034
Figure 7: North America Breast Reconstruction Market Revenue Share (%), by Technology 2026 & 2034
Figure 8: North America Breast Reconstruction Market Revenue (Billion), by Placement 2026 & 2034
Figure 9: North America Breast Reconstruction Market Revenue Share (%), by Placement 2026 & 2034
Figure 10: North America Breast Reconstruction Market Revenue (Billion), by End-Use 2026 & 2034
Figure 11: North America Breast Reconstruction Market Revenue Share (%), by End-Use 2026 & 2034
Figure 12: North America Breast Reconstruction Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Breast Reconstruction Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Breast Reconstruction Market Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Breast Reconstruction Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Breast Reconstruction Market Revenue (Billion), by Shape 2026 & 2034
List of Tables
Table 1: Breast Reconstruction Market Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Breast Reconstruction Market Revenue Billion Forecast, by Shape 2020 & 2034
Table 3: Breast Reconstruction Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 4: Breast Reconstruction Market Revenue Billion Forecast, by Placement 2020 & 2034
Table 5: Breast Reconstruction Market Revenue Billion Forecast, by End-Use 2020 & 2034
Table 6: Breast Reconstruction Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Breast Reconstruction Market Revenue Billion Forecast, by Product 2020 & 2034
Table 8: North America Breast Reconstruction Market Revenue Billion Forecast, by Shape 2020 & 2034
Table 9: North America Breast Reconstruction Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 10: North America Breast Reconstruction Market Revenue Billion Forecast, by Placement 2020 & 2034
Table 11: North America Breast Reconstruction Market Revenue Billion Forecast, by End-Use 2020 & 2034
Table 12: North America Breast Reconstruction Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Breast Reconstruction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Breast Reconstruction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Breast Reconstruction Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Breast Reconstruction Market Revenue Billion Forecast, by Product 2020 & 2034
Frequently Asked Questions
1. How large is the breast reconstruction market?
The market was valued at approximately 2.3 Billion in 2025 and is projected to reach 3.9 Billion by 2033 at a 7.1% CAGR, according to industry estimates.
2. What is the fastest-growing region in breast reconstruction?
Asia Pacific is the fastest-growing region, driven by rising breast cancer incidence, expanding surgical infrastructure, and improving reimbursement access across key countries.
3. Which product segment dominates breast reconstruction?
Breast implants dominate with about 60.4% revenue share in 2025, though acellular dermal matrix and anatomical implants are growing faster on aesthetic-outcome demand.
4. What are the main restraints on the breast reconstruction market?
Non-surgical alternatives such as external prostheses, aesthetic flat closure, and high implant costs limit procedure volume, particularly in price-sensitive markets.
5. Who are the leading breast reconstruction vendors?
Johnson & Johnson (Mentor), AbbVie (Allergan), Sientra, GC Aesthetics, Integra LifeSciences, and Zimmer Biomet lead the market, competing on implant innovation and clinical evidence.
6. What is driving breast reconstruction market growth?
Rising breast cancer incidence, favorable reimbursement policies, and advances in silicone implants, ADM, and robotic-assisted reconstruction drive procedure volume and revenue growth.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, with fieldwork anchored in structured executive interviews across the breast reconstruction value chain. We conduct in-depth interviews with raw material and biomaterial suppliers, specialized implant and ADM manufacturers, contract manufacturing organizations, and global surgical distributors. Decision-maker designations include VP-level Sourcing leads, Heads of R&D and Product Development, Technical and Clinical Directors, and Commercial Operations Leads. Interview guides probe implant material trends, ADM adoption, reimbursement dynamics, and capacity constraints.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Clinical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory & Quality Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Implant & Biomaterial Manufacturers
45%
ADM & Tissue Product Specialists
30%
Global Surgical Distributors
25%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases, and recognized technical standards and industry associations. No competitor market-research publications are cited in our validation chain.
Demand Modeling & Market Sizing Triangulation
Market sizing runs simultaneously top-down (macroeconomic and provider-segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling). These streams are reconciled to produce a defensible base-year value and compound forecast.


 Breast Reconstruction Market