Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Fibromyalgia Treatment Market: 2030 Outlook & Forecast
Fibromyalgia Treatment Market: 2030 Outlook & Forecast
Fibromyalgia Treatment Market
Fibromyalgia Treatment Market: 2030 Outlook & Forecast
Fibromyalgia Treatment Market by Drug Class (SNRIs, Anticonvulsants, Tricyclic Antidepressants, Muscle Relaxants, Others), by Route of Administration (Oral, Topical, Injectable), by Distribution Channel (Retail Pharmacies, Hospital Pharmacies, Online Pharmacies), by Care Model (Pharmacotherapy, CBT/Behavioral, Physical Rehabilitation, Integrated Bundles), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
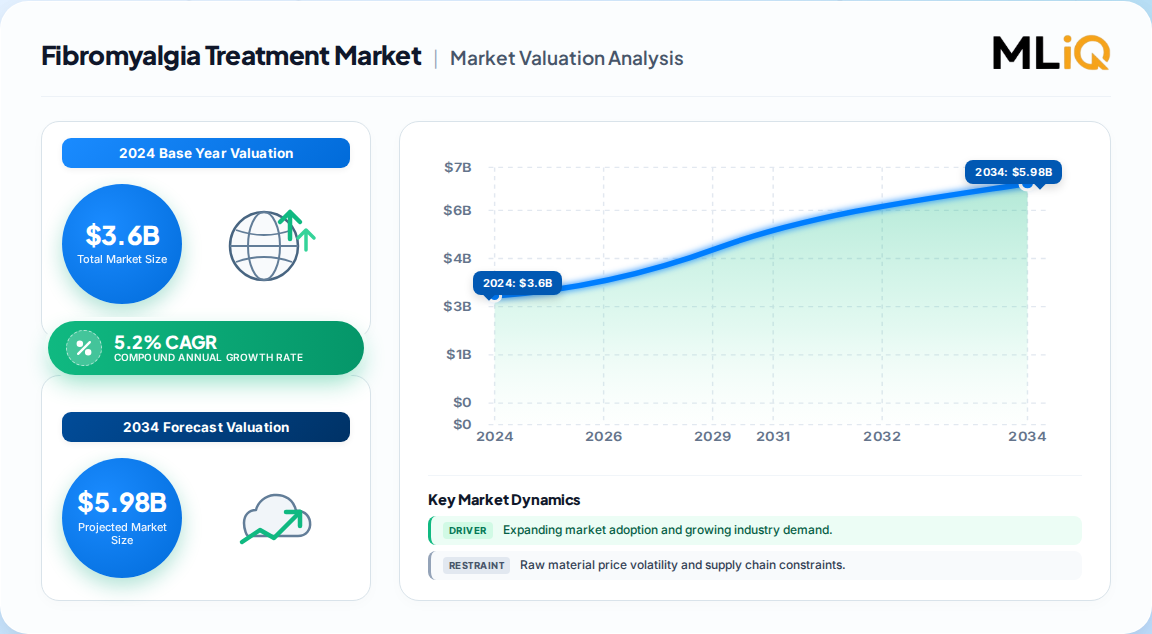
The global fibromyalgia treatment market was valued at USD 3.6 billion in 2024 and is projected to reach USD 4.88 billion by 2030, a 5.2% CAGR across the forecast period.
Growth is slow but structurally durable: three FDA-approved agents (pregabalin, duloxetine, milnacipran) anchor roughly 70% of prescriptions, so revenue tracks treated-population expansion rather than pricing.
SNRIs lead drug-class revenue at 35% share (~USD 1.26 billion), followed by anticonvulsants at 28% (~USD 1.01 billion); oral formulations dominate at 82% of value.
North America holds the largest regional share at 43% (USD 1.55 billion), while Asia-Pacific is the fastest-growing region at an 8.1% CAGR through 2030.
Retail pharmacies control 52% of distribution; online pharmacies (18% today) are the fastest-growing channel on generic price transparency and home delivery.
Pfizer leads competitive share (15%+ in 2025), with the top five players—Pfizer, Eli Lilly, Viatris, Teva, AbbVie—collectively holding approximately 46%.
Why this matters for decision-makers: With generics compressing drug pricing, value is migrating to multimodal care bundles—digital CBT, telehealth monitoring and coordinated pain clinics—where reimbursement is expanding and per-patient revenue is not capped by molecule price.
Fibromyalgia Treatment Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
3.600 B
2024
3.790 B
2025
3.990 B
2026
4.200 B
2027
4.420 B
2028
4.650 B
2029
4.880 B
2030
Fibromyalgia Treatment Market Size (In Billion)
Year
Market Size
2024
3.600 B
2025
3.790 B
2026
3.990 B
2027
4.200 B
2028
4.420 B
2029
4.650 B
2030
4.880 B
What is the Fibromyalgia Treatment Market?
The fibromyalgia treatment market encompasses pharmacological and non-pharmacological therapies for fibromyalgia syndrome—chronic widespread pain, fatigue and cognitive disturbance. It covers SNRIs, anticonvulsants, tricyclic antidepressants, muscle relaxants and off-label analgesics, plus CBT, physical rehabilitation and digital/telehealth care delivered through retail, hospital and online channels.
Scope: what this report covers and excludes
This analysis covers global revenue for fibromyalgia-specific pharmacotherapy, adjunctive pain management and reimbursed non-pharmacological care models across North America, Europe, Asia-Pacific, Latin America and the Middle East & Africa. It quantifies drug class, route of administration and distribution channel value pools from 2024 to 2030. This analysis does not cover broad chronic pain, neuropathic pain, depression or autoimmune therapeutics except where explicitly fibromyalgia-indicated, nor does it size unreimbursed wellness or supplement spending.
How big is the market for Fibromyalgia Treatment Market?
Published estimates diverge materially because each defines the treated boundary differently—some count only branded pharmacotherapy, others fold in generics, CBT and telehealth. The table below reconciles the principal competing estimates and their scope assumptions.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 3.6 billion → USD 4.88 billion
2024
2030
5.2%
Pharmacotherapy plus reimbursed behavioral/digital care, global
One published industry estimate
USD 2.10 billion → USD 3.55 billion
2025
2035
5.4%
Drug therapies plus structured PT/CBT/telehealth, global
A competing analysis
USD 3.31 billion → USD 4.99 billion
2026
2036
4.2%
Antidepressants, antiepileptics, muscle relaxants by channel
A third published estimate
Our analysis suggests the USD 3.6 billion 2024 base is the most defensible for procurement and investment planning: it aligns with the ~70% prescription concentration on three agents and with the 43% North American revenue share. The lower USD 2.1 billion figure likely narrows the boundary to drug-only spend, while the 4.2% CAGR understates demand from the multimodal shift.
How is the market segmented?
Segmentation follows clinical practice: drug class drives revenue, route reflects outpatient chronic management, and channel captures where refills and therapy initiation actually occur. The structure below excludes geography.
SNRIs and anticonvulsants together represent 63% of value; oral delivery 82%; retail pharmacies 52%. Integrated bundles remain small but are the fastest-growing construct, which our analysis reads as the leading indicator of where margin will migrate.
Which region leads in Fibromyalgia Treatment Market?
North America leads the global fibromyalgia treatment market with 43% of 2024 revenue (USD 1.55 billion), supported by high diagnosis rates, established SNRI prescribing and deep retail pharmacy penetration. Asia-Pacific is the fastest-growing region at an 8.1% CAGR, though from a 13% base.
The divergence is structural, not cyclical. US growth (~4.1%) is capped by generic maturity, while APAC's 8.1% reflects diagnostic catch-up and generics access. Europe's 3.0% path implies modest pricing power; Latin America and MEA carry the highest affordability risk.
What is driving growth — and what is holding it back?
Growth is driven by a large, female-skewed prevalent pool and widening guideline acceptance of multimodal care; it is restrained by a 6.42-year mean diagnostic delay and drug-cost-driven non-adherence. The net effect is steady mid-single-digit expansion rather than breakout growth.
Our analysis suggests the diagnostic delay is the single highest-leverage restraint: shortening time-to-diagnosis would expand the treated pool faster than any plausible pricing or pipeline event through 2030.
Who are the leading vendors?
Pfizer leads with over 15% share, and the top five players—Pfizer, Eli Lilly, Viatris, Teva and AbbVie—hold roughly 46% collectively. Competition is shifting from molecular novelty toward care-orchestration capability and payer partnerships.
Company
Position
Core Asset / Focus
Moat
Pfizer
Leader, 15%+
Duloxetine (Cymbalta)
Guideline embeddedness, physician trust
Eli Lilly
Major
Off-label antidepressant heritage
Prescriber network legacy
Viatris
Major
Generic CNS portfolio
Formulary volume, cost leadership
Teva
Major
Generic duloxetine, gabapentin
Scale and global distribution
AbbVie
Major
Milnacipran (Savella)
Chronic pain portfolio integration
Tonix Pharmaceuticals
Challenger
Tonmya (cyclobenzaprine sublingual)
First new approval in 15 years
Differentiation now rests on ecosystem design—patient support, adherence programs and payer contracts—not on mechanism. Generic manufacturers compete on price and reach; digital therapeutics firms compete for reimbursement contracts rather than prescriptions.
What do buyers and operators need to know? (Decision Support)
Procurement decisions hinge on formulary positioning, not clinical novelty. Because three agents dominate prescribing, buyers should negotiate generic duloxetine, pregabalin and milnacipran contracts early, locking volume tiers before payer consolidation narrows options. Switching costs are low for generics but high for integrated care contracts, where digital CBT and monitoring platforms embed into patient workflows.
Regulatory compliance varies sharply by region: US reimbursement for digital tools is expanding, while many EU and emerging markets still lack fibromyalgia-specific coverage. Buyers should build country-level reimbursement risk into contracts. The principal procurement risk is diagnostic ambiguity—variable coding inflates demand forecast error. Operators entering APAC should prioritize localization and frontline physician training, since underdiagnosis, not competition, is the binding constraint.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a value-migration thesis: pharmacotherapy revenue grows steadily at 5.2%, but margin concentrates in multimodal care bundles and digital adherence platforms where reimbursement is newly opening. The strongest counter-argument is that pipeline scarcity caps the upside—no near-term first-in-class asset targets fibromyalgia's neurobiology, so the market may stay generic-anchored longer than digital-therapy optimists assume. Our analysis suggests the bear case underweights Tonmya's signal value: a first approval in 15 years reopens the indication-specific commercial pathway.
Investors should prioritize care-orchestration assets (digital CBT, telehealth monitoring, integrated pain clinics) over pure-play generic exposure, where pricing power is structurally absent.
Operators should target Asia-Pacific reimbursement pilots and localized generics, where the 8.1% CAGR outpaces every other region by a wide margin.
Manufacturers should invest in diagnostic-pathway partnerships—screening tools, EHR triage—to compress the 6.42-year delay and accelerate treated-population conversion.
What would change our conclusion: a first-in-class neuroinflammation or glial-modulation asset reaching Phase III, or payer mandates that make multimodal bundles the default first-line pathway, would accelerate value migration faster than the base case assumes.
Research Methodology
Primary Research & Industry Fieldwork
Our 70/30 primary-to-secondary research split embedded analyst interviews across the fibromyalgia care value chain, including active pharmaceutical ingredient suppliers, specialty CNS formulators, contract manufacturing organizations, generic distributors and digital therapeutic platform operators. We interviewed VP-level sourcing leads, heads of clinical R&D, regulatory affairs directors and commercial operations executives to validate pricing, adherence and reimbursement assumptions.
Secondary Benchmarking & Public Trade Validation
We triangulated against UN Comtrade pharmaceutical trade flows, WHO and national health statistics, US SEC 10-K filings and investor presentations, FDA and EMA approval databases, and patent expiry registries. Published clinical guidelines from rheumatology and pain societies anchored treatment-pathway and prescribing-share assumptions.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down (macro prevalence and per-patient spend allocation) and bottom-up (manufacturer revenue, prescription volume and channel mix) models, reconciling them at the segment and regional level to produce a single consensus base-year valuation.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for 2024
Bottom-up revenue and prescription triangulation
High
Forecast Horizon
2024–2030 compound projection
Historical CAGR, regression and demand elasticity
High
Regional Distribution
Regional share breakdown
Cross-border trade flow and consumption analysis
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and filings
High
Sources Referenced
U.S. Food and Drug Administration (FDA) approval databases
World Health Organization (WHO) chronic disease and pain statistics
UN Comtrade pharmaceutical trade statistics
European Alliance of Associations for Rheumatology (EULAR) treatment recommendations
Table 14: Europe Fibromyalgia Treatment Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 15: Europe Fibromyalgia Treatment Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Europe Fibromyalgia Treatment Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Frequently Asked Questions
1. How big is the fibromyalgia treatment market?
The global fibromyalgia treatment market was valued at USD 3.6 billion in 2024 and is projected to reach USD 4.88 billion by 2030, growing at a 5.2% compound annual growth rate over the forecast period.
2. Which drug class leads fibromyalgia treatment revenue?
SNRIs lead with 35% of 2024 revenue, approximately USD 1.26 billion, driven by dual-action efficacy on pain and mood. Anticonvulsants follow at 28%, with pregabalin anchoring neuropathic pain prescribing.
3. Which region grows fastest in fibromyalgia treatment?
Asia-Pacific is the fastest-growing region at an 8.1% CAGR through 2030, rising from USD 0.47 billion to USD 0.75 billion, driven by rising awareness, generics access and digital care adoption.
4. What is holding back fibromyalgia market growth?
A mean 6.42-year delay from symptom onset to diagnosis suppresses the treated population, while generic substitution and roughly USD 594 annual per-patient drug costs in Europe limit pricing power and adherence.
5. Who are the leading fibromyalgia treatment companies?
Pfizer leads with over 15% market share, and the top five players—Pfizer, Eli Lilly, Viatris, Teva and AbbVie—collectively held approximately 46% of the market in 2025.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our 70/30 primary-to-secondary research split embedded analyst interviews across the fibromyalgia care value chain, including active pharmaceutical ingredient suppliers, specialty CNS formulators, contract manufacturing organizations, generic distributors and digital therapeutic platform operators. We interviewed VP-level sourcing leads, heads of clinical R&D, regulatory affairs directors and commercial operations executives to validate pricing, adherence and reimbursement assumptions.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Commercial & Market Access Leads
35%
R&D & Clinical Development Heads
30%
Procurement & Sourcing Directors
20%
Regulatory & Medical Affairs
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Branded & Generic Pharmaceutical Manufacturers
45%
Specialty CNS Formulators & CMOs
25%
Digital Therapeutics & Telehealth Operators
18%
Distributors & Pharmacy Networks
12%
Secondary Benchmarking & Public Trade Validation
We triangulated against UN Comtrade pharmaceutical trade flows, WHO and national health statistics, US SEC 10-K filings and investor presentations, FDA and EMA approval databases, and patent expiry registries. Published clinical guidelines from rheumatology and pain societies anchored treatment-pathway and prescribing-share assumptions.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down (macro prevalence and per-patient spend allocation) and bottom-up (manufacturer revenue, prescription volume and channel mix) models, reconciling them at the segment and regional level to produce a single consensus base-year valuation.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for 2024
Bottom-up revenue and prescription triangulation
High
Forecast Horizon
2024–2030 compound projection
Historical CAGR, regression and demand elasticity
High
Regional Distribution
Regional share breakdown
Cross-border trade flow and consumption analysis
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and filings
High
Sources Referenced
U.S. Food and Drug Administration (FDA) approval databases
World Health Organization (WHO) chronic disease and pain statistics
UN Comtrade pharmaceutical trade statistics
European Alliance of Associations for Rheumatology (EULAR) treatment recommendations
Figure 16:
Figure 17: Europe Fibromyalgia Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 18: Europe Fibromyalgia Treatment Market Revenue (Billion), by Care Model 2026 & 2034
Figure 19: Europe Fibromyalgia Treatment Market Revenue Share (%), by Care Model 2026 & 2034
Figure 20: Europe Fibromyalgia Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Fibromyalgia Treatment Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Fibromyalgia Treatment Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 23: Asia Pacific Fibromyalgia Treatment Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 24: Asia Pacific Fibromyalgia Treatment Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 25: Asia Pacific Fibromyalgia Treatment Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 26: Asia Pacific Fibromyalgia Treatment Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 27: Asia Pacific Fibromyalgia Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 28: Asia Pacific Fibromyalgia Treatment Market Revenue (Billion), by Care Model 2026 & 2034
Figure 29: Asia Pacific Fibromyalgia Treatment Market Revenue Share (%), by Care Model 2026 & 2034
Figure 30: Asia Pacific Fibromyalgia Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Fibromyalgia Treatment Market Revenue Share (%), by Country 2026 & 2034
Figure 32: Latin America Fibromyalgia Treatment Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 33: Latin America Fibromyalgia Treatment Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 34: Latin America Fibromyalgia Treatment Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 35: Latin America Fibromyalgia Treatment Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 36: Latin America Fibromyalgia Treatment Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 37: Latin America Fibromyalgia Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 38: Latin America Fibromyalgia Treatment Market Revenue (Billion), by Care Model 2026 & 2034
Figure 39: Latin America Fibromyalgia Treatment Market Revenue Share (%), by Care Model 2026 & 2034
Figure 40: Latin America Fibromyalgia Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Latin America Fibromyalgia Treatment Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Fibromyalgia Treatment Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 43: Middle East & Africa Fibromyalgia Treatment Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 44: Middle East & Africa Fibromyalgia Treatment Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 45: Middle East & Africa Fibromyalgia Treatment Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 46: Middle East & Africa Fibromyalgia Treatment Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 47: Middle East & Africa Fibromyalgia Treatment Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 48: Middle East & Africa Fibromyalgia Treatment Market Revenue (Billion), by Care Model 2026 & 2034
Figure 49: Middle East & Africa Fibromyalgia Treatment Market Revenue Share (%), by Care Model 2026 & 2034
Figure 50: Middle East & Africa Fibromyalgia Treatment Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Fibromyalgia Treatment Market Revenue Share (%), by Country 2026 & 2034
Table 16:
Table 17: Europe Fibromyalgia Treatment Market Revenue Billion Forecast, by Care Model 2020 & 2034
Table 18: Europe Fibromyalgia Treatment Market Revenue Billion Forecast, by Country 2020 & 2034


 Fibromyalgia Treatment Market