 Patient Lifting Equipment Market
 Size, CAGR & 2031 Outlook
Updated On : Nov 19, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Patient Lifting Equipment Market

Amit Mardhekar
Research Analyst

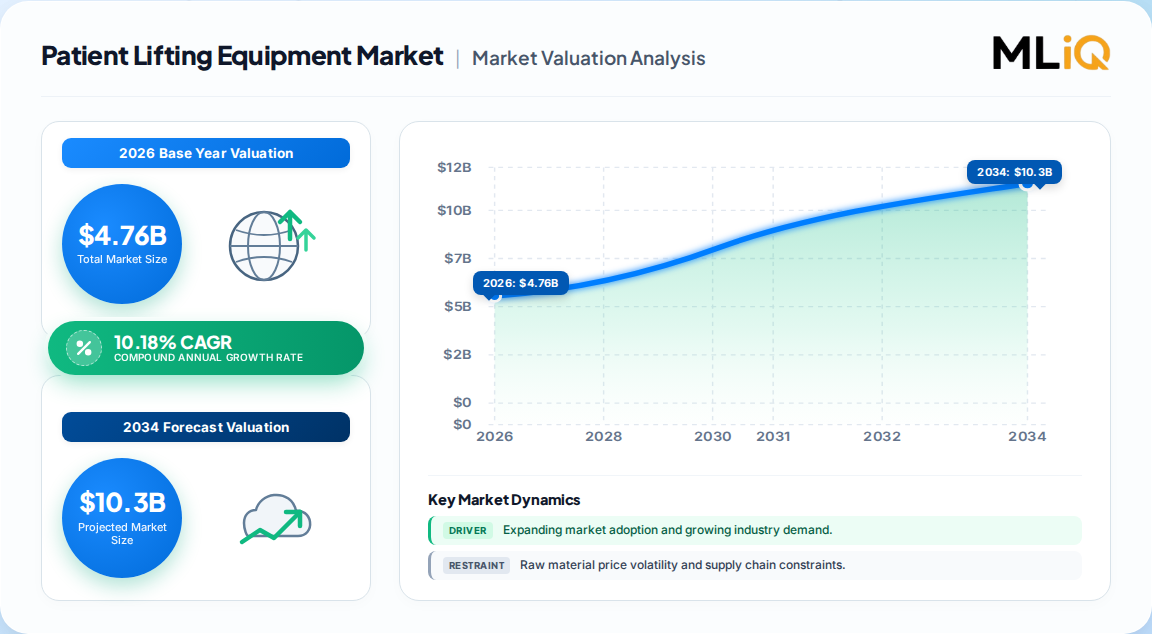
| Year | Market Size |
|---|---|
| 2025 | 4.320 B |
| 2026 | 4.760 B |
| 2027 | 5.240 B |
| 2028 | 5.780 B |
| 2029 | 6.370 B |
| 2030 | 7.020 B |
| 2031 | 7.730 B |

The patient lifting equipment market covers mechanical and powered devices — ceiling lifts, mobile floor lifts, sit-to-stand aids, bath and pool lifts, plus slings and accessories — used to transfer and reposition mobility-impaired patients safely. It exists to prevent caregiver musculoskeletal injury and patient falls, and is increasingly defined by zero-lift compliance rather than discretionary capital spend.
This analysis covers ceiling and overhead track lifts, floor/mobile lifts, sit-to-stand and transfer aids, bath and pool lifts, stair and wheelchair platform lifts, and associated slings across hospitals, long-term and nursing homes, home-care settings and rehabilitation centers, globally. It is segmented by product, mechanism (powered versus manual) and end user.
This analysis does not cover general medical beds, wheelchairs and scooters, ambulatory walking aids, bathroom safety fixtures, or non-mobility rehabilitation devices. Those adjacent categories sit in the broader patient handling equipment pool and are deliberately excluded — which is the single largest reason headline market sizes diverge sharply between published estimates.
One published estimate puts the narrow lift-and-transfer segment at 4.76 Billion USD in 2026, growing to 7.73 Billion USD by 2031 at a 10.18% CAGR. A competing analysis of the wider mechanical-lift category reports only 2.31 Billion USD for 2026 at 7.9% — a gap that is definitional, not contradictory.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 4.76 Billion USD | 2026 | 2031 (7.73 Billion) | 10.18% | Ceiling, floor, sit-to-stand, bath & pool lifts, plus stair/platform lifts; all end users | One published estimate |
| 2.31 Billion USD | 2026 | 2035 (4.42 Billion) | 7.9% | Mechanical lift handling only — floor, ceiling, sit-to-stand, slings; excludes platform lifts | A competing analysis |
| 13.3 Billion USD | 2026 | 2036 (18.5 Billion) | 4.4% | Full patient handling pool including medical beds (41.8% share), wheelchairs, bathroom safety | A third published estimate |
The 10.18% figure is the most defensible for this specific keyword. It is the only estimate whose scope matches lift-and-transfer equipment exactly, and its components are internally consistent: powered systems at 13.21%, home care at 17.21% and APAC at 15.29% mathematically support a blended low-teens rate. The 4.4% figure is diluted by mature bed and wheelchair categories and should not be used to value lift vendors.
The implication for buyers: anyone benchmarking lift demand against the 13.3 Billion headline is overstating their addressable pool roughly threefold. Segment-level diligence matters more than the headline here.
Segmentation is product-led, with mechanism and end user acting as the decisive profit filters. Powered, ceiling-mounted and home-care-facing combinations command both the highest price points and the fastest growth, which is where competitive intensity is concentrating.
| Parent | Children | 2025 share / growth signal |
|---|---|---|
| By Product | Ceiling lifts; Floor/mobile lifts; Sit-to-stand & transfer aids; Bath & pool lifts; Stair & wheelchair platform lifts; Slings & accessories | Ceiling lifts 32.82% share; stair/platform lifts 14.55% CAGR |
| By Mechanism | Powered; Manual | Powered 79.53% share, 13.21% CAGR; manual declining |
| By End User | Hospitals; Long-term & nursing homes; Home-care settings; Rehabilitation centers | Hospitals 48.12% share; home care 17.21% CAGR |
Two structural reads follow. First, ceiling lifts win on installed-base economics — the track is the lock-in, and slings become recurring revenue. Second, sit-to-stand aids are the underappreciated wedge: cheap enough for home budgets, clinical enough for rehabilitation units, and increasingly battery-powered.
North America leads with 38.52% of 2025 revenue, underpinned by enforceable safe-patient-handling legislation, mature reimbursement and near-saturated hospital ceiling-lift penetration. Asia-Pacific is the fastest-growing region at a 15.29% CAGR, driven by hospital build-outs and domestic manufacturing incentives.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.27% |
| Asia-Pacific | 0.24% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
| Region | 2025 revenue share | Growth signal |
|---|---|---|
| North America | 38.52% | Mature; replacement and upgrade cycle dominant |
| Europe | Not disclosed | Regulation-led; strong Nordic and DACH adoption |
| Asia-Pacific | Not disclosed | Fastest at 15.29% CAGR |
| Middle East & Africa | Not disclosed | Infrastructure-led, price sensitive |
| South America | Not disclosed | Emerging; reimbursement fragmented |
Our analysis suggests APAC's 15.29% growth is volume-led, not value-led. Domestic manufacturers in China and India will compress average selling prices even as unit growth accelerates, so revenue-share gains will lag unit-share gains for Western incumbents.
Demographics and regulation are the twin engines: aging and bariatric populations expand the need, while mandatory safe-patient-handling rules convert that need into enforceable purchase orders. The binding constraints are capex and reimbursement in emerging markets, plus persistent training and compliance gaps that blunt return on installed equipment.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Aging and bariatric population | Driver | High | +2.8% CAGR impact; 88M+ US seniors by 2050; bariatric devices rated to 454 kg |
| Mandatory safe-handling regulations | Driver | High | +2.1% CAGR; AORN 2024 guidance, OSHA advisories, AB 1136 |
| Home-based long-term care | Driver | High | +1.9% CAGR; home segment at 17.21% CAGR |
| Powered and IoT-enabled shift | Driver | Medium-high | +1.6% CAGR; justifies premium pricing and raises switching costs |
| Zero-lift hospital policies | Driver | Medium | +1.4% CAGR; short-term procurement trigger |
| Rental / as-a-service models | Driver | Medium | +0.9% CAGR; unlocks cost-sensitive buyers |
| Capex and fragmented reimbursement | Restraint | High | −2.3% CAGR in APAC emerging, LatAm, MEA |
| Insufficient caregiver training | Restraint | High | −1.8% CAGR; devices sit idle or are used unsafely |
| Safety recalls and litigation | Restraint | Medium | −1.2% CAGR; concentrated in North America and Europe |
| Short replacement cycles | Restraint | Low-medium | −0.9% CAGR; budget strain in public systems |
The balance: summed driver impacts exceed summed restraint impacts by roughly 3.9 percentage points, which is why the blended forecast sits in double digits rather than mid-single. But note the asymmetry in timing — the strongest restraints bite in the short term (≤2 years) while the strongest drivers compound over the long term. That means near-term volatility should not be read as structural weakness.
The 52% caregiver back-injury figure attributable to manual handling is the most commercially useful single data point here. It converts a soft benefit (dignity, comfort) into a hard actuarial case that procurement teams can take to a CFO.
The field is medium-concentration and bifurcated: a small set of full-portfolio global incumbents selling integrated lift-plus-service contracts, and a longer tail of specialists winning on ceiling-track systems, bariatric capacity or regional service density. Consolidation is active.
| Vendor | Portfolio strength | Strategic positioning |
|---|---|---|
| Arjo | Ceiling and mobile lifts, bariatric (Citadel Plus, 454 kg), Maxi Move 5 launched 2025 | Full-solution incumbent; service-contract moat |
| Invacare Corporation | Mobile and sit-to-stand lifts, home-care channel | Home-care breadth; pricing pressure exposure |
| Savaria (Handicare) | Stair and platform lifts, ceiling systems | Fastest-growing product adjacency (14.55% CAGR) |
| GF Health Products | Broad handling portfolio, value tier | Distributor-led reach in cost-sensitive markets |
| Enovis (DJO Global) | Rehabilitation and transfer adjacencies | Cross-sell into rehab centers |
| Benmor Medical | Specialist bariatric handling | Niche capacity leadership |
| Guldmann, Joerns, Medline, Stryker, Hill-Rom (Baxter) | Ceiling systems, long-term care, hospital infrastructure | Track installation and facility integration |
Differentiation is no longer in the hardware. Lifting capacity and ergonomics are commoditizing fast, and the durable moats are (1) installed ceiling-track bases that lock in sling and service revenue, (2) trained-service networks that shorten downtime, and (3) data integration with electronic health records that raises switching costs. Our analysis suggests vendors who bundle SafeSet-style alerts and maintenance analytics are capturing a measurable price premium over hardware-only competitors.
Purchase decisions should be anchored on total cost of ownership over a seven-to-ten-year horizon, not unit price. A ceiling lift's track installation, structural certification and sling ecosystem typically outweigh the device cost itself, and slings are a recurring consumable that should be priced into the business case from day one.
Compliance is the second selection filter. In North America, state-level safe-handling statutes and OSHA advisories create documentation obligations; in Europe, manual-handling directives are typically enforced through tender specifications. Buyers should require vendor evidence of regulatory conformity, load-test certification and staff-training programs — training gaps are the single largest cause of poor utilization after purchase.
Three procurement risks deserve explicit attention:
Operators should also stress-test utilization. IoT usage logs frequently reveal that a meaningful share of installed lifts are underused because of workflow friction or untrained staff, which silently erodes the return on a capital-intensive deployment.
The balance of evidence favors the double-digit growth case over the mid-single-digit one, but only for the narrow lift-and-transfer definition. The three independently sourced growth rates — powered systems at 13.21%, home care at 17.21%, APAC at 15.29% — are mutually reinforcing rather than coincidental, which is the signature of a genuine structural shift rather than a forecast artifact.
The strongest counter-argument is that the 10.18% figure may be optimistic in value terms even if unit growth holds. APAC expansion is heavily price-driven, and if domestic Chinese and Indian manufacturers capture volume share, global revenue could grow closer to the 7.9% reported for the narrower mechanical-lift category. We take this seriously: it is the most plausible path to a forecast miss, and it would compress Western incumbents' margins before it compresses their volumes.
Actionable strategy:
What would change our conclusion: evidence of accelerating ASP erosion in APAC exceeding 8% annually, or a sustained slowdown in European tender activity, would justify revising toward the 7–8% band. Precise sub-segment forecasting by country and product line requires the full report's granular dataset.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.18% from 2020-2034 |
| Segmentation |
|
At a 10.18% CAGR from 2026 to 2031, moving from 4.76 Billion USD to 7.73 Billion USD. The powered segment grows faster at 13.21%, and home-care settings fastest of all at 17.21%.
North America, with 38.52% of 2025 revenue, driven by enforceable safe-patient-handling laws and mature reimbursement. Asia-Pacific is the fastest-growing region at a 15.29% CAGR but remains price-sensitive.
Ceiling and overhead track lifts, at 32.82% of 2025 revenue. They dominate because the installed track locks in sling and service revenue for the equipment's working life, creating strong recurring income for vendors.
Scope. Narrow lift-and-transfer definitions produce roughly 4.76 Billion USD for 2026; full patient handling pools including medical beds and wheelchairs report 13.3 Billion USD. The two are not comparable and should not be used interchangeably.
Increasingly marginal. Powered systems held 79.53% of 2025 revenue and grow at 13.21% annually, while manual hoists face replacement pressure from zero-lift policies and caregiver-injury liability concerns across North America and Europe.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study is built on a 70/30 primary-to-secondary research split. Primary fieldwork comprised in-depth interviews with stakeholders across the lift-and-transfer value chain: component and sling manufacturers, ceiling-track and hoist producers, contract assemblers, and global and regional distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D and Product Engineering, Technical Directors responsible for load certification, and Commercial Operations Leads managing tender and rental-contract pipelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement VPs | 35% |
| Heads of R&D & Product Engineering | 30% |
| Technical & Compliance Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Hoist & Ceiling-Track Producers | 40% |
| Component & Sling Manufacturers | 25% |
| Global Distributors | 20% |
| Service & Installation Providers | 15% |
Secondary validation drew on official multilateral trade and standards sources — UN Comtrade, WTO tariff schedules, US ITC data and Eurostat — alongside corporate annual filings (10-K and SEC submissions), investor presentations, patent databases, and recognized non-profit technical standards and healthcare-safety associations. No third-party market-research publications were used as validation inputs.
We ran simultaneous top-down and bottom-up models. The top-down approach allocated macroeconomic and healthcare-spending aggregates across care settings and product categories. The bottom-up approach modeled manufacturer capacity, ex-factory pricing, installation and service revenue, and end-use consumption by facility type. Divergences between the two were reconciled at the segment and country level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |