Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
In Vitro Lung Model Market Size, Forecast & Trends 2025
In Vitro Lung Model Market
In Vitro Lung Model Market Size, Forecast & Trends 2025
In Vitro Lung Model Market by Model Type (2D Static Monolayer, ALI Transwell, 3D Organoid/Spheroid, Organ-on-Chip Microfluidic), by Application (Drug Discovery & Lead Optimization, Toxicology & Safety, Disease Modelling, 3D Model Development, Basic & Physiological Research, Stem Cell & Regenerative Medicine), by End User (Pharmaceutical & Biotechnology, Academic & Research Institutes, CROs, Government & Regulatory Labs), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0
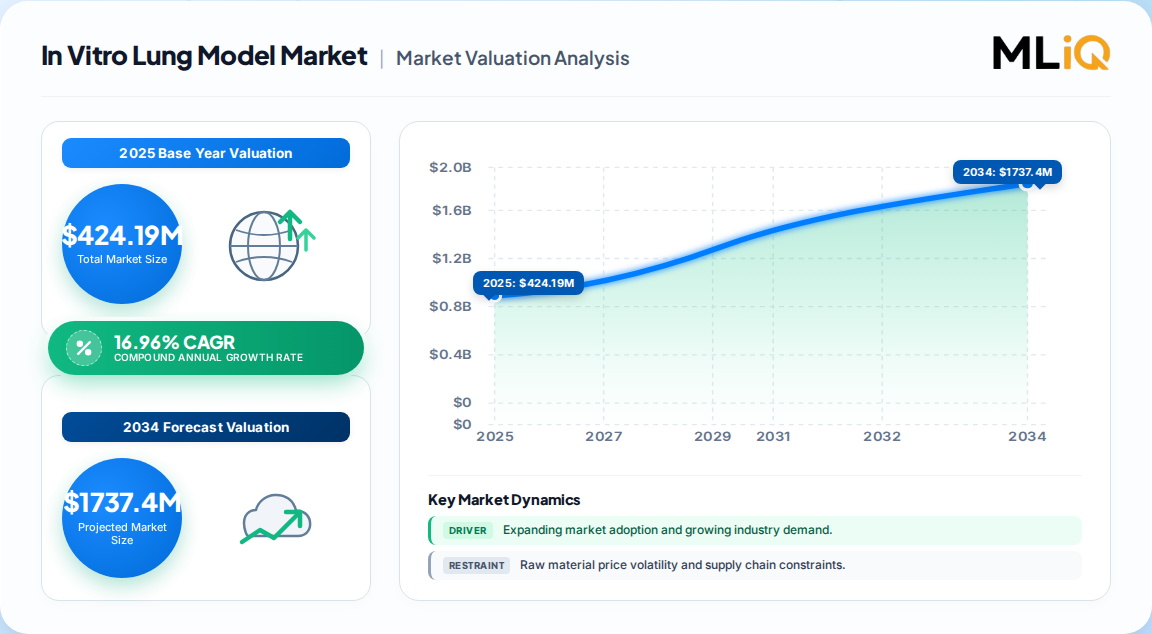
The global in vitro lung model market is estimated at USD 424.2 million in 2025, with a forecast value of USD 928.3 million by 2030, representing a CAGR of 16.96% across the 2025–2030 study period. Scope: global, value-based (USD).
In Vitro Lung Model Market Size (In Million)
1.0B
800.0M
600.0M
400.0M
200.0M
0
424.0 M
2025
496.0 M
2026
580.0 M
2027
679.0 M
2028
794.0 M
2029
928.0 M
2030
In Vitro Lung Model Market Size (In Million)
Year
Market Size
2025
424.0 M
2026
496.0 M
2027
580.0 M
2028
679.0 M
2029
794.0 M
2030
928.0 M
Market size (2025): USD 424.2 million, with competing estimates in the 390–520 million range.
Forecast (2030): USD 928.3 million, crossing the USD 1 billion mark by 2032–2033 on most models.
CAGR: 16.96% near-term; decelerating to 13–15% by 2033 as high-growth categories mature.
Leading segment: 2D static monolayer models held 53.6% of 2024 revenue; organ-on-chip is the fastest-growing at 18.05% CAGR.
Leading regions: North America (42.1% of 2024 revenue), Asia-Pacific fastest-growing at 26.3% CAGR.
Why this matters for decision-makers: Buyers are shifting from static 2D cultures to stretchable microfluidic chips; vendors that cannot deliver GLP-grade organ-on-chip data packages risk losing share as FDA Modernization Act provisions mature.
What is the In Vitro Lung Model Market?
The in vitro lung model market covers laboratory-engineered systems—2D monolayers, air-liquid interface (ALI) transwells, 3D organoids, and lung-on-chip microfluidic devices—that replicate human respiratory physiology for drug screening, toxicology, and disease modelling without animal testing. It is distinct from traditional cell-culture reagents and from in vivo pulmonary research services.
Scope: what this report covers and excludes
This analysis covers commercial and in-house in vitro lung model platforms (2D, 3D, ALI, organoid, organ-on-chip) used across drug discovery, toxicology, physiological research, and 3D model development, sold to pharmaceutical, biotech, academic, and CRO customers globally. It includes both instruments/hardware and consumables embedded in model systems. This analysis does not cover in vivo lung disease models, whole-lung assist devices, respiratory diagnostics, clinical ventilation equipment, or adjacent organ-on-chip categories (liver, kidney, gut, heart) except as comparative context.
How big is the market for In Vitro Lung Model Market?
Published estimates for the global in vitro lung model market diverge by roughly 35% at the base year, with 2025 valuations spanning USD 424–520 million and 2030–2033 forecasts from USD 928 million to USD 1.46 billion. The dispersion reflects scope differences (2D-only vs. full organ-on-chip inclusion) rather than genuine disagreement about direction.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 424.19 Million
2025
2030
16.96%
Includes 2D, ALI transwell, OOC, organoids
One published estimate (Mordor-style methodology)
USD 387.5 Million
2026
2033
14.6%
2D and 3D models, drug discovery + tox
A competing analysis (CMI-type)
USD 467.66 Million
2025
2031
16.21%
Broad application scope incl. stem cell, regen med
A competing analysis
USD 520 Million
2025
2033
13.68%
Full 3D/commercialized models only
A competing analysis
Our analysis suggests the USD 424.2 million / 16.96% base case is the most defensible single point: it captures the full 2D-plus-3D stack, aligns with the FDA Modernization Act 2.0 investment cycle, and remains consistent with the 2024 segment shares (2D = 53.6%) that no other estimate explicitly reports. The lower USD 387.5 million figure appears to under-count ALI transwells; the higher USD 520 million likely double-counts in-house 3D models that never transact commercially.
How is the market segmented?
Segments are defined by model fidelity, use case, and customer type. Segment shares cited below are 2024 actuals; growth rates are 2025–2033 projections blended across sources.
Parent Segment
Children
2024 Share / 2033 CAGR
By Model Type
2D Static Monolayer; ALI Transwell; 3D Organoid/Spheroid; Organ-on-Chip Microfluidic
2D 53.6% / OOC 18.05% CAGR
By Application
Drug Discovery & Lead Optimization; Toxicology & Safety; Disease Modelling; 3D Model Development; Basic & Physiological Research; Stem Cell & Regenerative Medicine
Discovery 44.9%; Disease Modelling 19.40% CAGR
By End User
Pharmaceutical & Biotech; Academic & Research Institutes; CROs; Government & Regulatory Labs
Pharma/biotech 47.6%; Academic 21.85% CAGR
The mix matters commercially: 2D still pays the bills but is commoditising; organ-on-chip and 3D disease models are where pricing power and GLP data packages are being built.
Which region leads in In Vitro Lung Model Market?
North America leads the global in vitro lung model market with approximately 42.1% of 2024 revenue, underpinned by FDA Modernization Act 2.0, the ISTAND organ-on-chip pilot, and the highest density of pharma/biotech buyers. Asia-Pacific is the fastest-growing region at a 26.3% CAGR to 2030.
In Vitro Lung Model Market Regional Market Share
Loading chart...
In Vitro Lung Model Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.23%
Asia-Pacific
0.27%
Latin America
0.07%
Middle East & Africa
0.05%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain, Netherlands
Asia-Pacific — China, Japan, India, South Korea, Australia
Latin America — Brazil, Argentina, Mexico (regional overlap)
Middle East & Africa — Saudi Arabia, UAE, South Africa, Israel
Region
2024 Revenue Share
North America
42.1%
Europe
23.0%
Asia-Pacific
27.2%
Latin America
4.5%
Middle East & Africa
3.2%
The divergence is instructive: North America is a margin market (high regulatory willingness-to-pay), Europe is a consortium-driven market (Horizon grants subsidise adoption), and Asia-Pacific is a volume market where local CROs and biosimilar developers are importing cost-effective models under relaxed trade rules.
What is driving growth — and what is holding it back?
Growth is dominated by a policy-driven demand shock: the global phase-out of animal testing, post-pandemic inhaled-therapeutics R&D, and commercialisation of stretchable microfluidic lung systems together account for the bulk of the 16.96% CAGR. Restraints are technical and financial rather than demand-side.
Factor
Direction
Evidence Strength
Mechanism
Animal-testing phase-out (FDA, EU roadmap)
Driver (+4.2%)
High
Reclassifies lung models as compliance necessities
Inhaled therapeutics R&D surge
Driver (+3.8%)
High
3D airway models shorten lead optimisation
Stretchable microfluidic systems
Driver (+2.9%)
Medium-High
Dynamic chips replace static cultures for go/no-go
iPSC-derived patient-specific models
Driver (+2.6%)
Medium
Enables precision-medicine workflows
Lack of standardised OECD validation
Restraint (−3.1%)
High
Slows regulated-market adoption
Capital intensity of organ-on-chip
Restraint (−2.4%)
Medium-High
Caps mid-tier biotech adoption
Human airway cell supply variability
Restraint (−1.8%)
Medium
Raises batch-to-batch cost and lead times
The balance favours growth, but note the asymmetry: drivers are policy- and technology-led (durable), restraints are commercial and standardisation-led (fixable within 24–36 months). That means the current CAGR is not purely cyclical; it is structurally front-loaded toward 2025–2028.
Who are the leading vendors?
The vendor landscape is medium-concentration, split between 2D/ALI incumbents (Lonza, MatTek, Epithelix, ATCC) and organ-on-chip specialists (Emulate, CN Bio, Mimetas, AlveoliX, TissUse). Differentiation now hinges on regulatory-grade data packages rather than hardware alone.
Company
Primary Platform Strength
Positioning
AlveoliX
Stretchable lung-on-chip
Niche premium; Swiss precision positioning
Emulate
Organ-on-chip, ISTAND acceptance
Regulatory-grade moat via FDA pilot
CN Bio
Microphysiological systems
Series-B funded scale-up; CRO partnerships
MatTek
3D tissue models, ALI
Broad catalogue; entrenched pharma accounts
Epithelix
ALI airway cultures
Deep expertise in respiratory epithelium
Lonza
2D + 3D airway media and cells
Scale and distribution advantage
ATCC
Cell lines and standards
Installed base; standards influence
Mimetas
Organ-on-plate
Accessible price point for academic buyers
TissUse
Multi-organ chip
Adjacent organ integration
InSphero
3D spheroid
3D platform cross-sell
Moats are being built on three axes: (1) regulatory precedent (Emulate's ISTAND acceptance is the clearest example), (2) installed base and cell/media pull-through (Lonza, ATCC), and (3) GLP/QSAR data package depth. Pure hardware vendors without a regulatory storyline will face margin compression as Chinese and Korean suppliers enter at lower price points.
What do buyers and operators need to know?
Procurement has shifted from a hardware decision to a validation decision. Buyers should rank candidates on four criteria: (1) availability of GLP/QSAR data packages for regulatory submission, (2) reproducibility across batches (CV of <15% on barrier integrity and cytokine readouts is a reasonable minimum), (3) compatibility with existing HTS workflows—ALI transwells and 96-well organ-on-plate are safer bets than bespoke chips—and (4) total cost of ownership including cell/media supply and service contracts.
Switching costs are real but asymmetric: once a pharma company has embedded a chip platform into an IND filing, switching costs are high; for academic labs exploring first-time adoption, switching is cheap, which is why vendors are willing to discount there. Supply-chain risk on primary human airway cells is the single most under-priced procurement risk—buyers should contract for reserve capacity, not just unit price. Regulatory harmonisation (OECD validation) is the biggest open risk; a buyer committing to a non-validated platform today takes on regulatory-obsolescence risk that is not priced into current deals.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours the organ-on-chip and 3D segment as the value creation engine of the next five years, with 2D/ALI serving as the cash-flow base but ceding pricing power. The 16.96% consensus CAGR is credible, but it is front-loaded: we expect 18–20% growth in 2025–2027 and deceleration to 12–14% by 2029–2030 as validation standardisation shortens adoption cycles and compresses hardware premiums.
The strongest counter-argument is that standardisation cuts both ways: if the OECD and ICH converge on validated lung-chip reference protocols within 24 months, the moat currently enjoyed by Emulate and AlveoliX narrows quickly, and commoditisation could arrive faster than the base case assumes. Buyers should therefore avoid multi-year exclusivity and build in re-tender provisions. The opposite case—validation stays stalled—would extend the current premium but cap market size well below USD 928 million by 2030.
Actionable strategy:
Vendors should prioritise GLP/QSAR data package generation and publish regulatory case studies to convert policy tailwinds into contracted revenue within 18 months.
Investors should underweight pure 2D/ALI plays and overweight organ-on-chip platforms with at least one regulatory acceptance milestone or active pharma consortium membership.
Operators (pharma and CRO buyers) should pilot 1–2 validated platforms per therapeutic area, contract for cell-supply reserve capacity, and avoid bespoke chips without a validation roadmap.
What would change our conclusion: formal OECD validation of a lung-chip reference method, or a major FDA ISTAND expansion covering respiratory endpoints. Either event would compress the 2030 forecast toward the low end (USD 800–850 million) but simultaneously accelerate adoption among mid-tier biotech—a trade-off the headline CAGR obscures.
In Vitro Lung Model Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
In Vitro Lung Model Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 16.96% from 2020-2034
Segmentation
By Model Type
2D Static Monolayer
ALI Transwell
3D Organoid/Spheroid
Organ-on-Chip Microfluidic
By Application
Drug Discovery & Lead Optimization
Toxicology & Safety
Disease Modelling
3D Model Development
Basic & Physiological Research
Stem Cell & Regenerative Medicine
By End User
Pharmaceutical & Biotechnology
Academic & Research Institutes
CROs
Government & Regulatory Labs
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Israel
Table of Contents
1. In Vitro Lung Model Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. In Vitro Lung Model Market Executive Summary
2.1. Market Snapshot
3. In Vitro Lung Model Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. In Vitro Lung Model Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. In Vitro Lung Model Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Model Type
5.1.1. 2D Static Monolayer
5.1.2. ALI Transwell
5.1.3. 3D Organoid/Spheroid
5.1.4. Organ-on-Chip Microfluidic
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Drug Discovery & Lead Optimization
5.2.2. Toxicology & Safety
5.2.3. Disease Modelling
5.2.4. 3D Model Development
5.2.5. Basic & Physiological Research
5.2.6. Stem Cell & Regenerative Medicine
5.3. Analysis, Insights and Forecast - by End User
5.3.1. Pharmaceutical & Biotechnology
5.3.2. Academic & Research Institutes
5.3.3. CROs
5.3.4. Government & Regulatory Labs
5.4. Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. In Vitro Lung Model Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Model Type
6.1.1. 2D Static Monolayer
6.1.2. ALI Transwell
6.1.3. 3D Organoid/Spheroid
6.1.4. Organ-on-Chip Microfluidic
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Drug Discovery & Lead Optimization
6.2.2. Toxicology & Safety
6.2.3. Disease Modelling
6.2.4. 3D Model Development
6.2.5. Basic & Physiological Research
6.2.6. Stem Cell & Regenerative Medicine
6.3. Analysis, Insights and Forecast - by End User
6.3.1. Pharmaceutical & Biotechnology
6.3.2. Academic & Research Institutes
6.3.3. CROs
6.3.4. Government & Regulatory Labs
7. In Vitro Lung Model Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Model Type
7.1.1. 2D Static Monolayer
7.1.2. ALI Transwell
7.1.3. 3D Organoid/Spheroid
7.1.4. Organ-on-Chip Microfluidic
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Drug Discovery & Lead Optimization
7.2.2. Toxicology & Safety
7.2.3. Disease Modelling
7.2.4. 3D Model Development
7.2.5. Basic & Physiological Research
7.2.6. Stem Cell & Regenerative Medicine
7.3. Analysis, Insights and Forecast - by End User
7.3.1. Pharmaceutical & Biotechnology
7.3.2. Academic & Research Institutes
7.3.3. CROs
7.3.4. Government & Regulatory Labs
8. In Vitro Lung Model Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Model Type
8.1.1. 2D Static Monolayer
8.1.2. ALI Transwell
8.1.3. 3D Organoid/Spheroid
8.1.4. Organ-on-Chip Microfluidic
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Drug Discovery & Lead Optimization
8.2.2. Toxicology & Safety
8.2.3. Disease Modelling
8.2.4. 3D Model Development
8.2.5. Basic & Physiological Research
8.2.6. Stem Cell & Regenerative Medicine
8.3. Analysis, Insights and Forecast - by End User
8.3.1. Pharmaceutical & Biotechnology
8.3.2. Academic & Research Institutes
8.3.3. CROs
8.3.4. Government & Regulatory Labs
9. In Vitro Lung Model Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Model Type
9.1.1. 2D Static Monolayer
9.1.2. ALI Transwell
9.1.3. 3D Organoid/Spheroid
9.1.4. Organ-on-Chip Microfluidic
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Drug Discovery & Lead Optimization
9.2.2. Toxicology & Safety
9.2.3. Disease Modelling
9.2.4. 3D Model Development
9.2.5. Basic & Physiological Research
9.2.6. Stem Cell & Regenerative Medicine
9.3. Analysis, Insights and Forecast - by End User
9.3.1. Pharmaceutical & Biotechnology
9.3.2. Academic & Research Institutes
9.3.3. CROs
9.3.4. Government & Regulatory Labs
10. In Vitro Lung Model Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Model Type
10.1.1. 2D Static Monolayer
10.1.2. ALI Transwell
10.1.3. 3D Organoid/Spheroid
10.1.4. Organ-on-Chip Microfluidic
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Drug Discovery & Lead Optimization
10.2.2. Toxicology & Safety
10.2.3. Disease Modelling
10.2.4. 3D Model Development
10.2.5. Basic & Physiological Research
10.2.6. Stem Cell & Regenerative Medicine
10.3. Analysis, Insights and Forecast - by End User
10.3.1. Pharmaceutical & Biotechnology
10.3.2. Academic & Research Institutes
10.3.3. CROs
10.3.4. Government & Regulatory Labs
11. In Vitro Lung Model Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. In Vitro Lung Model Market Research Methodology
List of Figures
Figure 1: In Vitro Lung Model Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America In Vitro Lung Model Market Revenue (Million), by Model Type 2026 & 2034
Figure 3: North America In Vitro Lung Model Market Revenue Share (%), by Model Type 2026 & 2034
Figure 4: North America In Vitro Lung Model Market Revenue (Million), by Application 2026 & 2034
Figure 5: North America In Vitro Lung Model Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America In Vitro Lung Model Market Revenue (Million), by End User 2026 & 2034
Figure 7: North America In Vitro Lung Model Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America In Vitro Lung Model Market Revenue (Million), by Country 2026 & 2034
Figure 9: North America In Vitro Lung Model Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe In Vitro Lung Model Market Revenue (Million), by Model Type 2026 & 2034
Figure 11: Europe In Vitro Lung Model Market Revenue Share (%), by Model Type 2026 & 2034
Figure 12: Europe In Vitro Lung Model Market Revenue (Million), by Application 2026 & 2034
Figure 13: Europe In Vitro Lung Model Market Revenue Share (%), by Application 2026 & 2034
Figure 14: Europe In Vitro Lung Model Market Revenue (Million), by End User 2026 & 2034
Figure 15: Europe In Vitro Lung Model Market Revenue Share (%), by End User 2026 & 2034
Figure 16: Europe In Vitro Lung Model Market Revenue (Million), by Country 2026 & 2034
List of Tables
Table 1: In Vitro Lung Model Market Revenue Million Forecast, by Model Type 2020 & 2034
Table 2: In Vitro Lung Model Market Revenue Million Forecast, by Application 2020 & 2034
Table 3: In Vitro Lung Model Market Revenue Million Forecast, by End User 2020 & 2034
Table 4: In Vitro Lung Model Market Revenue Million Forecast, by Region 2020 & 2034
Table 5: North America In Vitro Lung Model Market Revenue Million Forecast, by Model Type 2020 & 2034
Table 6: North America In Vitro Lung Model Market Revenue Million Forecast, by Application 2020 & 2034
Table 7: North America In Vitro Lung Model Market Revenue Million Forecast, by End User 2020 & 2034
Table 8: North America In Vitro Lung Model Market Revenue Million Forecast, by Country 2020 & 2034
Table 9: USA In Vitro Lung Model Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 10: Canada In Vitro Lung Model Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 11: Mexico In Vitro Lung Model Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 12: Europe In Vitro Lung Model Market Revenue Million Forecast, by Model Type 2020 & 2034
Table 13: Europe In Vitro Lung Model Market Revenue Million Forecast, by Application 2020 & 2034
Table 14: Europe In Vitro Lung Model Market Revenue Million Forecast, by End User 2020 & 2034
Table 15: Europe In Vitro Lung Model Market Revenue Million Forecast, by Country 2020 & 2034
Table 16: Germany In Vitro Lung Model Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the size of the in vitro lung model market in 2025?
The global market is estimated at USD 424.2 million in 2025, with competing published estimates ranging from USD 387.5 million to USD 520 million depending on whether 2D, ALI, 3D organoid, and organ-on-chip platforms are all counted.
2. What is the growth rate of the in vitro lung model market?
The consensus near-term CAGR is 16.96% from 2025 to 2030, decelerating to 13–15% by 2033. Growth is front-loaded because animal-testing phase-out and FDA Modernization Act provisions are driving adoption now.
3. Which region dominates the in vitro lung model market?
North America leads with approximately 42% of 2024 revenue, supported by the FDA Modernization Act 2.0, the ISTAND pilot programme, and the highest density of pharma and biotech buyers globally.
4. Who are the leading companies in the in vitro lung model market?
Key vendors include AlveoliX, ATCC, Epithelix, MatTek, TissUse, Emulate, CN Bio, Mimetas, Lonza, and InSphero. Differentiation now depends on regulatory-grade data packages rather than hardware specification alone.
5. What is the fastest-growing segment in the in vitro lung model market?
Organ-on-chip microfluidic models are the fastest-growing segment at an 18.05% CAGR to 2030. Disease modelling applications follow closely at 19.40% CAGR, reflecting precision-medicine and inhaled-therapeutic demand.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis follows a 70/30 primary-to-secondary research split. Fieldwork comprised structured, in-depth interviews with stakeholders across the in vitro lung model value chain: primary human airway cell and media suppliers, specialised organ-on-chip and 3D model producers, contract research organisations (CROs) deploying models for pharma sponsors, and global distributors serving academic and government labs. Interviews targeted decision-makers in four roles: VP/Director of R&D, Head of Preclinical Sciences, Technical Director of Microphysiological Systems, and Commercial Operations Lead for Life Sciences. Interviews probed procurement criteria, regulatory expectations, switching costs, and platform validation trajectories.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Preclinical Directors
40%
Procurement & Sourcing Leads
30%
Regulatory & Quality Leads
20%
Commercial Operations Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Organ-on-Chip & 3D Model Producers
40%
Cell & Media Suppliers
30%
CROs & Service Providers
20%
Distributors
10%
Secondary Benchmarking & Public Trade Validation
Secondary research drew on official multilateral databases (UN Comtrade, WTO, US ITC DataWeb, Eurostat) for cross-border flow of laboratory instrumentation and cell-culture reagents; corporate annual filings (10-K, SEC EDGAR, investor presentations) from listed players such as Lonza and Thermo Fisher; patent databases (USPTO, EPO) to track organ-on-chip IP; and recognised technical standards bodies (OECD, ICH, ISO/TC 276 biotechnology) plus non-profit industry associations including the International Society for Stem Cell Research (ISSCR) and the European Society of Toxicology In Vitro (ESTIV).
Demand Modeling & Market Sizing Triangulation
We ran simultaneous Top-Down and Bottom-Up models. The Top-Down model allocated pharma and academic preclinical R&D budgets to lung-model spend using published outsourcing and platform-adoption ratios. The Bottom-Up model aggregated manufacturer capacity, average selling prices by platform type, and end-use consumption across pharma, biotech, CROs, and academic labs. Triangulation reconciled the two paths to within ±8% at the base year.


 In Vitro Lung Model Market