Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Transplantation Market Size, Growth & Forecast to 2032
Transplantation Market
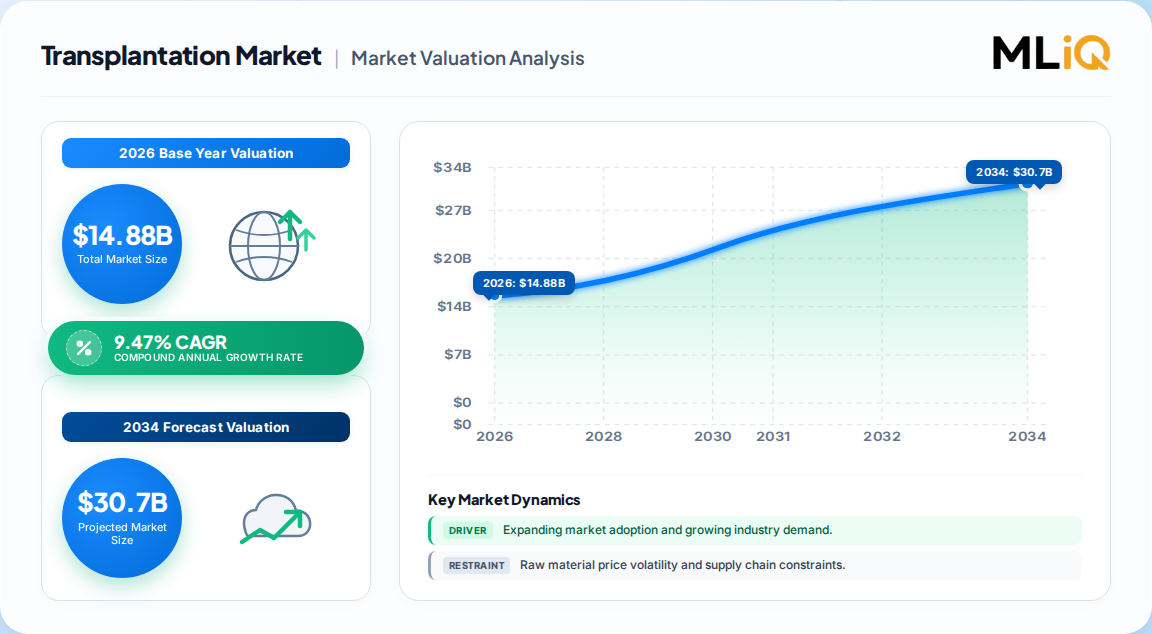
Transplantation Market Size, Growth & Forecast to 2032
Transplantation Market by Product (Immunosuppressive Drugs, Tissue Products, Preservation Solutions and Systems), by Application (Organ Transplantation, Tissue Transplantation, Stem Cell Transplantation), by End User (Hospitals, Transplant Centres, Ambulatory Surgical Centres, Specialty Clinics, Research Institutes), by Technology (Conventional Transplantation, Minimally Invasive Techniques, Machine Perfusion, Immunological Matching), by Procedure Type (Living Donor, Deceased Donor, Xenotransplantation), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0
14.88 Billion — the global transplantation market size in 2026, spanning immunosuppressive drugs, tissue products, preservation solutions and transplant procedures.
25.60 Billion by 2032 — forecast value, implying roughly 10.7 Billion of incremental revenue over the six-year horizon.
9.47% CAGR — the consensus mid-point growth rate for 2027–2032; competing published estimates range from 8.5% to 11.5%.
Immunosuppressive drugs lead product revenue at 38.92% share in 2026, but preservation solutions and systems are the fastest-growing product line at 11.86% CAGR.
North America leads with 37.35% of 2026 revenue; Asia-Pacific is fastest at 11.25% CAGR, with India (10.1%) and China (9.9%) the standout country growth markets.
Leading vendors include Novartis, AbbVie, Teva, Medtronic, Stryker, Zimmer Biomet, Asahi Kasei, BioLife Solutions and Veloxis Pharmaceuticals.
Why this matters for decision-makers: Growth is migrating from chronic drug annuity revenue toward procedure-enabling technology — perfusion, matching software and tissue banking — so vendors that anchor portfolios only in immunosuppression risk share erosion as organ preservation and logistics become the true bottleneck-breakers.
Transplantation Market Size (In Billion)
30.0B
20.0B
10.0B
0
14.88 B
2026
16.28 B
2027
17.82 B
2028
19.51 B
2029
21.36 B
2030
23.38 B
2031
25.60 B
2032
Transplantation Market Size (In Billion)
Year
Market Size
2026
14.88 B
2027
16.28 B
2028
17.82 B
2029
19.51 B
2030
21.36 B
2031
23.38 B
2032
25.60 B
What is the Transplantation Market?
The transplantation market covers the products, drugs, devices and services enabling the transfer of organs, tissues and cells from donor to recipient. It spans immunosuppressive therapies, tissue and organ grafts, preservation and perfusion systems, donor–recipient matching diagnostics, and the hospital and transplant-centre infrastructure that delivers them.
Scope: what this report covers and excludes
This analysis covers global revenue from immunosuppressive drugs, tissue products, preservation solutions and systems, and transplant procedures across organ, tissue and stem cell transplantation, segmented by product, application, end user and geography. This analysis does not cover artificial organ manufacturing, dialysis consumables, general surgical instrumentation, or veterinary transplantation.
How big is the market for Transplantation Market?
Published estimates cluster between 14.9 Billion and 24.0 Billion for the 2025–2026 base period, with forecast values from 25.6 Billion to 58.8 Billion by the early-to-mid 2030s. The spread reflects definitional breadth, not disagreement on direction.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
14.88 Billion
2026
2032 (25.60 Billion)
9.47%
Drugs, tissue products, preservation, procedures
One published estimate
21.9 Billion
2025
2036 (58.8 Billion)
9.4%
Adds stem cell transplantation and xenotransplantation
A competing analysis
5,454.4 Million (US only)
2023
2030 (9,632.5 Million)
8.5%
US revenue, three product lines
A competing analysis
32.94 Billion
—
2030
11.5%
Broad tissue-plus-organ framing
A competing analysis
Our analysis suggests the 14.88 Billion base is the most defensible for procurement and portfolio decisions: it is the narrowest, most auditable definition and its 9.47% CAGR sits almost exactly at the median of the four estimates. The higher 24.0 Billion figure is credible only if stem cell and xenotransplantation revenue are counted as in-scope today — a defensible but aggressive position.
How is the market segmented?
Segmentation follows three commercial axes — what is sold, what it treats, and where the procedure is performed — with product mix shifting fastest toward preservation and perfusion technology.
Parent segment
Children
2026 share / growth signal
By Product
Immunosuppressive drugs (calcineurin inhibitors, antiproliferatives, mTOR inhibitors), tissue products (allograft tissues, corneal, skin, bone), preservation solutions and systems
The implication is uncomfortable for incumbents: the two segments that generate recurring per-patient revenue (drugs, hospital procedures) are the slowest-growing, while the segments that expand the addressable patient pool (perfusion, tissue transplantation, ASC delivery) grow two to three times faster.
Which region leads in Transplantation Market?
North America leads with 37.35% of 2026 revenue, but Asia-Pacific is the fastest-growing region at 11.25% CAGR; the strategic centre of gravity is shifting eastward over the forecast window.
Transplantation Market Regional Market Share
Loading chart...
Transplantation Market Regional Market Share
Region
Market Share (%)
North America
0.37%
Europe
0.24%
Asia-Pacific
0.28%
Latin America
0.06%
Middle East & Africa
0.05%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Spain
Asia Pacific — China, Japan, India, South Korea, Australia
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
Region
2026 revenue share
Growth signal
North America
37.35%
Mature, high transplant volume, advanced procurement
Europe
24%
Steady, structured donation and reimbursement systems
Asia-Pacific
28%
Fastest at 11.25% CAGR; India 10.1%, China 9.9%
Latin America
6%
Emerging transplant infrastructure
Middle East & Africa
5%
Constrained by consent rates and cultural factors
The US alone represented 32.9% of global revenue in 2023 and remains the single largest country market, projected near 9.6 Billion by 2030. This divergence implies that North American vendors hold the installed base but Asian infrastructure build-out will absorb the marginal growth capital.
What is driving growth — and what is holding it back?
Demand expansion from chronic disease and organ failure is structurally stronger than the supply-side restraints, but the restraints cap realized — not potential — revenue. That distinction matters enormously for forecasting.
Factor
Direction
Evidence strength
Mechanism
Chronic disease burden
Driver (+2.1%)
High
Diabetes, hepatitis and cardiovascular disease expand the candidate pool
Organ failure incidence
Driver (+1.8%)
High
End-stage renal disease affects 750,000+ in the US alone
Preservation and perfusion technology
Driver (+1.4%)
High
Extends viability from 6 to 20+ hours; cuts graft dysfunction by 50%
Suppresses consent rates, especially MENA and parts of APAC
API supply fragility (tacrolimus)
Restraint (−1.1%)
Medium
Regional disruption risk in immunosuppressant supply
The balance favors growth, but note the asymmetry: the donor shortage is the single largest force in the model at −2.5%, and it is also the one most directly addressed by the fastest-growing product segments. Technology that rehabilitates marginal organs is effectively monetizing the restraint itself.
Who are the leading vendors?
No vendor holds a dominant share — market concentration is rated medium — and competition splits cleanly between pharmaceutical annuity players and device-and-preservation specialists.
Differentiation is increasingly technological rather than pharmacological: perfusion and preservation vendors are building razor-and-blade annuity models that mirror the economics historically enjoyed by immunosuppressant makers. Our analysis suggests the most defensible franchises sit where drug regimen, preservation logistics and matching data converge.
What do buyers and operators need to know?
Selection criteria are shifting from unit price to total graft economics. A perfusion console that adds 20 hours of preservation window changes organ acceptance rates, discard volumes and inter-regional logistics — value that dwarfs a modest capital discount. Procurement teams should therefore model cost-per-successful-transplant, not cost-per-device.
Switching costs are highest in immunosuppression, where changing a stable regimen carries rejection risk and clinician resistance, and lowest in consumables and preservation media, where validation cycles are short. Regulatory compliance is the sharpest gate: tissue products are subject to rigorous donor screening and traceability regimes, while perfusion devices require validation evidence for extended-criteria organs that many regulators still treat as investigational.
The underexplored risk is supply continuity. Tacrolimus and related API concentration means a single regional disruption can affect thousands of post-transplant patients — a procurement exposure that rarely appears in vendor scorecards but should.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the 14.88 Billion 2026 base and a high-single-digit to low-double-digit CAGR through 2032. Three of four estimates land between 9.4% and 9.5%, and the 11.5% outlier depends on a broader definition rather than a faster market. The strongest counter-argument is that xenotransplantation trial acceleration could trigger step-change supply expansion, but that remains a long-horizon option, not a 2030 revenue line.
Our judgment is that value is rotating from chronic therapy annuity toward procedure-enabling infrastructure. Drug players retain the largest revenue pool but face generic erosion and payer pressure; preservation, perfusion and matching-data vendors are capturing the growth margin while solving the market's binding constraint. Companies straddling all three will outperform specialists over the forecast window.
Actionable strategy for operators and investors:
Prioritize perfusion and preservation assets — the 11.86% CAGR segment directly monetizes the donor shortage and carries device-plus-consumable annuity economics.
Underwrite Asia-Pacific infrastructure, not just volume — India and China growth requires transplant-centre capacity, cold chain and training, which is where early capital earns disproportionate returns.
Build dual-sourced immunosuppressant supply — API concentration is an unhedged patient-safety and margin risk that few competitors have priced.
Evidence that would change this conclusion: sustained xenotransplantation clinical approvals before 2029, or a regulatory shift permitting routine use of extended-criteria organs, either of which would compress preservation pricing power and re-rate the market upward faster than modeled.
Transplantation Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Transplantation Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.47% from 2020-2034
Segmentation
By Product
Immunosuppressive Drugs
Tissue Products
Preservation Solutions and Systems
By Application
Organ Transplantation
Tissue Transplantation
Stem Cell Transplantation
By End User
Hospitals
Transplant Centres
Ambulatory Surgical Centres
Specialty Clinics
Research Institutes
By Technology
Conventional Transplantation
Minimally Invasive Techniques
Machine Perfusion
Immunological Matching
By Procedure Type
Living Donor
Deceased Donor
Xenotransplantation
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Transplantation Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Transplantation Market Executive Summary
2.1. Market Snapshot
3. Transplantation Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Transplantation Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Transplantation Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product
5.1.1. Immunosuppressive Drugs
5.1.2. Tissue Products
5.1.3. Preservation Solutions and Systems
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Organ Transplantation
5.2.2. Tissue Transplantation
5.2.3. Stem Cell Transplantation
5.3. Analysis, Insights and Forecast - by End User
5.3.1. Hospitals
5.3.2. Transplant Centres
5.3.3. Ambulatory Surgical Centres
5.3.4. Specialty Clinics
5.3.5. Research Institutes
5.4. Analysis, Insights and Forecast - by Technology
5.4.1. Conventional Transplantation
5.4.2. Minimally Invasive Techniques
5.4.3. Machine Perfusion
5.4.4. Immunological Matching
5.5. Analysis, Insights and Forecast - by Procedure Type
5.5.1. Living Donor
5.5.2. Deceased Donor
5.5.3. Xenotransplantation
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Transplantation Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product
6.1.1. Immunosuppressive Drugs
6.1.2. Tissue Products
6.1.3. Preservation Solutions and Systems
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Organ Transplantation
6.2.2. Tissue Transplantation
6.2.3. Stem Cell Transplantation
6.3. Analysis, Insights and Forecast - by End User
6.3.1. Hospitals
6.3.2. Transplant Centres
6.3.3. Ambulatory Surgical Centres
6.3.4. Specialty Clinics
6.3.5. Research Institutes
6.4. Analysis, Insights and Forecast - by Technology
6.4.1. Conventional Transplantation
6.4.2. Minimally Invasive Techniques
6.4.3. Machine Perfusion
6.4.4. Immunological Matching
6.5. Analysis, Insights and Forecast - by Procedure Type
6.5.1. Living Donor
6.5.2. Deceased Donor
6.5.3. Xenotransplantation
7. Transplantation Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product
7.1.1. Immunosuppressive Drugs
7.1.2. Tissue Products
7.1.3. Preservation Solutions and Systems
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Organ Transplantation
7.2.2. Tissue Transplantation
7.2.3. Stem Cell Transplantation
7.3. Analysis, Insights and Forecast - by End User
7.3.1. Hospitals
7.3.2. Transplant Centres
7.3.3. Ambulatory Surgical Centres
7.3.4. Specialty Clinics
7.3.5. Research Institutes
7.4. Analysis, Insights and Forecast - by Technology
7.4.1. Conventional Transplantation
7.4.2. Minimally Invasive Techniques
7.4.3. Machine Perfusion
7.4.4. Immunological Matching
7.5. Analysis, Insights and Forecast - by Procedure Type
7.5.1. Living Donor
7.5.2. Deceased Donor
7.5.3. Xenotransplantation
8. Transplantation Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product
8.1.1. Immunosuppressive Drugs
8.1.2. Tissue Products
8.1.3. Preservation Solutions and Systems
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Organ Transplantation
8.2.2. Tissue Transplantation
8.2.3. Stem Cell Transplantation
8.3. Analysis, Insights and Forecast - by End User
8.3.1. Hospitals
8.3.2. Transplant Centres
8.3.3. Ambulatory Surgical Centres
8.3.4. Specialty Clinics
8.3.5. Research Institutes
8.4. Analysis, Insights and Forecast - by Technology
8.4.1. Conventional Transplantation
8.4.2. Minimally Invasive Techniques
8.4.3. Machine Perfusion
8.4.4. Immunological Matching
8.5. Analysis, Insights and Forecast - by Procedure Type
8.5.1. Living Donor
8.5.2. Deceased Donor
8.5.3. Xenotransplantation
9. Transplantation Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product
9.1.1. Immunosuppressive Drugs
9.1.2. Tissue Products
9.1.3. Preservation Solutions and Systems
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Organ Transplantation
9.2.2. Tissue Transplantation
9.2.3. Stem Cell Transplantation
9.3. Analysis, Insights and Forecast - by End User
9.3.1. Hospitals
9.3.2. Transplant Centres
9.3.3. Ambulatory Surgical Centres
9.3.4. Specialty Clinics
9.3.5. Research Institutes
9.4. Analysis, Insights and Forecast - by Technology
9.4.1. Conventional Transplantation
9.4.2. Minimally Invasive Techniques
9.4.3. Machine Perfusion
9.4.4. Immunological Matching
9.5. Analysis, Insights and Forecast - by Procedure Type
9.5.1. Living Donor
9.5.2. Deceased Donor
9.5.3. Xenotransplantation
10. Transplantation Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product
10.1.1. Immunosuppressive Drugs
10.1.2. Tissue Products
10.1.3. Preservation Solutions and Systems
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Organ Transplantation
10.2.2. Tissue Transplantation
10.2.3. Stem Cell Transplantation
10.3. Analysis, Insights and Forecast - by End User
10.3.1. Hospitals
10.3.2. Transplant Centres
10.3.3. Ambulatory Surgical Centres
10.3.4. Specialty Clinics
10.3.5. Research Institutes
10.4. Analysis, Insights and Forecast - by Technology
10.4.1. Conventional Transplantation
10.4.2. Minimally Invasive Techniques
10.4.3. Machine Perfusion
10.4.4. Immunological Matching
10.5. Analysis, Insights and Forecast - by Procedure Type
10.5.1. Living Donor
10.5.2. Deceased Donor
10.5.3. Xenotransplantation
11. Transplantation Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Transplantation Market Research Methodology
List of Figures
Figure 1: Transplantation Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Transplantation Market Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Transplantation Market Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Transplantation Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Transplantation Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Transplantation Market Revenue (Billion), by End User 2026 & 2034
Figure 7: North America Transplantation Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Transplantation Market Revenue (Billion), by Technology 2026 & 2034
Figure 9: North America Transplantation Market Revenue Share (%), by Technology 2026 & 2034
Figure 10: North America Transplantation Market Revenue (Billion), by Procedure Type 2026 & 2034
Figure 11: North America Transplantation Market Revenue Share (%), by Procedure Type 2026 & 2034
Figure 12: North America Transplantation Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Transplantation Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Transplantation Market Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Transplantation Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Transplantation Market Revenue (Billion), by Application 2026 & 2034
Europe Transplantation Market Revenue Share (%), by Application 2026 & 2034
Table 16: Europe Transplantation Market Revenue Billion Forecast, by Product 2020 & 2034
Frequently Asked Questions
1. How big is the transplantation market in 2026?
The global transplantation market is valued at approximately 14.88 Billion in 2026, spanning immunosuppressive drugs, tissue products, preservation solutions and transplant procedures. A broader definition that includes stem cell and xenotransplantation revenue places the figure nearer 24.0 Billion.
2. What is the transplantation market growth rate?
The consensus CAGR is 9.47% for 2027 to 2032, reaching roughly 25.60 Billion by 2032. Competing published estimates range from 8.5% to 11.5%, with the spread driven by definitional breadth rather than directional disagreement.
3. Which segment leads the transplantation market?
Immunosuppressive drugs lead product revenue at 38.92% share in 2026, while organ transplantation accounts for 53.97% of application revenue. However, preservation solutions and systems are the fastest-growing product line at 11.86% CAGR.
4. Which region dominates the transplantation market?
North America holds the largest share at 37.35% of 2026 revenue, led by the United States. Asia-Pacific is the fastest-growing region at 11.25% CAGR, with India and China the standout country-level growth markets.
5. What is holding back the transplantation market?
Organ donor shortage is the largest restraint, with only 3 in 1,000 deaths meeting donation criteria. Antibiotic-resistant post-transplant infections, cultural objections to donation, and API supply fragility for tacrolimus further constrain realized procedure volumes.
6. Who are the leading transplantation market companies?
Key players include Novartis, AbbVie, Teva Pharmaceutical Industries, Medtronic, Stryker, Zimmer Biomet, Asahi Kasei, BioLife Solutions and Veloxis Pharmaceuticals. Market concentration is rated medium, with no single vendor holding a dominant share.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis is built on a 70/30 primary-to-secondary research split. Primary fieldwork comprised structured depth interviews across the transplant value chain, spanning immunosuppressive drug manufacturers, tissue bank and allograft processors, organ preservation and perfusion device makers, transplant-centre procurement groups, and cold-chain logistics distributors. Respondent designations included VP-level Sourcing and Procurement leads, Heads of Transplant R&D, Technical Directors of Preservation Systems, and Commercial Operations Leads at transplant centres. Interviews validated procedure volumes, pricing structures, formulary dynamics and device adoption timelines.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
35%
R&D & Technical Directors
30%
Commercial Operations Leads
20%
Regulatory & Quality Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Immunosuppressive Drug Manufacturers
35%
Tissue Banks & Allograft Processors
25%
Preservation & Perfusion Device Makers
22%
Transplant Centres & Distributors
18%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral and regulatory datasets — UN Comtrade and WTO trade statistics, US ITC tariff and import records, Eurostat healthcare trade data — alongside corporate annual filings (10-K and investor presentations), patent databases covering perfusion and immunosuppression IP, and technical standards published by recognized non-profit standards bodies and clinical transplant associations. All secondary benchmarks were cross-checked against primary interview findings before inclusion.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down and bottom-up models. The top-down approach allocated macroeconomic healthcare expenditure and procedure-volume data across product and application segments; the bottom-up approach modeled manufacturer capacity, realized pricing, end-user consumption and per-patient immunosuppression spend. Divergences between the two were reconciled through weighted triangulation informed by primary interview evidence.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for 2026
Bottom-up production and revenue triangulation
High
Forecast Horizon
2027–2032 compound projection
Historical CAGR, regression analysis and demand elasticity
High
Regional Distribution
Regional share breakdown
Cross-border trade flow analysis and regional consumption
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and commercial filings
High
Sources Referenced
UN Comtrade — international trade statistics for pharmaceutical and medical device flows
US ITC — tariff and import data for transplant-related products
Eurostat — European healthcare expenditure and procedure statistics
WHO and national organ procurement registries — donation and transplantation volume benchmarks
Figure 17:
Figure 18: Europe Transplantation Market Revenue (Billion), by End User 2026 & 2034
Figure 19: Europe Transplantation Market Revenue Share (%), by End User 2026 & 2034
Figure 20: Europe Transplantation Market Revenue (Billion), by Technology 2026 & 2034
Figure 21: Europe Transplantation Market Revenue Share (%), by Technology 2026 & 2034
Figure 22: Europe Transplantation Market Revenue (Billion), by Procedure Type 2026 & 2034
Figure 23: Europe Transplantation Market Revenue Share (%), by Procedure Type 2026 & 2034
Figure 24: Europe Transplantation Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Transplantation Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Transplantation Market Revenue (Billion), by Product 2026 & 2034
Figure 27: Asia Pacific Transplantation Market Revenue Share (%), by Product 2026 & 2034
Figure 28: Asia Pacific Transplantation Market Revenue (Billion), by Application 2026 & 2034
Figure 29: Asia Pacific Transplantation Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Transplantation Market Revenue (Billion), by End User 2026 & 2034
Figure 31: Asia Pacific Transplantation Market Revenue Share (%), by End User 2026 & 2034
Figure 32: Asia Pacific Transplantation Market Revenue (Billion), by Technology 2026 & 2034
Figure 33: Asia Pacific Transplantation Market Revenue Share (%), by Technology 2026 & 2034
Figure 34: Asia Pacific Transplantation Market Revenue (Billion), by Procedure Type 2026 & 2034
Figure 35: Asia Pacific Transplantation Market Revenue Share (%), by Procedure Type 2026 & 2034
Figure 36: Asia Pacific Transplantation Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Transplantation Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Latin America Transplantation Market Revenue (Billion), by Product 2026 & 2034
Figure 39: Latin America Transplantation Market Revenue Share (%), by Product 2026 & 2034
Figure 40: Latin America Transplantation Market Revenue (Billion), by Application 2026 & 2034
Figure 41: Latin America Transplantation Market Revenue Share (%), by Application 2026 & 2034
Figure 42: Latin America Transplantation Market Revenue (Billion), by End User 2026 & 2034
Figure 43: Latin America Transplantation Market Revenue Share (%), by End User 2026 & 2034
Figure 44: Latin America Transplantation Market Revenue (Billion), by Technology 2026 & 2034
Figure 45: Latin America Transplantation Market Revenue Share (%), by Technology 2026 & 2034
Figure 46: Latin America Transplantation Market Revenue (Billion), by Procedure Type 2026 & 2034
Figure 47: Latin America Transplantation Market Revenue Share (%), by Procedure Type 2026 & 2034
Figure 48: Latin America Transplantation Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Latin America Transplantation Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Transplantation Market Revenue (Billion), by Product 2026 & 2034
Figure 51: Middle East & Africa Transplantation Market Revenue Share (%), by Product 2026 & 2034
Figure 52: Middle East & Africa Transplantation Market Revenue (Billion), by Application 2026 & 2034
Figure 53: Middle East & Africa Transplantation Market Revenue Share (%), by Application 2026 & 2034
Figure 54: Middle East & Africa Transplantation Market Revenue (Billion), by End User 2026 & 2034
Figure 55: Middle East & Africa Transplantation Market Revenue Share (%), by End User 2026 & 2034
Figure 56: Middle East & Africa Transplantation Market Revenue (Billion), by Technology 2026 & 2034
Figure 57: Middle East & Africa Transplantation Market Revenue Share (%), by Technology 2026 & 2034
Figure 58: Middle East & Africa Transplantation Market Revenue (Billion), by Procedure Type 2026 & 2034
Figure 59: Middle East & Africa Transplantation Market Revenue Share (%), by Procedure Type 2026 & 2034
Figure 60: Middle East & Africa Transplantation Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Transplantation Market Revenue Share (%), by Country 2026 & 2034
Table 17: Europe Transplantation Market Revenue Billion Forecast, by Application 2020 & 2034
Table 18: Europe Transplantation Market Revenue Billion Forecast, by End User 2020 & 2034
Table 19: Europe Transplantation Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 20: Europe Transplantation Market Revenue Billion Forecast, by Procedure Type 2020 & 2034
Table 21: Europe Transplantation Market Revenue Billion Forecast, by Country 2020 & 2034


 Transplantation Market