Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Musculoskeletal Disorders Drugs Market: $126B by 2032
Musculoskeletal Disorders Drugs Market
Musculoskeletal Disorders Drugs Market: $126B by 2032
Musculoskeletal Disorders Drugs Market by Drug Type (Analgesics, DMARDs, Corticosteroids, Biologics & biosimilars, Osteoporosis medications, Others), by Route of Administration (Oral, Parenteral), by Distribution Channel (Hospital pharmacies, Drug stores & retail pharmacies, Online providers), by Condition (Rheumatoid arthritis, Osteoarthritis, Osteoporosis, Psoriatic arthritis, Ankylosing spondylitis, Fibromyalgia), by North America (United States, Canada, Mexico), by Europe (Germany, United Kingdom, France, Italy, Spain), by Asia-Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 263
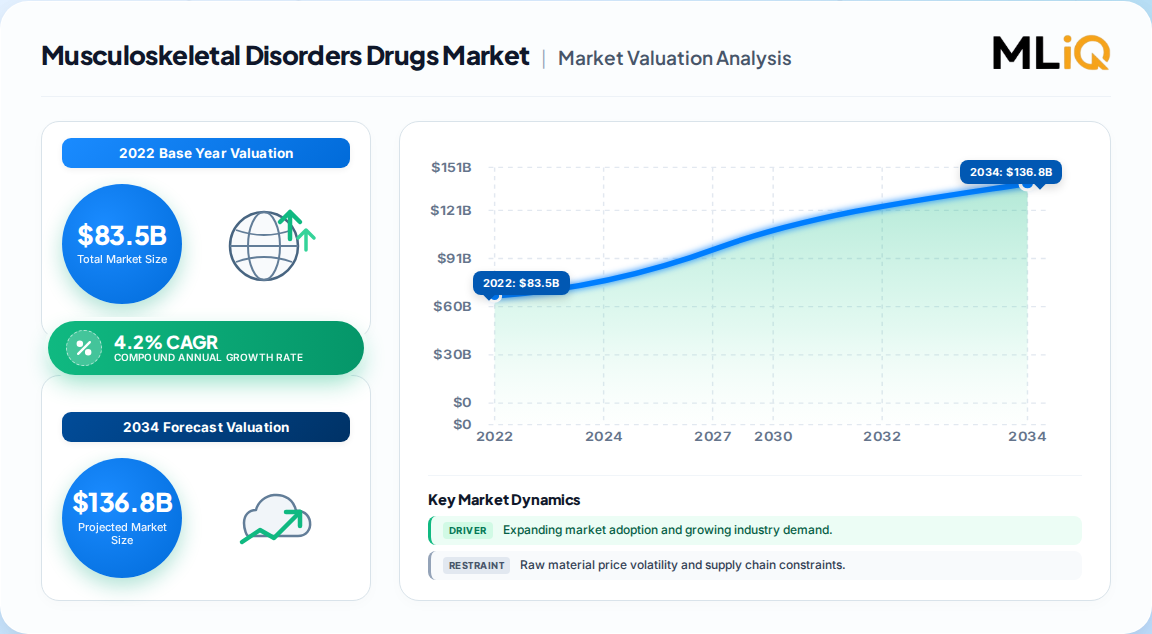
$83.5 billion was the global musculoskeletal disorders drugs market size in 2022, on track to $126.0 billion by 2032.
Forecast growth runs at a 4.2% CAGR across the 2023–2032 window, a mature but highly defensible trajectory.
Analgesics held the largest drug-type share in 2022, sustained by low cost and over-the-counter access.
Parenteral administration led in 2022; oral is the fastest-growing route as patients shift to self-managed care.
Drug stores & retail pharmacies dominate distribution, while online providers post the steepest growth.
North America commanded roughly 42% of 2032 revenue; Asia-Pacific is the fastest-growing region.
Why this matters for decision-makers: the market rewards portfolio breadth over novelty; vendors with only premium biologics exposure face slower volume growth than peers pairing analgesics with DMARDs.
Musculoskeletal Disorders Drugs Market Size (In Billion)
150.0B
100.0B
50.0B
0
83.50 B
2022
87.00 B
2023
90.70 B
2024
94.50 B
2025
98.50 B
2026
102.6 B
2027
106.9 B
2028
Musculoskeletal Disorders Drugs Market Size (In Billion)
Year
Market Size
2022
83.50 B
2023
87.00 B
2024
90.70 B
2025
94.50 B
2026
98.50 B
2027
102.6 B
2028
106.9 B
What is the Musculoskeletal Disorders Drugs Market?
The musculoskeletal disorders drugs market covers pharmaceutical therapies—analgesics, DMARDs, corticosteroids, biologics and bone agents—used to manage pain, inflammation and structural degradation across arthritis, osteoporosis, back pain and related conditions. It spans oral and parenteral routes sold through hospital, retail and online channels.
Scope: what this report covers and excludes
This analysis sizes global demand for prescription and over-the-counter pharmaceuticals indicated for musculoskeletal disorders, segmented by drug type, route of administration and distribution channel across five regions. It covers branded, generic and biosimilar molecules. This analysis does not cover orthopedic implants, surgical devices, physical therapy services, diagnostic imaging or nutraceutical supplements.
How big is the market for Musculoskeletal Disorders Drugs Market?
One published estimate puts the market at $83.5 billion in 2022, reaching $126.0 billion by 2032 at 4.2% CAGR. A competing analysis sizes a narrower $9.65 billion scope at 6.9% CAGR through 2030, while a third places the 2029 horizon at $109.4 billion.
The $126 billion figure is the most defensible because its scope explicitly includes analgesics, which alone anchor the largest revenue pool. The $9.65 billion estimate narrows to disease-specific medications and should not be read as a market total. Our analysis suggests the two 4.2% CAGRs corroborate each other, giving buyers a reliable planning baseline; the 6.9% generic-only figure reflects a small base, not superior momentum.
How is the market segmented?
Segmentation follows three commercial axes: drug class determines margin and pricing power, route shapes delivery cost and adherence, and channel governs access and reimbursement. Drug type and route are the two dimensions buyers should weight most heavily in portfolio decisions.
Which region leads in Musculoskeletal Disorders Drugs Market?
North America leads with approximately 42% of 2032 revenue, underpinned by a large patient pool, concentrated innovator presence and favorable reimbursement. Asia-Pacific is the fastest-growing region, driven by aging demographics and expanding healthcare infrastructure.
Europe (Germany, United Kingdom, France, Italy, Spain)
Asia-Pacific (China, Japan, India, South Korea, Australia)
Latin America (Brazil, Argentina, Colombia)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Region
Share of 2032 revenue
North America
42%
Europe
26%
Asia-Pacific
22%
Latin America
6%
Middle East & Africa
4%
The divergence matters: North America monetizes through price and biologics adoption, while Asia-Pacific monetizes through volume. Our analysis suggests vendors cannot run one commercial playbook across both—US launch economics depend on formulary access, whereas Asia-Pacific returns hinge on generics scale and retail distribution depth.
What is driving growth — and what is holding it back?
Prevalence and demographics are the primary growth engines: 1.71 billion people globally live with musculoskeletal conditions, and aging populations structurally expand the treated pool. Restraints are access- and cost-driven rather than demand-driven, which caps downside risk to the forecast.
The competitive field splits into three tiers: diversified innovators with immunology franchises, rheumatology specialists, and generic manufacturers. Concentration is moderate—no single player holds pricing power across the full drug-type spectrum.
Company
Archetype
Primary moat
Johnson & Johnson
Diversified innovator
Immunology portfolio breadth and channel reach
Pfizer
Diversified innovator
Scale, pipeline and acquisition-driven expansion
AbbVie
Immunology specialist
Biologic franchise depth and payer relationships
Amgen
Biologics specialist
Biosimilar and inflammation pipeline
Novartis
Diversified innovator
Portfolio diversity across musculoskeletal indications
UCB
Rheumatology specialist
Focused neurology and immunology positioning
Differentiation rests on biologic formulation know-how and payer contracting rather than molecular novelty alone. Analgesics remain commoditized, so defensible margins accrue to firms owning the DMARD and biologic layers. This divergence implies mid-tier generics players will struggle to fund innovation without a biosimilar pipeline.
What do buyers and operators need to know? (Decision Support)
Procurement decisions should prioritize formulary access and total cost of therapy over headline molecule pricing. In musculoskeletal care, adherence and route convenience drive real-world cost more than acquisition price, so buyers should model oral-versus-parenteral switching explicitly.
Regulatory compliance differs sharply by channel. Online providers face verification and pharmacovigilance obligations that retail pharmacies largely absorb through existing infrastructure, raising the effective cost of digital entry. Switching costs are highest for biologic patients already stabilized on therapy, making retention economics more valuable than new-patient acquisition.
Supply risk concentrates in parenteral manufacturing, where capacity constraints and single-source fill-finish arrangements create exposure. Buyers should qualify dual sources for high-volume injectables and stress-test reimbursement assumptions, particularly where government pricing reforms are pending.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a steady-state, volume-led expansion rather than a disruptive-growth thesis. The two independent 4.2% CAGRs reinforce each other, and the demand base is demographic rather than cyclical, which makes the forecast unusually resilient. The strongest counter-argument is that biologics pricing pressure could compress value growth below the stated CAGR; however, that risk affects revenue per patient, not patient volume, and is partly offset by biosimilar-led access expansion.
Our analysis suggests the market's real asymmetry sits in Asia-Pacific, where prevalence is high but treated rates remain low. Vendors that build retail and online distribution ahead of demand will capture share as access improves, while those waiting for hospital infrastructure will cede the first-mover advantage. Conversely, North America remains a margin market, not a growth market—positioning there should defend share rather than chase expansion.
Actionable strategy for operators and investors:
Prioritize a dual portfolio pairing commoditized analgesics for volume with DMARDs and biosimilars for margin.
Build online and retail distribution capability in Asia-Pacific before reimbursement matures there.
Qualify dual-source fill-finish capacity for injectables to insulate against parenteral supply shocks.
What would change this conclusion: a sustained step-down in biologic net pricing or a regulatory shock to reimbursement in North America would pull the growth trajectory below 4%, warranting a defensive rebalance toward generics.
Table 14: Europe Musculoskeletal Disorders Drugs Market Revenue Billion Forecast, by Drug Type 2020 & 2034
Table 15: Europe Musculoskeletal Disorders Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Frequently Asked Questions
1. How large is the musculoskeletal disorders drugs market?
The market was valued at $83.5 billion in 2022 and is projected to reach $126.0 billion by 2032, growing at a 4.2% CAGR over the 2023–2032 forecast period.
2. What is the fastest-growing segment in this market?
Oral administration is the fastest-growing route, driven by lower cost and ease of use, while online providers represent the fastest-growing distribution channel as e-commerce access expands.
3. Which region dominates musculoskeletal disorders drug sales?
North America holds roughly 42% of global revenue, supported by a large patient base and favorable reimbursement, while Asia-Pacific registers the highest growth rate.
4. Who are the leading companies in the market?
Johnson & Johnson, Pfizer, AbbVie, Amgen, Novartis and UCB lead through immunology franchises, biologic pipelines and payer relationships across major markets.
5. What is restraining market growth?
Limited treatment access in low-income countries, healthcare professional shortages and high R&D plus regulatory costs are the principal restraints, though demand itself remains structurally strong.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applied a 70/30 primary-to-secondary split, prioritizing direct engagement with market participants. In-depth interviews were conducted across the value chain, including active pharmaceutical ingredient suppliers, specialty formulation manufacturers, contract manufacturing organizations, and global pharmaceutical distributors. Decision-maker designations interviewed included VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both supply-side and demand-side perspectives informed the sizing.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Commercial & Sourcing Leads
38%
R&D & Medical Affairs Directors
34%
Regulatory & Market Access Managers
28%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Innovator & Biologic Manufacturers
45%
Generic & Biosimilar Producers
30%
Distributors & Retail Pharmacies
25%
Secondary Benchmarking & Public Trade Validation
Findings were benchmarked against official multilateral databases, including UN Comtrade, WTO tariff and trade statistics, US ITC data and Eurostat pharmaceutical trade series. Corporate annual filings (10-K and SEC submissions), investor presentations, and patent databases were reviewed to validate pipeline activity and revenue concentration. Recognized industry associations and pharmacovigilance standards provided technical context for therapeutic classification.
Demand Modeling & Market Sizing Triangulation
Sizing was triangulated simultaneously through a top-down allocation of macroeconomic and therapeutic-segment expenditure and a bottom-up build from manufacturer capacity, product pricing and end-use consumption modeling. Divergences between the two approaches were reconciled at the molecule-class level before aggregation.


 Musculoskeletal Disorders Drugs Market