 Urinalysis Test Market
 Size, Share & Forecast to 2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 256

Amit Mardhekar
Research Analyst

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Urinalysis Test Market
Amit Mardhekar
Research Analyst

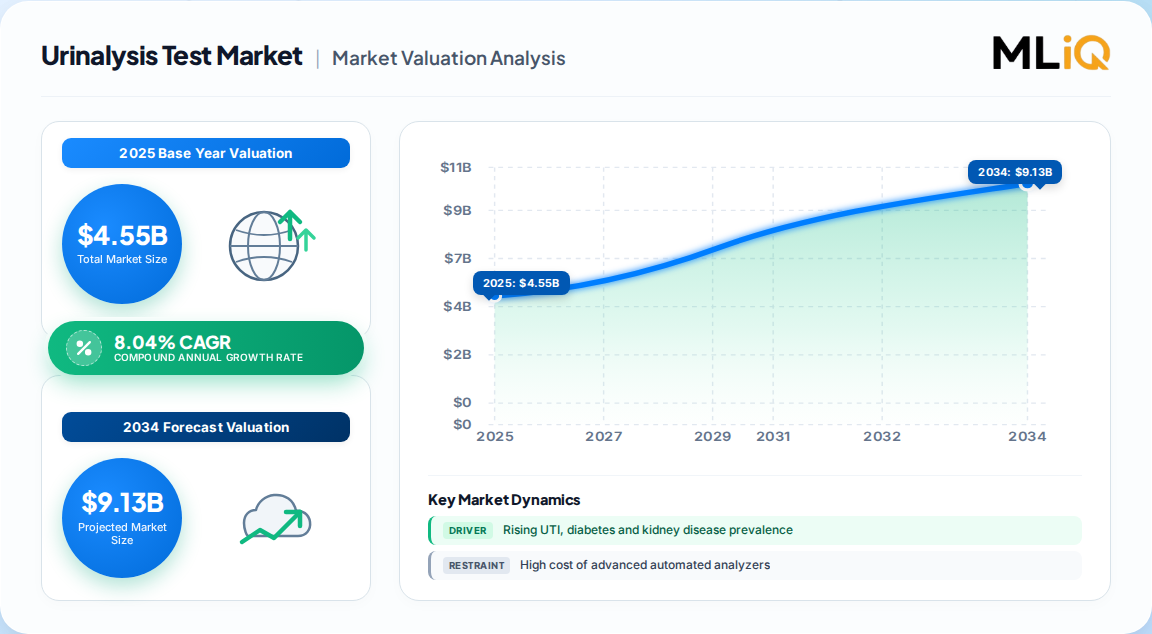
| Year | Market Size |
|---|---|
| 2025 | 4.550 B |
| 2026 | 4.910 B |
| 2027 | 5.310 B |
| 2028 | 5.730 B |
| 2029 | 6.190 B |
| 2030 | 6.690 B |
| 2031 | 7.230 B |

The Urinalysis Test Market covers diagnostic products and services used to physically, chemically and microscopically examine urine to detect urinary tract infections, kidney disorders, diabetes and metabolic disease. It spans automated analyzers, reagent strips, consumables and point-of-care or home-based testing kits sold to hospitals, labs and consumers.
This analysis covers urinalysis instruments, consumables and reagents across hospital, clinical laboratory, home care and research end uses globally. It excludes blood glucose monitoring, clinical chemistry analyzers outside urine workflows, pregnancy-test retail hardware, and standalone microbiology culture testing, which are addressed in adjacent diagnostic reports.
Estimates cluster tightly: the global Urinalysis Test Market sits near 4.55 Billion in 2025, with forecasts converging on 8–9 Billion by the mid-2030s at a ~7.8–8.04% CAGR. The divergence is largely scope-based rather than demand-based.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 4.4 Billion | 2024 | 2030 | 7.8% | Instruments, consumables, full application set, global | One published estimate |
| 5.1 Billion | 2026 | 2030 | 7.8% | Same scope, forward-dated base | One published estimate |
| 4.55 Billion | 2025 | 2034 | 8.04% | Products + consumables, disease & fertility screening | A competing analysis |
| 9.13 Billion | 2034 | 2034 | 8.04% | Terminal value of above series | A competing analysis |
Our analysis treats the 2025 figure of ~4.55 Billion as most defensible: it reconciles the 2024 base of 4.4 Billion with observed 7–8% growth and sits between the two publishers' anchor points. The wider 9.13 Billion terminal value reflects a longer horizon, not aggressive demand assumptions. Buyers should anchor decisions on the CAGR band, not the terminal number.
Segmentation is product-led, with application and end-use layers determining purchasing behavior. Consumables generate recurring revenue while instruments drive competitive positioning.
| Parent segment | Children |
|---|---|
| Product | Instruments, Consumables (reagent strips, dipsticks, disposables) |
| Application | Disease screening (UTI, diabetes, kidney), Fertility & pregnancy testing, Others |
| End use | Hospitals, Clinical laboratories, Home care, Research & academics, Others |
Consumables' dominance (~61.5–78.6%) is a structural moat: installed-base analyzers lock buyers into proprietary strips. The instruments segment, growing ~7.45% CAGR, matters less for revenue than for controlling that razor-and-blades cycle. Our analysis suggests fertility and home-testing sub-segments (~8.86% CAGR) are the fastest-moving niche and the most under-served commercially.
North America leads the Urinalysis Test Market with roughly 38% of global revenue, underpinned by advanced diagnostics infrastructure, high chronic-disease burden and rapid adoption of automated analyzers. Asia Pacific follows as the fastest-growing region at ~9.85% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) | Growth signal |
|---|---|---|
| North America | ~38% | Mature, replacement-led |
| Europe | ~24% | Stable, regulatory-driven |
| Asia Pacific | ~27% | Fastest (~9.85% CAGR) |
| Latin America | ~6% | Emerging, price-sensitive |
| Middle East & Africa | ~5% | Infrastructure-constrained |
Our analysis suggests Asia Pacific's 27% share understates its strategic weight: rising chronic-disease prevalence and improving facilities will shift volume growth decisively eastward, making local manufacturing partnerships the decisive competitive lever.
Growth is driven by rising UTI, diabetes and kidney-disease prevalence, automation and digital/AI diagnostics, and expanding point-of-care and home testing. Restraints centre on high analyzer costs in low-resource settings and inconsistent reimbursement and standards.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Chronic disease prevalence | Driver | High | ~800M diabetics globally; ~1/3 with kidney comorbidity |
| Automated & AI analyzers | Driver | High | Digital microscopy cuts manual error, boosts throughput |
| Point-of-care / home testing | Driver | Medium-High | 150M annual UTI cases; app-based kits |
| High instrument cost | Restraint | Medium | Limits adoption in low/middle-income facilities |
| Reimbursement inconsistency | Restraint | Medium | Slows standardized adoption across regions |
The balance favors growth: demand-side drivers are structural and demographically anchored, while restraints are largely cost and policy frictions that automation and consumable pricing can erode over time. Our analysis implies the binding constraint is not demand but affordability and workflow integration in emerging markets.
The competitive field is moderately concentrated, with large diagnostics majors competing on automation platforms and mid-tier specialists competing on consumables price and regional reach.
| Vendor | Positioning | Strategic strength |
|---|---|---|
| Siemens Healthineers | Automated sediment analysis | Digital microscopy, neural-network imaging |
| Sysmex Corporation | Automated urine workflow | Broad installed base, collaborations |
| Beckman Coulter (Danaher) | Integrated lab systems | Global lab channel depth |
| F. Hoffmann-La Roche | Diagnostics breadth | Reagent and platform integration |
| ARKRAY | Urinalysis specialists | Cost-competitive consumables |
| Mindray | Emerging-market instruments | Price-performance in APAC |
| EKF Diagnostics | Point-of-care | Portable, decentralized testing |
Differentiation rests on two moats: proprietary consumable lock-in and validated AI/digital-microscopy accuracy. Our analysis suggests mid-tier vendors will compete hardest on consumable pricing and reimbursement partnerships rather than instrument features, where majors hold a durable edge.
Selection should prioritize total cost of ownership over sticker price: analyzers are loss-leaders for proprietary reagent strips, so buyers must model multi-year consumable contracts, not instrument outlay alone. Confirm closed vs. open reagent systems before commitment, as closed systems raise switching costs materially.
Procurement risk concentrates in supply continuity of strips and disposables, plus regulatory clearance variance across FDA and EMA regimes. Buyers should verify digital-microscopy validation evidence and EHR/cloud integration capability, since lab workflow disruption is the dominant hidden cost. For operators entering emerging markets, local manufacturing or distribution partnerships mitigate affordability and logistics risk.
The balance of evidence favors a consumables-anchored growth thesis: the market's ~8% trajectory is durable, but value accrues disproportionately to vendors controlling reagent-strip lock-in and automated-workflow integration. The strongest counter-argument is that home and point-of-care testing could commoditize urine diagnostics and erode lab-based consumable pricing — a real risk, but our analysis judges it a complement over the forecast horizon rather than a substitute.
What would change this conclusion: sustained reimbursement cuts in North America, or regulatory fast-tracking of consumer self-tests that bypasses lab channels. Absent those signals, the consumables-led, APAC-weighted thesis holds. Precise sub-segment forecasting and vendor benchmarking require the full report's granular model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.04% from 2020-2034 |
| Segmentation |
|
The global Urinalysis Test Market was valued near 4.55 Billion in 2025 and is projected to reach roughly 9.13 Billion by 2034. Estimates converge on a 7.8–8.04% CAGR, with scope differences explaining publisher divergence.
North America leads with approximately 38% of global revenue, supported by advanced diagnostics infrastructure. Asia Pacific is the fastest-growing region at nearly 9.85% CAGR, driven by rising chronic disease and improving healthcare facilities.
Fertility and pregnancy testing is growing fastest at roughly 8.86% CAGR, while instruments expand near 7.45%. Consumables remain the largest product segment at 61.5–78.6% of revenue due to recurring reagent-strip demand.
Key players include Siemens Healthineers, Sysmex, Beckman Coulter (Danaher), F. Hoffmann-La Roche, ARKRAY, Mindray and EKF Diagnostics. Differentiation rests on automated-workflow integration and proprietary consumable lock-in.
Rising UTI, diabetes and kidney-disease prevalence, automation and AI diagnostics, and expanding point-of-care and home testing are primary drivers. High instrument costs and inconsistent reimbursement restrain adoption in lower-resource settings.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a disciplined 70/30 primary-to-secondary split. In-depth interviews were conducted across the urinalysis value chain, spanning reagent and consumable producers, automated analyzer manufacturers, contract manufacturers of diagnostic strips, and global laboratory distributors. Within these organizations we engaged decision-makers designated as VP of Sourcing, Heads of Diagnostics R&D, Technical Directors, and Commercial Operations Leads, capturing both procurement economics and clinical workflow realities.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Diagnostics R&D Directors | 30% |
| Technical & Lab Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Reagent & Consumable Producers | 40% |
| Analyzer Manufacturers | 30% |
| Contract Strip Manufacturers | 18% |
| Laboratory Distributors | 12% |
Findings were cross-validated against official multilateral trade and standards databases including UN Comtrade, WTO, US ITC and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards bodies. This triangulation anchors volume and pricing assumptions to auditable public records.
We run simultaneous Top-Down allocation (macroeconomic and healthcare-segment spend) and Bottom-Up modeling (manufacturer capacity, product pricing, and end-use consumption), reconciling the two to a single defensible base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |