 Pediatric Home Healthcare Market
: 2026 Size, Share & 2035 Outlook
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Pediatric Home Healthcare Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 52.50 B |
| 2026 | 56.40 B |
| 2027 | 60.30 B |
| 2028 | 64.50 B |
| 2029 | 69.00 B |
| 2030 | 73.80 B |
| 2031 | 78.90 B |

Pediatric home healthcare is the delivery of skilled nursing, rehabilitation therapy, and personal care assistance to infants, children, and adolescents with chronic, complex, or post-acute needs in the home. It substitutes institutional care with family-centered, coordinated clinical support.
The analysis covers global pediatric home healthcare delivered by agencies and provider networks: skilled nursing, rehabilitation therapy, personal care assistance, and adjacent respiratory/enteral support services. It spans indications including cancer, respiratory disease, cardiovascular disease, hearing disorders, and other complex conditions. This analysis does not cover adult home healthcare, pediatric hospital inpatient care, pediatric hospice as a standalone category, or medical device manufacturing.
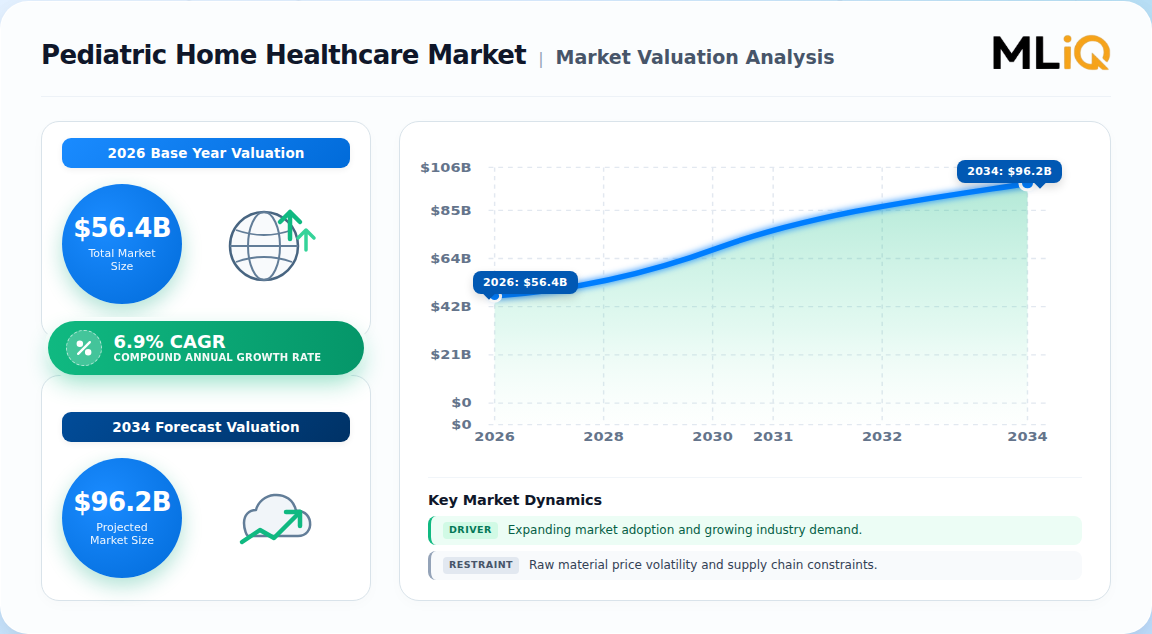
The market was valued near 56.4 Billion in 2026, on a consensus trajectory toward 103 Billion by 2035 at 6.9% CAGR. Competing estimates diverge mainly on base-year and service-scope definition.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 52.5 Billion to 103 Billion | 2025 | 2035 | 6.9% | Broad agency-model pediatric home care | One published estimate |
| 42.6 Billion to 85.8 Billion | 2022 | 2032 | 7.25% | Skilled nursing, personal care, rehab, others | A competing analysis |
| 28.97 Billion to 42.53 Billion | 2024 | 2030 | 6.61% | Service-segmented global agency market | Another published estimate |
| 12.53 Billion (U.S. only) | 2023 | 2030 | 7.85% | U.S. rehabilitation and skilled nursing | A separate published benchmark |
Our analysis treats the 52.5–56.4 Billion band as most defensible because it aligns with U.S. spending of 169.4 Billion across total home health in 2024 and a pediatric share consistent with Medicaid HCBS growth of 12.8% year-over-year. The lower 28.97 Billion figure likely excludes respiratory equipment and enteral support, which materially widens the addressable base.
Pediatric home healthcare segments by service, indication, and care provider. Service mix is the primary determinant of revenue and margin, with rehabilitation therapy leading in value and skilled nursing leading in growth.
| Parent Segment | Children |
|---|---|
| By Service | Skilled Nursing, Personal Care Assistance, Rehabilitation Therapy, Others |
| By Indication | Cancer, Respiratory Diseases, Cardiovascular Diseases, Hearing Disorders, Others |
| By Care Provider | Home Health Agencies, Private Duty Nursing, Specialty Providers |
Rehabilitation therapy dominated the U.S. revenue mix at 60.27% in 2023, driven by cerebral palsy, autism, and premature-infant developmental needs. Skilled nursing, by contrast, accounts for 67.3% of Medicaid pediatric home health spend, signaling where reimbursement pulls hardest.
North America leads with roughly 38% of global revenue, underpinned by Medicaid HCBS waivers, CHIP coverage, and dense provider networks. Asia Pacific is the fastest-growing region as specialist reach expands through telehealth.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.22% |
| Asia-Pacific | 0.27% |
| South America | 0.06% |
| Middle East & Africa | 0.07% |
Our analysis suggests Asia Pacific's growth will hinge less on disease prevalence than on licensing simplification and telehealth-enabled specialist leakage from urban centers. Latin America and MEA remain small but are where per-capita service intensity is lowest and upside highest.
Growth is driven by rising pediatric chronic-condition prevalence (45.7% of U.S. children ages 3–17 in 2023) and Medicaid HCBS expansion up 12.8% year-over-year. Restraints are workforce scarcity and reimbursement lag, not demand.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising pediatric chronic disease | Growth | High | Recurring skilled care demand, not episodic |
| Medicaid HCBS expansion | Growth | High | Converts clinical need into reimbursable volume |
| Telehealth-enabled therapy | Growth | Medium | Extends specialist reach, lowers per-visit cost |
| Pediatric nursing shortage | Restraint | High | 37.9% of families report discharge delays |
| Reimbursement rate pressure | Restraint | High | Margin compression despite volume |
| Regulatory fragmentation | Restraint | Medium | Slows multi-state and cross-border scaling |
Callout — the binding constraint: When referrals exceed nursing coverage, payers may authorize care but families still face delayed starts or reduced hours. Market sizing that ignores this gap overstates realizable revenue.
The market is highly fragmented; the top five players — Aveanna, BAYADA, BrightStar Care, Interim Healthcare, and MGA Homecare — collectively hold only 4.7% share, with Aveanna leading at ~2.3% in 2025.
| Vendor | Positioning | Competitive Moat |
|---|---|---|
| Aveanna Healthcare | National pediatric and adult home care | Payer contracts, scale, respiratory integration |
| BAYADA Home Health Care | Private-duty nursing and pediatrics | Clinical training and caregiver retention |
| BrightStar Care | Franchise-based pediatric services | Local brand and referral relationships |
| Interim Healthcare | Broad home care and staffing | Multi-market footprint |
| MGA Homecare | High-acuity pediatric nursing | Specialist clinical depth |
Differentiation rests on caregiver credentialing depth and payer authorization throughput, not price. Scale advantages accrue primarily to operators that spread compliance, recruiting, and contracting costs across multiple states.
Buyers must scrutinize clinical credentialing, authorization speed, and continuity-of-care models above all else. Pediatric high-acuity capability cannot be added through general staffing; it requires specialist licensure and family-facing judgment.
Procurement risk concentrates in service gaps: an agency may win on rate but fail on shift coverage, forcing families back to institutional settings. Switching costs are high because care plans, authorization histories, and caregiver relationships transfer poorly. Regulatory compliance — EPSDT mandates, state Medicaid waiver variation, and cross-border licensing — raises market entry cost and favors multi-market operators with dedicated compliance infrastructure. Buyers should weight continuity metrics and backup staffing guarantees over headline pricing.
The balance of evidence favors operators that treat clinician supply as the primary strategic asset. Demand is structurally underwritten by chronic-condition prevalence and Medicaid expansion; the market's failure mode is delivery capacity, not referral scarcity. This is a supply-constrained market masquerading as a demand-driven one.
The strongest counter-argument is that reimbursement reform could reprice the market faster than workforce investment pays off, compressing margins before scale benefits arrive. We acknowledge that risk, but rate pressure affects all operators — favoring those with multi-payer diversification and lower-cost regional delivery.
Actionable strategy:
Evidence that would change our conclusion: a sustained acceleration in CMS reimbursement updates above wage inflation would shift the thesis from supply-constraint defense toward volume-race offense.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.9% from 2020-2034 |
| Segmentation |
|
The global market is estimated at approximately 56.4 Billion in 2026, with a 6.9% CAGR projected to 2035. Estimates vary by scope, especially whether respiratory and enteral support services are included.
North America leads with about 38% of global revenue, supported by Medicaid HCBS waivers and CHIP coverage. Asia Pacific is the fastest-growing region as telehealth extends specialist reach.
Skilled nursing is the fastest-growing service segment, driven by high-acuity pediatric demand and Medicaid spend concentration. Rehabilitation therapy remains the largest segment by revenue.
Aveanna Healthcare leads with roughly 2.3% share. BAYADA, BrightStar Care, Interim Healthcare, and MGA Homecare follow, with the top five holding only 4.7% collectively.
The pediatric nursing shortage is the primary binding constraint. Approximately 37.9% of families with medically complex children report extended hospital stays due to unavailable in-home nursing.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews across the pediatric home healthcare value chain: pediatric home health agencies, private-duty nursing providers, rehabilitation therapy networks, respiratory and enteral equipment suppliers, and payer/waiver administrators. Decision-maker interviews include VP-level Operations, Directors of Clinical Services, Payer Contracting Leads, and Chief Nursing Officers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Clinical & Nursing Directors | 40% |
| Operations & Payer Contracting Leads | 35% |
| Regulatory & Compliance Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Pediatric Home Health Agencies | 40% |
| Private-Duty Nursing Providers | 30% |
| Rehabilitation Therapy Networks | 20% |
| Respiratory & Enteral Suppliers | 10% |
We triangulate against official multilateral and national databases including CMS Medicaid spending data, UN Comtrade trade flows for home medical equipment, US ITC filings, and Eurostat health expenditure statistics. Corporate annual filings (SEC 10-K), investor presentations, and patent activity inform capacity and strategy validation. Recognized standards bodies and clinical associations, including the American Academy of Pediatrics and the National Association for Home Care & Hospice, anchor definitions.
We run simultaneous Top-Down macroeconomic allocation (health spending by segment and country) and Bottom-Up modeling of agency capacity, caregiver headcount, and per-hour pricing. Divergence is reconciled through payer reimbursement data and waiver enrollment figures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up agency revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade and consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports and capacity mapping | High |