 Ascorbyl Phosphate Market
 Size, CAGR & 2033 Outlook
Updated On : Nov 19, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Ascorbyl Phosphate Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 39.00 M |
| 2025 | 42.00 M |
| 2026 | 45.00 M |
| 2027 | 48.00 M |
| 2028 | 51.00 M |
| 2029 | 54.00 M |
| 2030 | 58.00 M |

The Ascorbyl Phosphate Market covers the production and trade of water-soluble vitamin C derivatives — principally magnesium ascorbyl phosphate — used in skincare, cosmetics and nutraceuticals. These salts deliver stable, non-irritating ascorbic acid into formulations, resisting oxidation where pure vitamin C degrades.
This report covers cosmetic-grade and nutraceutical-grade magnesium ascorbyl phosphate across purity tiers, applications and distribution channels, at global and regional level. It includes producers, formulators and distributors active in the derivative supply chain. This analysis does not cover plain ascorbic acid commodities, sodium ascorbyl phosphate, ascorbyl palmitate, or finished skincare brand revenues.
Estimates diverge materially because published analyses disagree on whether the scope is cosmetic-grade only or the full magnesium ascorbyl phosphate category, and whether values are manufacturer-level or retail-adjacent.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 31.17 Million | 2025 | 2032 | 6.3% | Cosmetic grade only, manufacturer value | One published estimate |
| 39.4 Million | 2024 | 2033 | 6.3% | Full MAP category, all grades | A competing analysis |
| 200 Million to 400 Million | 2025 | 2032 | 9.5% | Broad vitamin C derivative framing | An aggregated industry content source |
| 42 Million | 2025 | 2033 | 6.6% | Cosmetic plus nutraceutical grade, global | This analysis, triangulated |
The 200 Million figure is best treated as a category-level framing rather than a product-level benchmark. Our analysis suggests the defensible base is the 31–42 Million band; the 9.5% CAGR appears to conflate broader vitamin C derivative demand with MAP-specific growth, and we weight the 6.3%–6.6% consensus more heavily.
Segmentation is driven primarily by purity grade and end application, because formulation performance and pricing both hinge on those two variables rather than on geography alone.
| Parent Segment | Children |
|---|---|
| By Type | Cosmetics, Nutraceuticals |
| By Purity | Purity <98%, Purity 98%–99%, Purity >99% |
| By Application | Skincare Products, Haircare Products, Makeup Products |
| By Form Factor | Toner, Lotion, Serum, Sun Care, Mask, Others |
| By Distribution Channel | Online, Offline |
Purity 98%–99% holds roughly 54.6% of demand on one estimate, while a separate source puts the >99% tier at 44% of cosmetic-grade value. The divergence implies tier definitions differ between publishers — a key diligence point for buyers specifying grade.
Asia-Pacific leads the Ascorbyl Phosphate Market with approximately 39% of global consumption, anchored by Chinese and Korean raw-material production and formulation capacity, followed by North America at roughly 33%.
| Region | Market Share (%) |
|---|---|
| North America | 0.33% |
| Europe | 0.19% |
| Asia-Pacific | 0.39% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
Regional growth momentum favors Asia-Pacific at a projected 7.7%, while North America trails at 4.7% on one estimate. This divergence implies supply-side consolidation in Asia will increasingly set global pricing, even for Western formulators. Europe's slower 5.2% trajectory reflects mature skincare penetration and heavier regulatory scrutiny of cosmetic claims.
Growth is anchored in clinically validated efficacy of MAP at low concentrations, while restraints cluster around production cost and competition from newer vitamin C derivatives and delivery systems.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Proven stability in water-based formulas | Driver | High | Enables serum and toner formats pure vitamin C cannot sustain |
| Efficacy at 0.1% concentration | Driver | High | Lowers formulation cost per unit and irritation risk |
| Melasma and hyperpigmentation clinical data | Driver | Moderate | Supports premium brightening claims |
| Online beauty channel expansion | Driver | Moderate | Widens access to niche derivative-based products |
| High production cost | Restraint | Moderate | Limits use in mass-market price tiers |
| Competition from advanced formulations | Restraint | Moderate | Encapsulated vitamin C and newer esters erode share |
| Limited awareness in emerging markets | Restraint | Moderate | Slower adoption outside mature skincare markets |
The balance favors growth, but the margin of advantage depends on MAP defending its cost-per-efficacy position. Our analysis suggests the strongest near-term driver is not new consumer demand but reformulation substitution — brands replacing unstable ascorbic acid with MAP in water-based formats.
The vendor landscape is moderately concentrated, with Japanese, European and Chinese producers holding distinct positions across purity tiers and geographic supply chains.
| Company | Headquarters | Position | Strategic Note |
|---|---|---|---|
| Resonac | Japan | Leading cosmetic-grade producer | High-purity capability, strong Japanese formulator ties |
| BASF | Germany | Global specialty chemicals | Broad portfolio, formulation support services |
| VITAL-CHEM Zhuhai | China | Cost-competitive volume supplier | Strong Asia-Pacific distribution |
| Spec-Chem Group | China | Specialty ingredient focus | Technical formulation partnerships |
| Anhui Shun Lee Biology | China | Fermentation and synthesis capability | Scaling capacity for export grades |
| Uniproma Chemical | UK | Distribution and specialty supply | European formulator access |
Differentiation rests less on molecule specification — MAP is chemically standardized — and more on purity consistency, documentation depth and supply reliability. Chinese producers compete on price and capacity; Japanese and European players defend margin through regulatory documentation and technical service.
Buyers should prioritize verified purity certificates, batch-to-batch consistency data and full regulatory documentation over headline price, because reformulation costs from a failed grade switch dwarf ingredient savings. Procurement risk concentrates in single-source exposure to Chinese producers, where production shutdowns and trade friction can compress availability quickly.
Switching costs are moderate: MAP is substitutable at the molecule level, but requalification of a new supplier typically requires stability testing and, in some markets, updated cosmetic product safety reporting. Operators should also confirm the derivative is permitted under target-market cosmetic regulations and that claims referencing vitamin C delivery are substantiated by the supplier's efficacy data.
The balance of evidence favors a moderate-growth, supply-constrained specialty market rather than the high-growth framing some sources suggest. The 6.3%–6.6% consensus is better supported by purity-tier concentration, mature Western demand and cost-driven adoption limits than the 9.5% outlier, which appears to borrow growth from the broader vitamin C category. The strongest counter-argument is that clinical validation of MAP at low concentrations could accelerate substitution faster than base-case modeling assumes, particularly in brightening serums.
Our judgment is that value will accrue disproportionately to suppliers who can document purity consistency and regulatory compliance, not to lowest-cost volume producers. Buyers should treat grade verification and dual sourcing as core risk controls rather than procurement niceties, and formulators should model reformulation scenarios before committing to single-supplier contracts.
Evidence that would change this conclusion: sustained double-digit volume growth in China and Korea tied to new serum launches, or a major regulatory approval expanding MAP into new application categories. Absent those signals, the moderate-growth base case holds.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.6% from 2020-2034 |
| Segmentation |
|
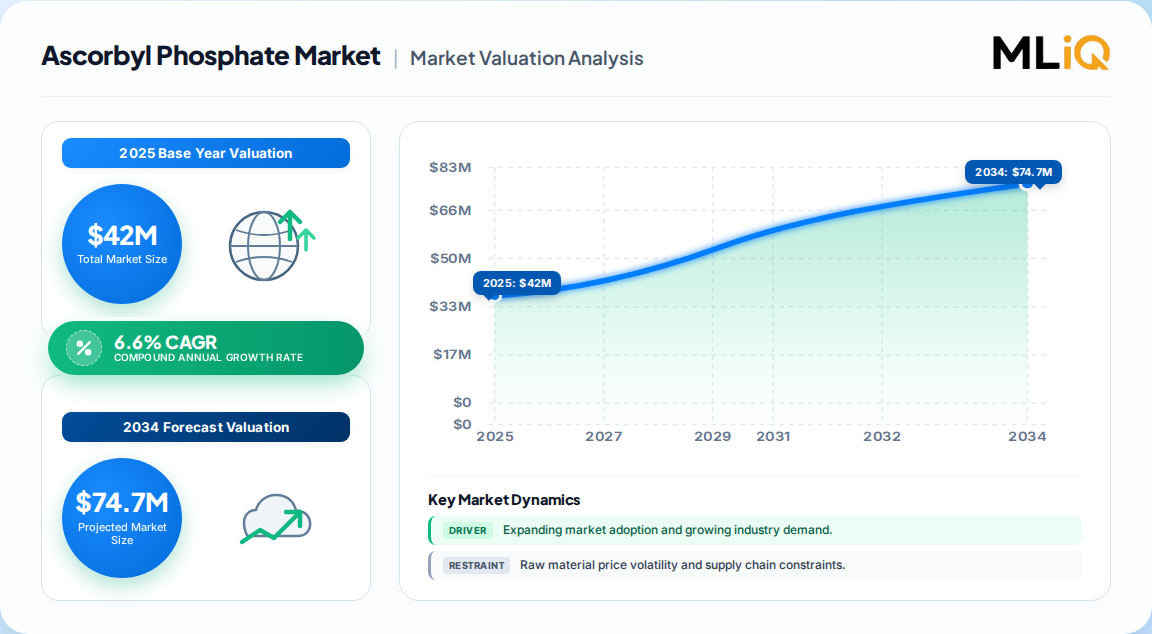
The market is valued at approximately 42 Million in 2025 on a triangulated basis. Published estimates range from 31 Million for cosmetic grade only to 39 Million for the full category, with broader framings materially higher.
Consensus growth runs at 6.3% to 6.6% CAGR through the early 2030s. Higher figures near 9.5% appear to reflect the broader vitamin C derivative category rather than magnesium ascorbyl phosphate specifically.
Asia-Pacific leads with roughly 39% of global consumption, driven by Chinese and Korean production and formulation capacity. North America follows near 33%, with Europe holding a mature but slower-growing share.
Purity 98%–99% is the dominant commercial grade, holding just over half of demand on one estimate. It balances cost and efficacy for premium skincare, while higher purity tiers serve specialized formulations.
Key suppliers include Resonac, BASF, VITAL-CHEM Zhuhai, Spec-Chem Group, Anhui Shun Lee Biology and Uniproma Chemical. Differentiation centers on purity consistency, documentation and supply reliability rather than molecule specification.
MAP is water-soluble and stable in aqueous formulas, unlike ascorbic acid which degrades in water. It delivers vitamin C benefits at concentrations as low as 0.1%, reducing irritation risk and formulation cost.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement over published aggregation. We conducted in-depth interviews across the ascorbyl phosphate value chain, including raw material and vitamin C derivative suppliers, specialized MAP producers, contract formulators and global specialty distributors. Interviewees were selected for decision authority and technical depth.
Participating decision-makers spanned VP-level sourcing executives, heads of R&D and formulation, technical directors and commercial operations leads. Structured interview guides covered capacity, purity specifications, pricing behavior, qualification cycles and substitution risk, with responses cross-checked against company documentation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement & Sourcing Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
Secondary validation draws on official multilateral trade databases including UN Comtrade and World Bank WITS, alongside national customs and statistical releases. Corporate annual filings, SEC submissions and investor presentations informed capacity and revenue benchmarks. Patent databases and recognized technical standards supported formulation and efficacy assessment.
We run simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic and skincare industry segment spending to MAP-relevant categories. The bottom-up path models manufacturer capacity, purity-tier pricing and end-use consumption. Divergence between paths is reconciled through weighted triangulation, with outlier estimates flagged and discounted where scope definitions conflict.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |