Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Active Pharmaceutical Ingredients Market Outlook 2026
Active Pharmaceutical Ingredients Market
Active Pharmaceutical Ingredients Market Outlook 2026
Active Pharmaceutical Ingredients Market by Type of Synthesis (Synthetic, Biotech/Biological, Highly Potent (HPAPI)), by Type of Manufacturer (Captive/In-House, Merchant/Outsourced), by API Type (Innovative, Generic), by Molecule Size (Small Molecule, Large Molecule/Biologic), by Therapeutic Application (Oncology, Cardiology, Anti-diabetics, CNS & Anesthesia, Infectious Disease, Biologics, Others), by Type of Drug (Prescription, OTC), by North America (United States, Canada, Mexico), by Europe (Germany, UK, France, Italy, Switzerland), by Asia-Pacific (China, India, Japan, South Korea, Singapore), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0
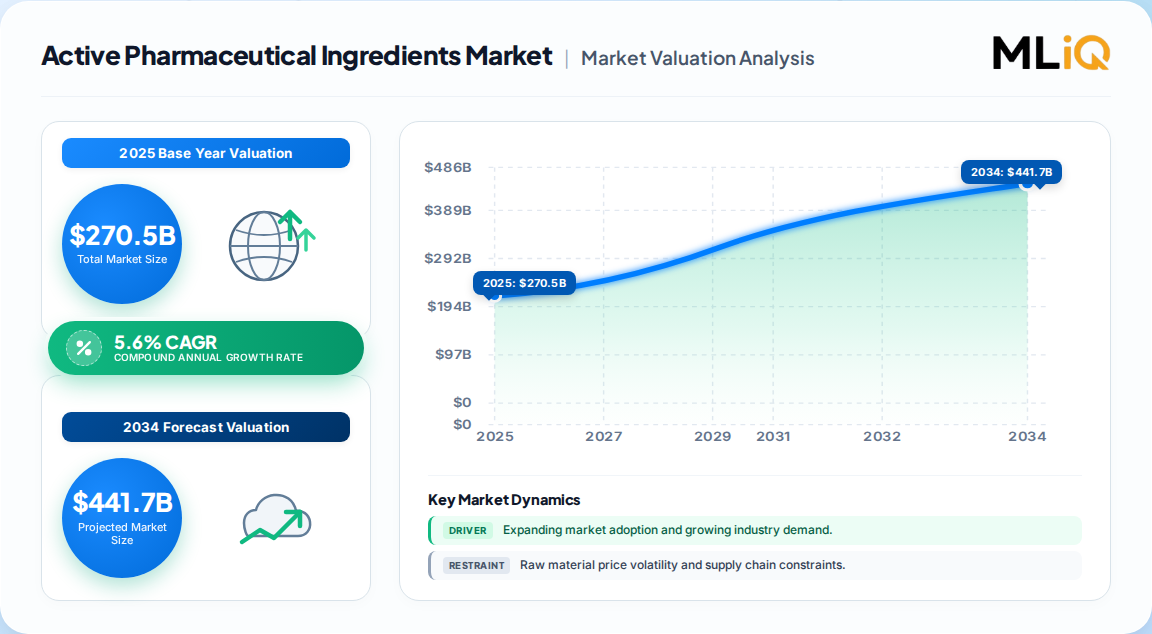
270.5 Billion represents the global Active Pharmaceutical Ingredients Market value in 2025, setting the baseline for all forward projections.
The market is forecast to reach 419.0 Billion by 2033, expanding at a 5.6% CAGR across the 2026–2033 horizon.
Synthetic APIs dominate with roughly 71% of 2025 revenue, but biologic APIs are growing fastest at nearly 9% annually.
North America leads with a 37.7% revenue share, while Asia-Pacific is the fastest-growing region at approximately 10% CAGR.
Captive manufacturers hold 50.6% of the market, yet merchant/outsourced production is accelerating as pharma firms diversify supply chains.
Pfizer, Teva, Dr. Reddy's, Sun Pharma, Lonza, Cipla, and Aurobindo anchor a moderately concentrated competitive landscape.
Why this matters for decision-makers: Biologic and high-potency API capacity, not commodity small-molecule volume, will determine margin leadership through 2033. Firms that delay specialized capacity investment risk structural cost disadvantage.
Active Pharmaceutical Ingredients Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
270.5 B
2025
287.1 B
2026
303.2 B
2027
320.2 B
2028
338.1 B
2029
357.1 B
2030
377.2 B
2031
Active Pharmaceutical Ingredients Market Size (In Billion)
Year
Market Size
2025
270.5 B
2026
287.1 B
2027
303.2 B
2028
320.2 B
2029
338.1 B
2030
357.1 B
2031
377.2 B
What is the Active Pharmaceutical Ingredients Market?
The Active Pharmaceutical Ingredients Market encompasses the biologically active components—synthetic chemical entities, biotechnology-derived proteins, and complex biologics—that produce therapeutic effects in finished drug products. It spans captive in-house synthesis, merchant API sales, and contract development and manufacturing (CDMO/CMO) services across branded, generic, and biosimilar pharmaceuticals.
Scope: what this report covers and excludes
This analysis covers global API production and trade across synthetic, biological, and highly potent categories, segmented by manufacturer model, molecule size, therapeutic area, and drug type. It addresses captive and merchant manufacturing, contract outsourcing, and regulatory frameworks across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover finished pharmaceutical formulation, drug delivery devices, excipients, or clinical research services.
How big is the market for Active Pharmaceutical Ingredients Market?
Published estimates disagree materially on both base value and growth rate, reflecting differing scope definitions rather than genuine market divergence. The table below reconciles the leading benchmarks.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
228.5 Billion
2022
2032
6.5%
Broad API incl. biologics, HPAPI, both captive and merchant
One published estimate
256.4 Billion
2025
2034
4.22%
Global API incl. innovative and generic, captive and merchant
A competing analysis
270.5 Billion
2025
2033
5.6%
API by synthesis, manufacturer, type, application, drug type
A third published estimate
245.7 Billion (2026)
2026
2032
6.95%
API by type, manufacturer, molecule size, therapy
A separate industry analysis
The 270.5 Billion / 5.6% benchmark is the most defensible. It sits between the conservative 4.22% and aggressive 6.95% views, and its scope explicitly reconciles captive vs. merchant manufacturing—a distinction the higher-CAGR estimates blur. Our analysis suggests the 6.95% figure likely overstates growth by conflating merchant API expansion with total market value.
How is the market segmented?
Segmentation reveals where value concentrates and which sub-segments carry premium pricing. The following parents exclude geography.
Synthetic APIs held approximately 70.9% of 2025 revenue, but biological APIs are forecast to grow at 8.92% CAGR—the widest growth gap in the segmentation. This divergence implies that volume leadership and value leadership are decoupling: commodity small-molecule producers face price pressure while biologic and HPAPI specialists command premium margins.
Which region leads in Active Pharmaceutical Ingredients Market?
North America leads with 37.7% of 2025 revenue, but Asia-Pacific is the fastest-growing region at roughly 10% CAGR. The geography tree below shows the nested structure used throughout this analysis.
Active Pharmaceutical Ingredients Market Regional Market Share
Loading chart...
Active Pharmaceutical Ingredients Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.24%
Asia-Pacific
0.22%
Latin America
0.09%
Middle East & Africa
0.07%
Parent Region
Children
North America
United States, Canada, Mexico
Europe
Germany, UK, France, Italy, Switzerland
Asia-Pacific
China, India, Japan, South Korea, Singapore
Latin America
Brazil, Argentina, Mexico
Middle East & Africa
Saudi Arabia, UAE, South Africa
The United States alone accounts for approximately 90.8% of North American API value, underscoring the concentration risk and opportunity in a single regulatory jurisdiction. Our analysis suggests Asia-Pacific's growth premium is structural: India's CDMO sector growing at 7% annually and China's fermentation capacity expansion are not cyclical tailwinds but durable supply-chain rebalancing.
What is driving growth — and what is holding it back?
Chronic disease prevalence and biosimilar patent cliffs are the dominant demand engines, while pricing controls and GMP compliance costs constrain margin expansion.
Factor
Direction
Evidence Strength
Mechanism
Rising chronic disease burden
Driver
High
Diabetes projected at 783M cases by 2045; CVD causes 17.9M deaths annually
Biosimilar and generic demand
Driver
High
USD 200+ Billion in biologic revenues facing patent expiry
CMO/CDMO expansion
Driver
Medium-High
India CDMO growing 7% annually; outsourcing cost advantages
Biopharma R&D surge
Driver
High
8,000+ drugs in clinical development globally
Unfavorable pricing policies
Restraint
Medium
Price controls compress top and bottom-line growth
GMP and nitrosamine compliance
Restraint
High
EU controls link API specs to finished medicine requirements
High manufacturing costs
Restraint
Medium
Specialized containment and sterile capacity require heavy capex
The balance of evidence favors demand-side drivers through 2030. However, the compliance burden is not merely a cost—it is a moat. EU nitrosamine controls and GMP equivalence requirements effectively raise barriers to entry for low-cost producers, protecting incumbent margins in regulated markets. The restraint and the driver are, in this sense, the same force.
Who are the leading vendors?
The market is moderately concentrated, with integrated pharma majors and specialized API manufacturers competing on chemistry capability, regulatory breadth, and capacity scale.
Company
Primary Strength
Strategic Focus
Pfizer CentreOne
Integrated pharma + CDMO
Sterile and complex API
Teva Pharmaceutical Industries
Generic API scale
Cost leadership
Dr. Reddy's Laboratories
Synthetic and oncology API
Vertical integration
Sun Pharmaceutical Industries
Broad portfolio
Emerging market reach
Lonza
Biologics and HPAPI
Specialized manufacturing
Cipla
Generic API
Volume and access
Aurobindo Pharma
Generic API scale
Cost and capacity
EUROAPI
European API
Regional supply security
Differentiation hinges on two moats: specialized containment capability (HPAPI, ADC payloads) and regulatory approval breadth across jurisdictions. Commodity synthetic API producers compete almost exclusively on cost, making them vulnerable to Asian price competition. Our analysis suggests EUROAPI's standalone European positioning is a deliberate regulatory-arbitrage play—capturing premium pricing from buyers diversifying away from single-region supply concentration.
What do buyers and operators need to know? (Decision Support)
Procurement strategy in this market is no longer a pure cost exercise. The EU's Falsified Medicines Directive requires written GMP-equivalence confirmation from exporting-country authorities for non-listed third countries—a requirement waived only for countries on the Commission's equivalence list, which now includes the US, Japan, Switzerland, South Korea, Brazil, Israel, Australia, Canada, Taiwan, and Singapore as of 2026. Buyers sourcing from non-listed jurisdictions face months-long documentation risk.
Switching costs are asymmetric. Qualifying a new API supplier requires Drug Master File resubmission, batch validation, and often re-filing with regulators—a 12-to-24-month process. This locks buyers into incumbent relationships but also locks producers into compliance investments that smaller competitors cannot replicate.
The critical procurement risk is single-region concentration. COVID-19 exposed the fragility of China-centric supply, and buyers now routinely dual-source across India and Europe. Operators should prioritize suppliers with audit-ready GMP documentation, demonstrated nitrosamine control, and sterile or HPAPI containment capability. Small-batch specialty API demand from precision medicine is rising, and suppliers without flexible capacity will lose share to CDMOs.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a structural upgrade thesis over a volume-growth thesis. Total market CAGR of 5.6% understates the real story: within that average, biologic APIs are growing at nearly 9% and oncology APIs at over 10%, while commodity synthetic APIs face price deflation. The spread between these growth rates is the single most important number for capital allocation.
The strongest counter-argument is that biosimilar pricing pressure will compress API margins for biologic producers just as generic competition did for synthetic producers. This is credible—but it misunderstands timing. The USD 200+ Billion biosimilar cliff is a 2027–2032 event, and the producers building capacity now will capture the first wave of premium-priced biosimilar API contracts before commoditization sets in.
Actionable Strategy:
Operators should prioritize HPAPI and sterile biologic capacity investment, where regulatory barriers protect margins and demand growth exceeds 8% annually.
Procurement teams should build dual-region supplier relationships, prioritizing EU-listed equivalence countries to reduce documentation and compliance risk.
Investors should look past headline CAGR and target CDMO platforms in India and Europe, where merchant outsourcing is growing at roughly 9.5%—nearly double the total market rate.
The evidence that would change our conclusion: a sustained acceleration in generic API price recovery in emerging markets, or a regulatory shift that lowers GMP-equivalence barriers for non-listed countries. Neither is visible in current policy trends.
Active Pharmaceutical Ingredients Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Active Pharmaceutical Ingredients Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.6% from 2020-2034
Segmentation
By Type of Synthesis
Synthetic
Biotech/Biological
Highly Potent (HPAPI)
By Type of Manufacturer
Captive/In-House
Merchant/Outsourced
By API Type
Innovative
Generic
By Molecule Size
Small Molecule
Large Molecule/Biologic
By Therapeutic Application
Oncology
Cardiology
Anti-diabetics
CNS & Anesthesia
Infectious Disease
Biologics
Others
By Type of Drug
Prescription
OTC
By Geography
North America
United States
Canada
Mexico
Europe
Germany
UK
France
Italy
Switzerland
Asia-Pacific
China
India
Japan
South Korea
Singapore
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Active Pharmaceutical Ingredients Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Active Pharmaceutical Ingredients Market Executive Summary
2.1. Market Snapshot
3. Active Pharmaceutical Ingredients Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Active Pharmaceutical Ingredients Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Active Pharmaceutical Ingredients Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type of Synthesis
5.1.1. Synthetic
5.1.2. Biotech/Biological
5.1.3. Highly Potent (HPAPI)
5.2. Analysis, Insights and Forecast - by Type of Manufacturer
5.2.1. Captive/In-House
5.2.2. Merchant/Outsourced
5.3. Analysis, Insights and Forecast - by API Type
5.3.1. Innovative
5.3.2. Generic
5.4. Analysis, Insights and Forecast - by Molecule Size
5.4.1. Small Molecule
5.4.2. Large Molecule/Biologic
5.5. Analysis, Insights and Forecast - by Therapeutic Application
5.5.1. Oncology
5.5.2. Cardiology
5.5.3. Anti-diabetics
5.5.4. CNS & Anesthesia
5.5.5. Infectious Disease
5.5.6. Biologics
5.5.7. Others
5.6. Analysis, Insights and Forecast - by Type of Drug
5.6.1. Prescription
5.6.2. OTC
5.7. Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia-Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. Active Pharmaceutical Ingredients Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type of Synthesis
6.1.1. Synthetic
6.1.2. Biotech/Biological
6.1.3. Highly Potent (HPAPI)
6.2. Analysis, Insights and Forecast - by Type of Manufacturer
6.2.1. Captive/In-House
6.2.2. Merchant/Outsourced
6.3. Analysis, Insights and Forecast - by API Type
6.3.1. Innovative
6.3.2. Generic
6.4. Analysis, Insights and Forecast - by Molecule Size
6.4.1. Small Molecule
6.4.2. Large Molecule/Biologic
6.5. Analysis, Insights and Forecast - by Therapeutic Application
6.5.1. Oncology
6.5.2. Cardiology
6.5.3. Anti-diabetics
6.5.4. CNS & Anesthesia
6.5.5. Infectious Disease
6.5.6. Biologics
6.5.7. Others
6.6. Analysis, Insights and Forecast - by Type of Drug
6.6.1. Prescription
6.6.2. OTC
7. Active Pharmaceutical Ingredients Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type of Synthesis
7.1.1. Synthetic
7.1.2. Biotech/Biological
7.1.3. Highly Potent (HPAPI)
7.2. Analysis, Insights and Forecast - by Type of Manufacturer
7.2.1. Captive/In-House
7.2.2. Merchant/Outsourced
7.3. Analysis, Insights and Forecast - by API Type
7.3.1. Innovative
7.3.2. Generic
7.4. Analysis, Insights and Forecast - by Molecule Size
7.4.1. Small Molecule
7.4.2. Large Molecule/Biologic
7.5. Analysis, Insights and Forecast - by Therapeutic Application
7.5.1. Oncology
7.5.2. Cardiology
7.5.3. Anti-diabetics
7.5.4. CNS & Anesthesia
7.5.5. Infectious Disease
7.5.6. Biologics
7.5.7. Others
7.6. Analysis, Insights and Forecast - by Type of Drug
7.6.1. Prescription
7.6.2. OTC
8. Active Pharmaceutical Ingredients Market Asia-Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type of Synthesis
8.1.1. Synthetic
8.1.2. Biotech/Biological
8.1.3. Highly Potent (HPAPI)
8.2. Analysis, Insights and Forecast - by Type of Manufacturer
8.2.1. Captive/In-House
8.2.2. Merchant/Outsourced
8.3. Analysis, Insights and Forecast - by API Type
8.3.1. Innovative
8.3.2. Generic
8.4. Analysis, Insights and Forecast - by Molecule Size
8.4.1. Small Molecule
8.4.2. Large Molecule/Biologic
8.5. Analysis, Insights and Forecast - by Therapeutic Application
8.5.1. Oncology
8.5.2. Cardiology
8.5.3. Anti-diabetics
8.5.4. CNS & Anesthesia
8.5.5. Infectious Disease
8.5.6. Biologics
8.5.7. Others
8.6. Analysis, Insights and Forecast - by Type of Drug
8.6.1. Prescription
8.6.2. OTC
9. Active Pharmaceutical Ingredients Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type of Synthesis
9.1.1. Synthetic
9.1.2. Biotech/Biological
9.1.3. Highly Potent (HPAPI)
9.2. Analysis, Insights and Forecast - by Type of Manufacturer
9.2.1. Captive/In-House
9.2.2. Merchant/Outsourced
9.3. Analysis, Insights and Forecast - by API Type
9.3.1. Innovative
9.3.2. Generic
9.4. Analysis, Insights and Forecast - by Molecule Size
9.4.1. Small Molecule
9.4.2. Large Molecule/Biologic
9.5. Analysis, Insights and Forecast - by Therapeutic Application
9.5.1. Oncology
9.5.2. Cardiology
9.5.3. Anti-diabetics
9.5.4. CNS & Anesthesia
9.5.5. Infectious Disease
9.5.6. Biologics
9.5.7. Others
9.6. Analysis, Insights and Forecast - by Type of Drug
9.6.1. Prescription
9.6.2. OTC
10. Active Pharmaceutical Ingredients Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type of Synthesis
10.1.1. Synthetic
10.1.2. Biotech/Biological
10.1.3. Highly Potent (HPAPI)
10.2. Analysis, Insights and Forecast - by Type of Manufacturer
10.2.1. Captive/In-House
10.2.2. Merchant/Outsourced
10.3. Analysis, Insights and Forecast - by API Type
10.3.1. Innovative
10.3.2. Generic
10.4. Analysis, Insights and Forecast - by Molecule Size
10.4.1. Small Molecule
10.4.2. Large Molecule/Biologic
10.5. Analysis, Insights and Forecast - by Therapeutic Application
10.5.1. Oncology
10.5.2. Cardiology
10.5.3. Anti-diabetics
10.5.4. CNS & Anesthesia
10.5.5. Infectious Disease
10.5.6. Biologics
10.5.7. Others
10.6. Analysis, Insights and Forecast - by Type of Drug
10.6.1. Prescription
10.6.2. OTC
11. Active Pharmaceutical Ingredients Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Active Pharmaceutical Ingredients Market Research Methodology
List of Figures
Figure 1: Active Pharmaceutical Ingredients Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Active Pharmaceutical Ingredients Market Revenue (Billion), by Type of Synthesis 2026 & 2034
Figure 3: North America Active Pharmaceutical Ingredients Market Revenue Share (%), by Type of Synthesis 2026 & 2034
Figure 4: North America Active Pharmaceutical Ingredients Market Revenue (Billion), by Type of Manufacturer 2026 & 2034
Figure 5: North America Active Pharmaceutical Ingredients Market Revenue Share (%), by Type of Manufacturer 2026 & 2034
Figure 6: North America Active Pharmaceutical Ingredients Market Revenue (Billion), by API Type 2026 & 2034
Figure 7: North America Active Pharmaceutical Ingredients Market Revenue Share (%), by API Type 2026 & 2034
Figure 8: North America Active Pharmaceutical Ingredients Market Revenue (Billion), by Molecule Size 2026 & 2034
Figure 9: North America Active Pharmaceutical Ingredients Market Revenue Share (%), by Molecule Size 2026 & 2034
Figure 10: North America Active Pharmaceutical Ingredients Market Revenue (Billion), by Therapeutic Application 2026 & 2034
Figure 11: North America Active Pharmaceutical Ingredients Market Revenue Share (%), by Therapeutic Application 2026 & 2034
Figure 12: North America Active Pharmaceutical Ingredients Market Revenue (Billion), by Type of Drug 2026 & 2034
Figure 13: North America Active Pharmaceutical Ingredients Market Revenue Share (%), by Type of Drug 2026 & 2034
Figure 14: North America Active Pharmaceutical Ingredients Market Revenue (Billion), by Country 2026 & 2034
North America Active Pharmaceutical Ingredients Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Type of Synthesis 2020 & 2034
Table 2: Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Type of Manufacturer 2020 & 2034
Table 3: Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by API Type 2020 & 2034
Table 4: Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Molecule Size 2020 & 2034
Table 5: Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Therapeutic Application 2020 & 2034
Table 6: Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Type of Drug 2020 & 2034
Table 7: Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Type of Synthesis 2020 & 2034
Table 9: North America Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Type of Manufacturer 2020 & 2034
Table 10: North America Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by API Type 2020 & 2034
Table 11: North America Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Molecule Size 2020 & 2034
Table 12: North America Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Therapeutic Application 2020 & 2034
Table 13: North America Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Type of Drug 2020 & 2034
Table 14: North America Active Pharmaceutical Ingredients Market Revenue Billion Forecast, by Country 2020 & 2034
United States Active Pharmaceutical Ingredients Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current size of the Active Pharmaceutical Ingredients Market?
The global API market was valued at approximately 270.5 Billion in 2025 and is projected to reach 419.0 Billion by 2033, growing at a 5.6% CAGR. Chronic disease prevalence and biosimilar demand are the primary growth engines.
2. Which region dominates API production?
North America leads with 37.7% of global revenue in 2025, supported by advanced infrastructure and FDA frameworks. Asia-Pacific is the fastest-growing region at roughly 10% CAGR, driven by India and China.
3. What are the main types of APIs?
APIs segment into synthetic chemical, biological/biotech, and highly potent (HPAPI) categories. Synthetic APIs held about 71% of 2025 revenue, while biological APIs are growing fastest at nearly 9% CAGR.
4. Why is the biosimilar pipeline important for API demand?
Patent expirations on biologics worth over USD 200 Billion in annual revenue are creating large-scale biosimilar API opportunities. The FDA's 2024 SIMLANDI approval exemplifies this wave, driving biologic API capacity demand.
5. How do regulatory requirements affect API sourcing?
The EU Falsified Medicines Directive requires GMP-equivalence confirmation from exporting-country authorities unless the country is on the approved equivalence list. This adds documentation risk and reinforces supplier concentration.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary split, ensuring that market sizing is grounded in verifiable operational data rather than desk estimates alone. We conducted in-depth interviews with stakeholders across the API value chain: raw material and precursor suppliers, specialized API producers (synthetic, biologic, and HPAPI), contract development and manufacturing organizations (CDMOs), and global distributors. Interviews targeted decision-makers including Vice Presidents of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, capturing both demand-side procurement criteria and supply-side capacity constraints.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement & Sourcing Leads
35%
R&D & Technical Directors
30%
Regulatory & Quality Heads
22%
Commercial Operations Leads
13%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
API Producers & Synthesis Labs
40%
CDMOs & Contract Manufacturers
30%
Raw Material & Precursor Suppliers
18%
Global Distributors & Traders
12%
Secondary Benchmarking & Public Trade Validation
Secondary research draws on official multilateral databases—UN Comtrade, WTO trade statistics, US ITC, and Eurostat—to validate cross-border API flows and regional consumption patterns. Corporate filings (10-K, SEC submissions, annual investor presentations) provide capacity and revenue benchmarks for leading producers. Patent databases inform pipeline-driven demand modeling, while recognized technical standards from industry associations and regulatory bodies (EMA, FDA, ICH) anchor compliance-cost assumptions.
Demand Modeling & Market Sizing Triangulation
We triangulate market size through simultaneous Top-Down and Bottom-Up models. The Top-Down approach allocates macroeconomic pharmaceutical expenditure across API segments using therapeutic-area shares. The Bottom-Up approach models manufacturer capacity, product pricing, and end-use consumption by region, reconciling captive and merchant production separately to avoid double-counting.


 Active Pharmaceutical Ingredients Market