 Alcohol Dehydrogenase Market by Type
: 2026 Global Outlook
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Alcohol Dehydrogenase Market by Type

Amit Mardhekar
Research Analyst

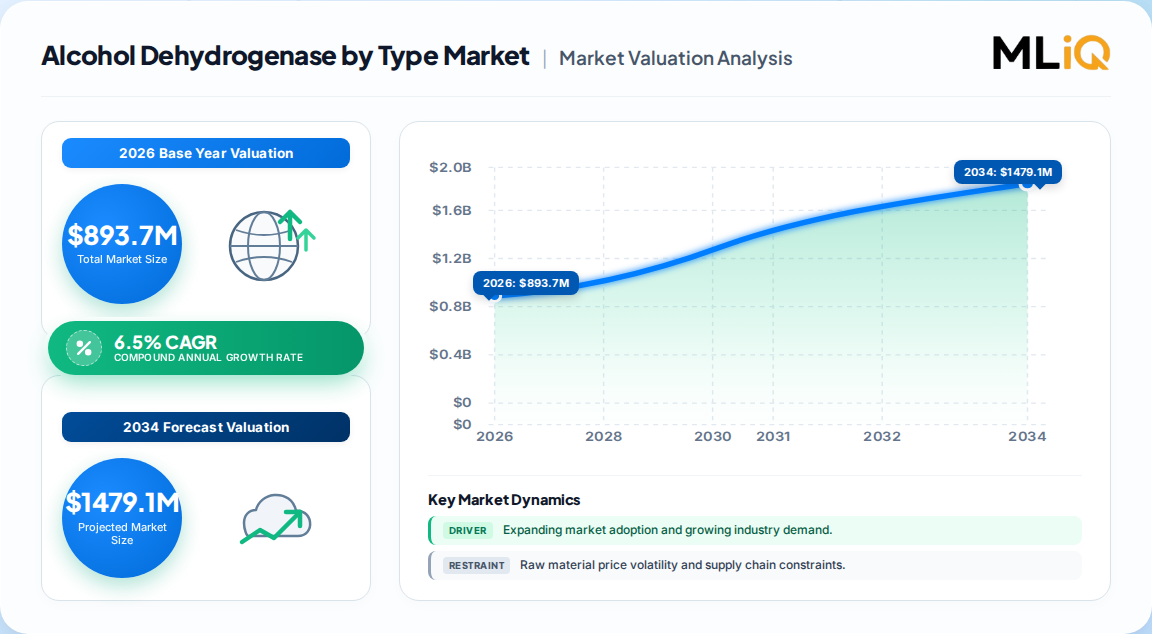
| Year | Market Size |
|---|---|
| 2025 | 839.0 M |
| 2026 | 894.0 M |
| 2027 | 952.0 M |
| 2028 | 1.010 B |
| 2029 | 1.080 B |
| 2030 | 1.150 B |
| 2031 | 1.220 B |

The alcohol dehydrogenase market by type segments commercial oxidoreductase enzymes by catalytic activity grade — principally 5 KU, 15 KU, 30 KU, 75 KU and 150 KU — where one KU liberates one micromole of NADH per minute under standard assay conditions. Grade selection determines assay linearity, reagent consumption and cost per test.
This report covers commercial alcohol dehydrogenase enzyme formats sold by activity grade (5–150 KU and above), across microbial, plant and animal sources, in liquid, powder and gel forms, for diagnostic, analytical, biocatalytic and research applications. Geography spans North America, Europe, Asia-Pacific, Latin America and Middle East & Africa. This analysis does not cover wholesale industrial ethanol fermentation volumes, chromatographic or mass-spectrometric detection methods without enzymatic reagents, or endogenous liver-function testing that does not consume exogenous ADH reagent.
Published estimates diverge by an order of magnitude, largely because some analysts count only diagnostic-grade reagent enzymes while others include biocatalysis and bulk industrial concentrates. The table below normalizes the competing figures against their definitions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 893.7 Million | 2026 | 2036 (1,679.0 Mn) | 6.5% | Commercial ADH enzymes, all activity grades, global | One published estimate (2026) |
| 709.1 Million | 2024 | 2034 (1,246.1 Mn) | 5.8% | ADH enzymes by product type, source, form, application | A competing analysis |
| 175.66 Million | 2025 | 2032 (264.13 Mn) | 6.0% | Narrower enzyme-only scope, pharma/food/cosmetics/biotech | A competing analysis |
| 1.76 Billion | 2024 | 2035 (3.05 Bn) | 5.16% | Broadest scope including industrial biocatalysis adjacencies | A competing analysis |
Our analysis favors the 2026 base of approximately 890 Million as the most defensible midpoint: it reconciles the diagnostic-reagent core with the growing biocatalysis segment without absorbing unrelated industrial ethanol volumes. The 175 Million figure almost certainly captures only catalog-scale research reagent sales, while the 1.76 Billion figure appears to fold in fermentation-adjacent biocatalyst demand that dilutes grade-level comparability.
Segmentation by activity grade is the defining structural axis, because grade determines both price per unit and the instrument class a buyer can deploy it on. Source and form segmentations then govern supply security and shelf-life economics.
| Parent segment | Children |
|---|---|
| By Type (Activity Grade) | 5 KU, 15 KU, 30 KU, 75 KU, 150 KU, 300 KU+ |
| By Source | Microbial, Plant, Animal |
| By Form | Liquid, Powder, Gel |
| By Application | Disease Diagnosis, Alcohol Concentration Detection, Biocatalysis/Catalyst, Research, Others |
| By End Use | Clinical, Industrial, Research |
Grade proliferation is itself a signal: suppliers are pushing buyers toward higher-activity formats (75 KU and 150 KU) because concentration reduces shipping and cold-chain cost per test. Our analysis suggests mid-tier 30 KU grades will lose relative share after 2028 as automated analyzers demand tighter kinetic windows.
North America leads the global alcohol dehydrogenase market by type with roughly 38.5% of value, but Asia-Pacific is closing the gap fastest as Chinese and Indian toxicology screening volumes scale.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.26% |
| Asia-Pacific | 0.24% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
The regional hierarchy is driven less by population than by enforcement infrastructure. North America's position rests on mature impaired-driving calibration regimes and CLIA-moderate-complexity assay adoption, while China's 8.3% projected CAGR reflects rapid expansion of public-safety testing capacity rather than replacement demand.
Growth is driven primarily by mandated toxicological screening and clinical automation, while high production costs and enzyme thermal instability cap how fast capacity can profitably scale.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Stricter blood-alcohol enforcement | Driver | High | Replaces colorimetric screens with enzymatic quantification |
| Clinical automation expansion | Driver | High | Standardized 150 KU liquid formats on automated analyzers |
| Enzyme engineering (recombinant expression) | Driver | Medium-High | Improves yield, thermal stability and lot consistency |
| Biocatalysis for chiral synthesis | Driver | Medium | NAD/NADH recycling systems raise adoption in pharma |
| High small-scale production cost (>EUR 10,000/kg) | Restraint | High | Limits entry and caps margin at low volumes |
| Thermal instability above 45°C | Restraint | High | Constrains reactor design and cold-chain spend |
| Sourcing complexity for animal-derived ADH | Restraint | Medium | Ethical and traceability constraints shift demand to microbial |
Our analysis suggests the restraint side is structurally weaker than it appears: large-scale fermentation already reduces unit cost toward EUR 250/kg, so the cost barrier is a scale barrier, not a technology barrier. The binding constraint over 2026–2036 is validated lot reproducibility, not raw enzyme availability.
Novonesis Group, Amano Enzyme, Thermo Fisher Scientific and Sigma-Aldrich anchor the supply side, with Roche and Merck KGaA strong in clinical reagent integration.
| Company | Primary positioning | Structural advantage |
|---|---|---|
| Novonesis Group | Industrial enzyme scale | Fermentation capacity and global distribution |
| Amano Enzyme | Specialty enzyme grades | Application depth in diagnostic and food enzymes |
| Thermo Fisher Scientific | Research and clinical reagents | Instrument-reagent bundle and catalog breadth |
| Sigma-Aldrich (Merck) | Catalog reagent supply | Brand trust and lot documentation |
| Roche | Clinical diagnostics integration | Analyzer-embedded assay ecosystems |
| Merck KGaA | Life science and diagnostics | Regulatory dossier depth |
Differentiation is migrating from activity per vial toward documentation per lot. Vendors that bundle stabilizers, application notes and CLIA-support packages are converting commodity reagent sales into recurring assay contracts — a shift our analysis reads as the single most important competitive re-rating in this sector.
Grade selection is a procurement decision as much as a technical one. Buyers specifying 150 KU liquid formats gain kinetic predictability in 10-minute photometric windows but accept cold-chain dependence and shorter shelf life. Powder formats trade convenience for reconstitution variability that can introduce assay drift if buffer protocols are not locked.
Switching costs are materially underestimated. Revalidating a grade change typically requires recalibration across every affected analyzer, proficiency-test resubmission and, in regulated labs, documentation of comparability. Our analysis suggests a qualified second source is worth a 5–10% price premium because single-source failure carries regulatory and turnaround risk far exceeding the reagent delta.
Regulatory exposure varies sharply by end use. Clinical customers face proficiency and complexity categorization requirements; food and beverage users need GRAS-aligned inputs; cosmetic formulators require safety dossiers. Vendors that pre-package these documents shorten buyer qualification cycles and, in practice, win tenders before price is discussed.
The balance of evidence favors a moderately consolidated, compliance-driven market growing in the mid-single digits through 2036, with value migrating toward high-activity grades and validated supply relationships. The 6.5% forecast sits above the 5.8% and 5.16% competing estimates precisely because it weights enforcement-driven clinical demand more heavily — a defensible methodological choice given that laboratory consolidation is compressing the vendor pool at the same time.
The strongest counter-argument is that biocatalysis adoption in pharmaceutical chiral synthesis could accelerate faster than enforcement-driven diagnostics, pushing growth toward the upper bound of 7%+ and shifting the grade mix toward custom formulations. That outcome would reward flexible fermentation capacity over catalog breadth, an inversion of current competitive logic.
What would change our conclusion: sustained evidence that biocatalytic ADH demand in pharmaceutical manufacturing exceeds 25% of total volume would require re-basing the forecast upward and reinterpreting grade mix entirely — a level of segment-level granularity that only the full report resolves.
See the research methodology appendix below for interview composition, triangulation approach and the full validation matrix.
Our research operates on a structured 70/30 primary-to-secondary split. Fieldwork comprised depth interviews across raw material and fermentation suppliers, specialized enzyme producers, contract assay formulators, diagnostic reagent integrators and global distributors. Interviewees included VP-level sourcing leads, heads of R&D, technical directors and commercial operations managers, each screened for direct procurement or specification authority.
We validated demand estimates against UN Comtrade and WTO trade flows, US ITC and Eurostat customs data, corporate 10-K and annual investor filings, patent landscapes, and non-profit technical standards from ISO and pharmacopeial bodies. No third-party market-research publisher data was used as a primary source.
Top-down allocation from macroeconomic and clinical testing budgets was run simultaneously against bottom-up modeling of manufacturer capacity, product pricing and end-use consumption, with divergences reconciled at the grade level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.5% from 2020-2034 |
| Segmentation |
|
It is the commercial segment of ADH enzymes classified by catalytic activity grade — 5 KU, 15 KU, 30 KU, 75 KU and 150 KU — where one KU converts one micromole of substrate per minute. Grade determines assay linearity, reagent cost per test and instrument compatibility.
The 150 KU grade dominates, capturing roughly 33.7% of global volume in 2026. Clinical chemistry automation favors high-activity formats because they deliver predictable kinetics inside strict photometric windows and reduce reagent consumption per test.
The market is projected to grow at approximately 6.5% CAGR from 2026 to 2036, reaching about 1,679 Million USD. Growth is anchored by mandated toxicological screening and expanding clinical laboratory automation, particularly in Asia-Pacific.
North America leads with approximately 38.5% of global value, supported by mature impaired-driving enforcement and CLIA-categorized clinical testing. Asia-Pacific is the fastest-growing region, with China tracking an 8.3% CAGR.
Leading suppliers include Novonesis Group, Amano Enzyme, Thermo Fisher Scientific, Sigma-Aldrich, Roche and Merck KGaA. Competition increasingly hinges on lot-to-lot reproducibility and regulatory documentation rather than price per unit alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research is built on a 70/30 primary-to-secondary split. Fieldwork comprised structured depth interviews across five value-chain tiers: fermentation and raw material suppliers, specialized enzyme producers, contract assay formulators, diagnostic reagent integrators and global distributors. Within each tier we screened for specification authority, interviewing VP-level sourcing leads, heads of R&D, technical directors and commercial operations managers whose decisions directly determine grade selection and supplier qualification.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Directors | 35% |
| Heads of R&D & Technical Directors | 35% |
| Regulatory & Quality Leads | 15% |
| Commercial Operations Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Fermentation & Raw Material Suppliers | 30% |
| Specialized Enzyme Producers | 30% |
| Contract Formulators & Reagent Integrators | 25% |
| Global Distributors & Traders | 15% |
Estimates were cross-checked against UN Comtrade and WTO trade flows, US ITC and Eurostat customs records, corporate 10-K and annual investor filings, patent landscapes, and non-profit technical standards from ISO and pharmacopeial bodies. No third-party market-research publisher data was treated as a primary source; where published estimates were referenced, they were normalized against defined scope boundaries.
Top-down allocation from macroeconomic and clinical testing budgets ran simultaneously with bottom-up modeling of manufacturer capacity, product pricing and end-use consumption. Divergences were reconciled at activity-grade level, with unresolved gaps flagged rather than smoothed.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |