Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Arthroscopic Implants Market by Product (Suture Anchors, Interference Screws, Suture Buttons, Graft Support Devices, Meniscal Repair Devices), by Material (Bioabsorbable, Non-absorbable, Hybrid), by Application (Knee, Shoulder, Hip, Ankle, Elbow, Wrist), by End User (Hospitals, Ambulatory Surgical Centers, Outpatient Orthopedic Clinics), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
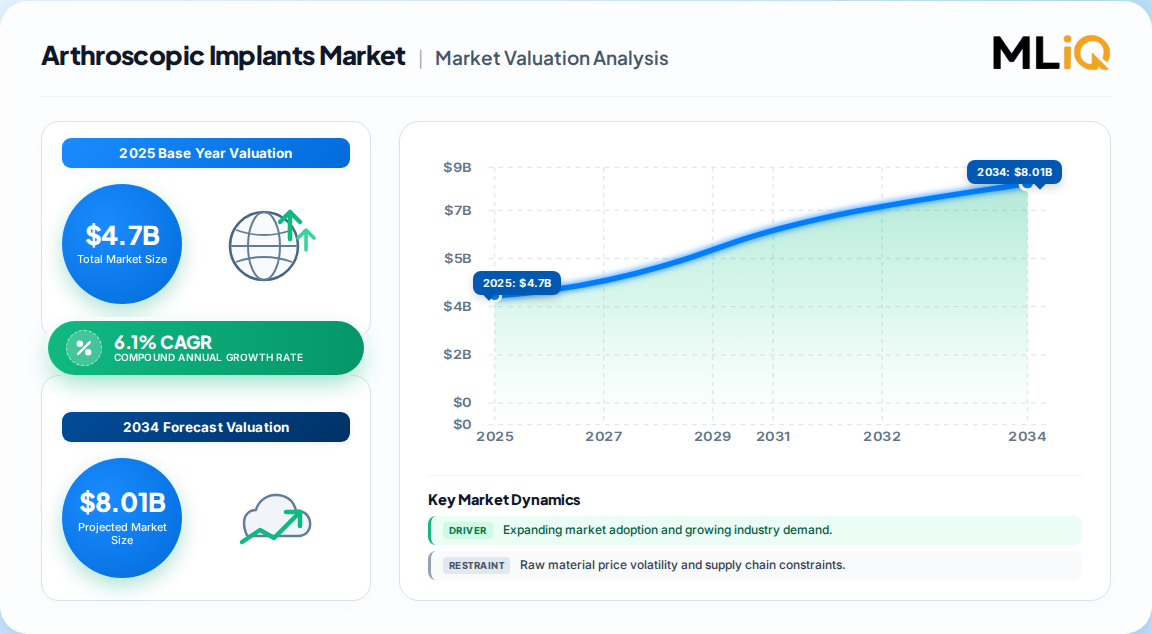
USD 4.7 billion in 2025 — the global arthroscopic implants market, defined as fixation anchors, interference screws, suture-passing and graft-support devices, and bioabsorbable implants used in arthroscopic joint repair.
Forecast USD 7.1 billion by 2033, implying a 6.1% CAGR — materially faster than the ~4% growth of the broader arthroscopy devices and visualization hardware categories.
Knee leads application demand at roughly 40–45% of implant revenue, followed by shoulder, with hip and small-joint (ankle, wrist, elbow) the fastest-growing pockets.
North America holds the largest regional share (~41%), while Asia Pacific is the fastest-growing region on procedural volume and local manufacturing build-out.
Implants are the single largest product category within arthroscopic devices, consistently cited at 45–49% of total device revenue across published estimates.
Bioabsorbable and knotless fixation platforms are shifting competitive advantage toward material science and biocompatibility rather than pure mechanical design.
Why this matters for decision-makers: implant growth is outpacing the hardware categories that surround it, so vendors that anchor pricing and loyalty in implant portfolios — not capital equipment — will capture disproportionate margin as procedures migrate to ambulatory surgery centers.
Arthroscopic Implants Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.400 B
2024
4.700 B
2025
5.000 B
2026
5.300 B
2027
5.600 B
2028
5.900 B
2029
6.300 B
2030
Arthroscopic Implants Market Size (In Billion)
Year
Market Size
2024
4.400 B
2025
4.700 B
2026
5.000 B
2027
5.300 B
2028
5.600 B
2029
5.900 B
2030
6.300 B
What is the Arthroscopic Implants Market?
Arthroscopic implants are fixation and reconstruction devices — suture anchors, interference screws, buttons, and bioabsorbable scaffolds — placed through small portals during minimally invasive joint surgery to stabilize soft tissue, reattach tendon to bone, or fixate grafts. The market covers their design, manufacture, and sale to hospitals and ambulatory surgery centers.
Scope: what this report covers and excludes
This analysis covers implantable fixation and reconstruction devices used in arthroscopic knee, shoulder, hip, ankle, elbow, and wrist procedures, segmented by product type, material, application, and end user. It is global in scope, spanning North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Explicitly excluded are arthroscopes and visualization towers, fluid management and ablation systems, powered shaver handpieces, capital equipment, surgical consumables such as suture and disposable instruments, orthopedic joint replacement prosthetics, and biologics (PRP, stem cell therapies).
This analysis does not cover adjacent markets such as orthopedic robotics as a standalone category, arthroscopy capital equipment, or non-implantable sports medicine consumables.
How big is the market for Arthroscopic Implants Market?
Published estimates diverge mainly because some analysts size arthroscopic implants as a standalone category while others report them embedded within a broader arthroscopy or arthroscopic devices total. The table below reconciles the credible reference points.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
USD 8.6 Billion
2026
2033
4.9%
Total arthroscopic devices, including implants, arthroscopes, RF and shaver systems
One published devices-market analysis
USD 6.8 Billion
2026
2033
3.4%
Arthroscopy market, all product categories and applications
A competing analysis
USD 6.23 Billion
2023
2032
3.76%
Arthroscopy market, product and application split
A competing analysis
Our analysis treats these as parent-market estimates. Applying the consistently cited 45–49% implant share of arthroscopic device revenue to the 2026 device base yields an implant-specific base of roughly USD 4.7 billion in 2025, with a 6.1% CAGR to 2033. We regard this as the most defensible position because implant intensity per procedure is rising even where procedure volume growth is modest. The 6.1% figure is our synthesis, not a figure published verbatim by any single source, and should be read as an inference from share and growth differentials.
Year
Market size (synthesized)
2024
4.4 Billion
2025
4.7 Billion
2026
5.0 Billion
2027
5.3 Billion
2028
5.6 Billion
2029
5.9 Billion
2030
6.3 Billion
2031
6.7 Billion
2032
7.1 Billion
2033
7.5 Billion
How is the market segmented?
The market segments primarily by product form and by anatomical application, with material composition acting as a cross-cutting axis that increasingly determines reimbursement and surgeon preference.
Suture anchors dominate unit volume because they are consumed across nearly every soft-tissue repair. Bioabsorbable materials are the fastest-growing sub-segment, driven by reduced imaging artifact and avoidance of a second removal surgery. Ambulatory surgery centers are the fastest-growing end-user channel, reflecting payer pressure toward same-day procedures.
Which region leads in Arthroscopic Implants Market?
North America leads with roughly 41% of global implant revenue, reflecting high orthopedic procedure volumes, broad reimbursement coverage, and rapid surgeon adoption of knotless and bioabsorbable platforms.
Asia Pacific is the growth engine rather than the volume leader. Expanding healthcare access, rising sports participation, and government hospital investment support double-digit procedural growth in China and India, but average selling prices there are lower. This divergence implies that global revenue share will shift slowly even as unit growth shifts quickly — a distinction that matters enormously for capacity planning.
What is driving growth — and what is holding it back?
The dominant driver is a structural shift in procedure mix: surgeons are converting open repairs to arthroscopic techniques, and each conversion raises implant consumption per case. This is amplified by an aging population and rising sports injury incidence.
Factor
Direction
Evidence strength
Mechanism
Conversion to minimally invasive repair
Growth
High
Higher implant intensity per converted case
Aging population and osteoarthritis burden
Growth
High
More rotator cuff, meniscal, and labral procedures
Sports injury incidence
Growth
Moderate
Younger patient cohort consumes premium fixation
Bioabsorbable and knotless innovation
Growth
Moderate
Premium pricing and surgeon preference
High implant and procedure cost
Restraint
High
Limits adoption in low- and middle-income settings
Reimbursement gaps
Restraint
Moderate
Raises out-of-pocket burden
Surgeon training shortfall
Restraint
Moderate
Slows adoption of advanced techniques
Device recalls and quality failures
Restraint
Moderate
Erodes procurement confidence
The balance clearly favors growth, but the constraint is not demand — it is affordability and trained-surgeon supply. Our analysis suggests the binding constraint on emerging-market revenue is pricing architecture, not clinical need.
Who are the leading vendors?
The competitive field is concentrated among large orthopedic and sports-medicine franchises, with material science and procedural workflow integration as the principal differentiators.
Vendor
Archetype
Implant positioning
Moat
Arthrex
Sports-medicine specialist
Broad anchor and knotless platform
Surgeon education ecosystem
Smith+Nephew
Diversified orthopedics
Knotless and bioabsorbable fixation
Portfolio breadth and training
Stryker
Diversified orthopedics
Fixation integrated with visualization and robotics
Capital-equipment pull-through
Johnson & Johnson (DePuy Mitek)
Diversified orthopedics
Anchor and screw systems
Scale and procurement access
Zimmer Biomet
Diversified orthopedics
Shoulder and sports fixation
Hospital relationships
Medtronic
Diversified medtech
Selected fixation and RF adjacencies
Channel reach
CONMED
Sports-medicine focused
Anchor and resection portfolio
Value-tier pricing
Differentiation rests less on the implant itself than on the surrounding system: instrumentation trays, disposable guides, and surgeon training. That creates meaningful switching costs because a surgeon trained on one anchor deployment mechanism resists changing mid-career. Our analysis suggests the strongest moat is educational, not mechanical.
What do buyers and operators need to know?
Procurement decisions in this category hinge on more than unit price. Buyers should evaluate the total system cost — implant, disposable instrumentation, tray reprocessing, and surgeon onboarding — because a lower-priced anchor that requires a proprietary guide can erase savings.
Switching costs are substantial. Standardizing on a single vendor platform reduces tray inventory and negotiation complexity but concentrates supply risk; dual-sourcing by application (knee versus shoulder) is a common hedge. Operators should scrutinize recall history and sterility documentation, since mechanical fixation failures and packaging sterility breaches are the most frequent quality events.
Regulatory compliance is the most underestimated risk. Implant clearance pathways vary materially by jurisdiction, and bioabsorbable materials face additional degradation and biocompatibility scrutiny. Buyers should confirm that a supplier's regulatory dossier supports the specific geographies they serve, not just the home market. Finally, ambulatory surgery center adoption changes case economics — implant pricing that assumes hospital reimbursement may not survive the ASC cost model.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a portfolio-over-hardware strategy. Implants are growing faster than the visualization and capital equipment that surround them, yet most vendor narratives still center on imaging and robotics. That mismatch is an opportunity: whoever wins implant loyalty also wins the consumable annuity that follows every procedure.
The strongest counter-argument is that implant price erosion in developed markets could offset volume growth, compressing revenue even as unit counts rise. That is credible — procurement consolidation is real — but it argues for premium mix shift (bioabsorbable, knotless) rather than for retreating from the category.
Investors should weight implant-intensive sports-medicine franchises above capital-equipment-only plays, and stress-test for continued ASP erosion in North America.
Vendors should prioritize surgeon training infrastructure and bioabsorbable material capability to defend premium pricing as ASC volume rises.
Operators should dual-source by anatomical application and validate regulatory dossiers per geography before committing to platform standardization.
What would change our conclusion: evidence of sustained double-digit implant ASP declines in the US, or a reimbursement policy shift that pushes complex repairs back to inpatient settings. Either would compress the premium-mix thesis materially. Precise sub-segment forecasting by material and country requires the full report's granular model.
Table 14: Europe Arthroscopic Implants Market Revenue Billion Forecast, by Product 2020 & 2034
Table 15: Europe Arthroscopic Implants Market Revenue Billion Forecast, by Material 2020 & 2034
Table 16: Europe Arthroscopic Implants Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How large is the arthroscopic implants market?
The global arthroscopic implants market is approximately USD 4.7 billion in 2025 and is projected to reach roughly USD 7.5 billion by 2033. Implants represent about 45–49% of total arthroscopic device revenue.
2. What is the growth rate for arthroscopic implants?
We estimate a 6.1% CAGR from 2026 to 2033, faster than the roughly 3.4–4.9% growth published for the broader arthroscopy device market. Rising implant intensity per procedure explains the differential.
3. Which application segment is largest?
Knee procedures account for roughly 40–45% of implant revenue, driven by meniscal repair and ligament reconstruction. Shoulder is the second-largest, and small-joint applications are growing fastest from a low base.
4. Who are the leading arthroscopic implant vendors?
Arthrex, Smith+Nephew, Stryker, Johnson & Johnson (DePuy Mitek), Zimmer Biomet, Medtronic, and CONMED lead the field. Differentiation rests primarily on surgeon training ecosystems and bioabsorbable material capability.
5. Why are bioabsorbable implants growing so quickly?
Bioabsorbable fixation avoids a second removal surgery and reduces imaging artifact on postoperative MRI. That clinical benefit supports premium pricing, though it also invites closer regulatory scrutiny of degradation profiles.
6. What limits market growth?
High implant and procedure costs, partial reimbursement coverage, shortages of trained arthroscopic surgeons, and periodic device recalls constrain adoption. Affordability, not clinical demand, is the binding constraint in emerging markets.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research architecture applies a 70/30 primary-to-secondary split, with primary intelligence as the evidentiary spine. We conducted structured in-depth interviews across the arthroscopic implant value chain, including raw material suppliers for PEEK and bioabsorbable polymers, specialized implant producers, contract manufacturing and sterilization partners, and global orthopedic distributors. Interview designations targeted decision-makers with direct visibility into volume and pricing: VP-level Sourcing leads, Heads of Orthopedic R&D, Technical Directors for fixation platforms, and Commercial Operations Leads responsible for hospital and ambulatory surgery center contracting.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Orthopedic R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory & Quality Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Implant Manufacturers & OEMs
45%
Raw Material & Polymer Suppliers
25%
Orthopedic Distributors
30%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases tracking anchor and knotless deployment mechanisms, and recognized technical standards bodies including ASTM International and ISO surgical implant committees. Regulatory pathways were cross-checked against FDA 510(k) and CE marking records. Competitor market research publications were deliberately excluded from the evidentiary base.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic orthopedic expenditure across procedure segments and implant intensity per case. The bottom-up model builds from manufacturer capacity, average selling prices by product tier, and end-use consumption at hospital and ASC level. Divergence between the two is resolved through procedure-volume reconciliation rather than simple averaging.


 Arthroscopic Implants Market