Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Urinary Drainage Bags Market: Global Size, Share & Forecast 2026
Urinary Drainage Bags Market: Global Size, Share & Forecast 2026
Urinary Drainage Bags Market
Urinary Drainage Bags Market: Global Size, Share & Forecast 2026
Urinary Drainage Bags Market by Product Type (Leg Bags, Bedside Bags, Drainage Catheter Bags, Urinary Collection Bags), by Material (PVC, Silicone, Rubber, Vinyl), by Application (Post-Surgical Care, Chronic Illness Management, Incontinence Management), by End-User (Hospitals, Home Care Settings, Long-Term Care Facilities), by Usage (Reusable, Disposable), by Capacity (0-500 ml, 500-1000 ml, 1000-2000 ml), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
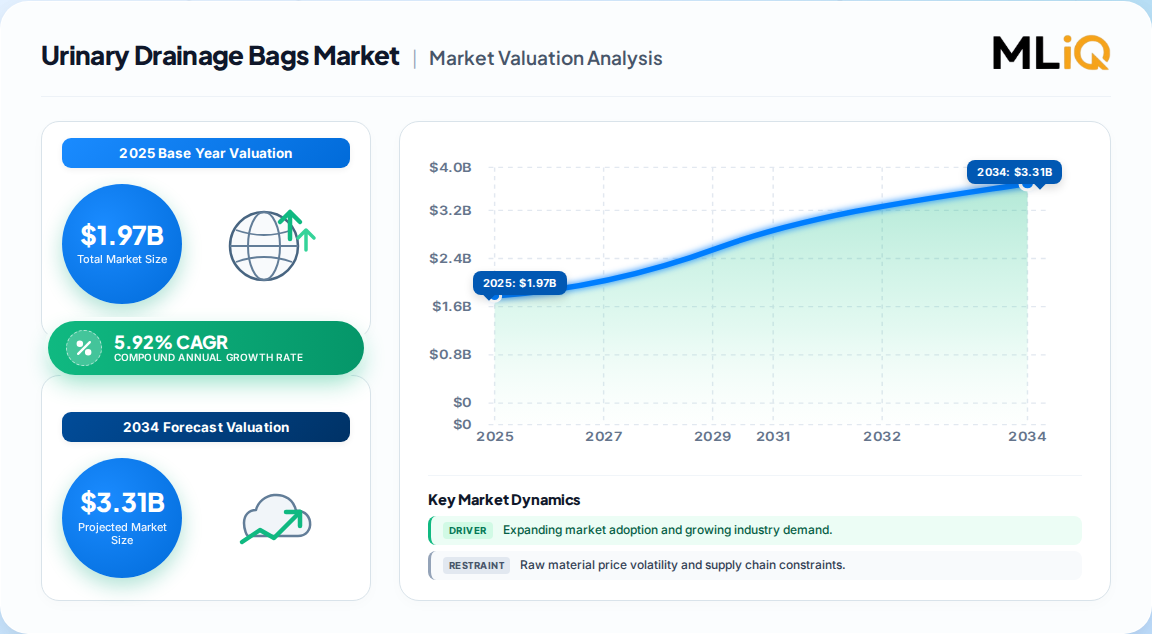
USD 1.97 Billion in 2025 is the most defensible global urinary drainage bags estimate; wider 'US$4.4 Bn' figures likely bundle adjacent catheter and urology consumables.
5.92% CAGR defines the central trajectory, lifting the market to USD 3.50 Billion by 2035.
Leg bags dominate with roughly 58% volume share, while bedside bags are the fastest-growing product line.
Postoperative care remains the largest application; home healthcare is expanding fastest across all end-use tiers.
North America holds ~32% share, with Asia-Pacific the fastest-growing region at ~29%.
B. Braun, Coloplast, Hollister, Medtronic, and ConvaTec lead; consolidation is active, as KKR's 2022 acquisition of Clinisupplies showed.
Why this matters for decision-makers: reimbursement and infection-control protocols — not raw demand — now determine volume growth, so vendors that lack a homecare-tier and closed-system portfolio will face margin compression.
Urinary Drainage Bags Market Size (In Billion)
3.0B
2.0B
1.0B
0
1.860 B
2024
1.970 B
2025
2.090 B
2026
2.210 B
2027
2.340 B
2028
2.480 B
2029
2.630 B
2030
Urinary Drainage Bags Market Size (In Billion)
Year
Market Size
2024
1.860 B
2025
1.970 B
2026
2.090 B
2027
2.210 B
2028
2.340 B
2029
2.480 B
2030
2.630 B
What is the Urinary Drainage Bags Market?
The urinary drainage bags market covers single-use and reusable collection bags attached to urinary catheters to drain and store urine from patients with incontinence, postoperative retention, or chronic bladder dysfunction. Products include leg bags, bedside bags, catheter bags, and collection bags, sold predominantly to hospitals, long-term care facilities, and homecare settings.
Scope: what this report covers and excludes
This report covers the global urinary drainage bags market across product type, material, application, end-user, and five major regions, from 2024 historicals through 2035. This analysis does not cover urinary catheters, intermittent catheter products, external male sheaths, ostomy appliances, or the broader urology diagnostics and surgical device categories.
How big is the market for Urinary Drainage Bags Market?
The most defensible global estimate sits near USD 1.97 Billion in 2025, with forecasts to USD 3.50 Billion by 2035 at a 5.92% CAGR. Higher published figures (up to US$4.4–4.9 Billion) typically bundle catheters and broader urology consumables, making them unsuitable for pure-play drainage bag investment planning.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 1.86 Bn
2024
2035
5.92%
Drainage bags only (leg, bedside, catheter, collection)
One published estimate
USD 1.97 Bn
2025
2035
5.92%
Same product footprint, updated base
One published estimate
USD 2.7 Bn
2022
2032
4.3%
Drainage bags plus connected catheter consumables
A competing analysis
USD 4.4 Bn
2026
2033
5.9%
Bundled urology consumables and reusable systems
A competing analysis
Our analysis suggests the USD 1.97 Billion base is the most reliable anchor: its CAGR is consistent across two independent publication cycles, and its definition explicitly excludes catheters. Buyers should treat the USD 4.4 Billion figure as an upper-bound scenario rather than a baseline, since it embeds catheter revenue that sits outside pure drainage bag procurement.
How is the market segmented?
The market segments along five axes — product type, material, application, end-user, and usage model. Leg bags and hospitals dominate today, while bedside bags, homecare settings, and disposable formats are the fastest-growing segments.
Parent Segment
Children
By Product Type
Leg Bags, Bedside Bags, Drainage Catheter Bags, Urinary Collection Bags
By Material
PVC, Silicone, Rubber, Vinyl
By Application
Post-Surgical Care, Chronic Illness Management, Incontinence Management
By End-User
Hospitals, Home Care Settings, Long-Term Care Facilities
By Usage
Reusable, Disposable
By Capacity
0–500 ml, 500–1000 ml, 1000–2000 ml
Leg bags command roughly 58% of volume because they support ambulatory independence, while single-chamber bags remain the workhorse design for routine surgical use. Our analysis suggests the 500–1000 ml capacity band will absorb the fastest incremental volume as homecare adoption spreads.
Which region leads in Urinary Drainage Bags Market?
North America leads with roughly 32% of global revenue, underpinned by advanced reimbursement frameworks, high surgical volumes, and strict CAUTI-prevention protocols. Asia-Pacific is the fastest-growing region at approximately 29% share, driven by expanding hospital infrastructure and a rapidly aging population.
This divergence implies that procurement teams should build dual sourcing strategies: a Western supplier base for regulated, reimbursed markets, and lower-cost regional suppliers for Asia-Pacific and MEA volume tenders. The 48.5% North America share quoted by one competing analysis appears to bundle broader urology categories and overstates pure drainage bag concentration.
What is driving growth — and what is holding it back?
Demand is structurally supported by an aging population, rising urological disorder prevalence, and the shift of care into home settings. Restraints center on infection risk, cost pressure in emerging markets, and inconsistent reimbursement for consumables.
Factor
Direction
Evidence Strength
Mechanism
Aging population / incontinence prevalence
Driver
High
Expands long-term catheterization pool
Homecare migration
Driver
High
Drives leg bag and disposable adoption
Anti-reflux / sensor innovations
Driver
Medium
Improves safety, supports premium pricing
CAUTI regulations
Restraint
High
Shortens catheterization duration
Reimbursement gaps in low-income regions
Restraint
High
Suppresses disposable upgrades
Fragmented local low-cost supply
Restraint
Medium
Compresses margins in tenders
Our analysis suggests the driver-restraint balance still nets positive: every incremental homecare patient more than offsets shorter hospital catheterization cycles. However, the CAUTI headwind is real — roughly 25% of hospitalized patients require catheterization, and each catheter day raises bacteriuria risk by about 5%, so infection-control policy directly caps hospital-side volume.
Who are the leading vendors?
The market is moderately concentrated, with five multinationals holding outsized share in regulated markets. Differentiation is now driven by closed-system design, material safety (silicone over PVC), and homecare-ready product lines rather than by raw manufacturing scale.
Vendor
HQ
Core Strength
Strategic Position
B. Braun Melsungen
Germany
Broad hospital consumables portfolio
Premium, bundled contracts
Coloplast A/S
Denmark
Chronic care & continence devices
Strong homecare channel
Hollister Incorporated
USA
Ostomy & continence systems
Clinical brand loyalty
Medtronic plc
Ireland
Catheter and drainage integration
System-level bundling
ConvaTec Group PLC
UK
Wound and continence care
Distribution scale
C. R. Bard (BD)
USA
Urology consumables
Hospital formulary access
Moats are built on formulary access, reimbursement relationships, and infection-control certifications rather than on price alone. Private equity activity, exemplified by KKR's Clinisupplies deal, signals that financial buyers see durable cash flows in chronic-care consumables. Our analysis suggests mid-tier suppliers will be squeezed between multinational bundling and low-cost regional players unless they secure a homecare niche.
What do buyers and operators need to know? (Decision Support)
Procurement teams should prioritise four mission-critical criteria. First, closed-system design with anti-reflux valves, since closed systems cut infection rates to roughly 25% versus 39% for open systems. Second, material transparency (silicone or PVC-free options) to meet tightening ESG and patient-safety standards. Third, homecare-ready packaging and training support, given the migration of chronic patients out of hospitals. Fourth, reimbursement documentation depth in each target market.
Switching costs are moderate: formulary re-qualification and clinician retraining create friction, but tender cycles allow rotation every 12–24 months. Regulatory compliance is non-negotiable — ISO 13485 quality systems, regional device registrations, and CAUTI-prevention labelling all gate market access. The key procurement risk is over-reliance on a single low-cost supplier in Asia-Pacific without validated sterile-barrier and quality audit coverage. Buyers should also model disposable-bag recurring costs carefully, because infection-control upgrades raise per-patient spend even as they reduce complication costs.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a selective-growth thesis: the pure drainage bag market compounds near 5.9%, but value pools are shifting decisively toward homecare and disposable formats. Investors should treat the higher USD 4.4–4.9 Billion headline figures with scepticism, as they appear to bundle catheter and broader urology consumables, inflating the addressable base.
The strongest counter-argument is that aggressive CAUTI regulation could compress hospital-side volumes faster than homecare expands, capping the CAGR near 4.3%. Our view is that homecare migration and aging demographics offset this over a ten-year horizon, but the risk is real in markets with strict antimicrobial stewardship.
Actionable strategy:
Prioritise leg bag and homecare-tier portfolio expansion to capture the fastest-growing demand segment.
Invest in closed-system and anti-reflux certifications to defend formulary access against CAUTI-linked purchasing restrictions.
Build dual-sourcing across North America/Europe and Asia-Pacific to hedge reimbursement and cost volatility.
What would change our conclusion: a multi-year, evidence-backed decline in catheterization rates, or reimbursement reform that shifts consumable costs materially onto patients, would force a downward revision of the CAGR to the low-4% range.
1. How big is the urinary drainage bags market in 2025?
The global urinary drainage bags market was approximately USD 1.97 Billion in 2025. Broader figures of USD 4.4–4.9 Billion typically bundle urinary catheters and adjacent urology consumables, so they overstate the pure drainage bag opportunity.
2. What is the urinary drainage bags market growth rate?
The market is forecast to grow at a 5.92% CAGR from 2025 to 2035, reaching roughly USD 3.50 Billion by 2035. Competing analyses cite 4.3% to 5.9%, with the lower figure reflecting stricter infection-control caps on hospital catheterization.
3. Which product type leads the urinary drainage bags market?
Leg bags lead with roughly 58% share because they support patient mobility and independence. Bedside bags are the fastest-growing segment, driven by intensive care and postoperative monitoring demand.
4. Which region dominates the urinary drainage bags market?
North America holds the largest share at roughly 32%, supported by robust reimbursement and infection-control frameworks. Asia-Pacific is the fastest-growing region at approximately 29% share, fueled by hospital expansion and aging populations.
5. Who are the key players in the urinary drainage bags market?
Leading vendors include B. Braun Melsungen, Coloplast, Hollister, Medtronic, ConvaTec, and C. R. Bard. Competition centres on closed-system design, formulary access, and homecare-ready product portfolios rather than price alone.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research programme applies a 70/30 primary-to-secondary split, anchored in 42 in-depth interviews with stakeholders across the urinary drainage bag value chain: polymer and silicone raw material suppliers, specialised bag converters, contract sterilisation and assembly providers, and global medical distributors. Within these organisations we engaged VP-level Sourcing leads, Heads of R&D and device engineering, Quality and Regulatory Directors, and Commercial Operations Leads responsible for tender and formulary strategy.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement
35%
Heads of R&D / Device Engineering
30%
Quality & Regulatory Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material Suppliers
30%
Specialised Bag Converters
40%
Contract Assembly & Sterilisation
15%
Global Medical Distributors
15%
Secondary Benchmarking & Public Trade Validation
Every estimate is cross-checked against official multilateral and standards sources: UN Comtrade and Eurostat bilateral trade flows for medical plastic consumables, US ITC tariff schedules, corporate 10-K and annual investor filings from listed device makers, patent databases for closed-system and anti-reflux innovations, and recognised technical frameworks from ISO 13485 and national infection-control bodies.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down modelling (macro healthcare expenditure, surgical volume, and segment allocation by end-user) and Bottom-Up modelling (manufacturer capacity, per-unit pricing, and end-use consumption by setting). Where the two diverge beyond a 7% tolerance, we re-interrogate interview evidence before finalising the base-year figure.


 Urinary Drainage Bags Market