Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Intravenous (IV) Therapy and Vein Access Market 2026 Outlook
Intravenous (IV) Therapy and Vein Access Market 2026 Outlook
Intravenous (IV) Therapy and Vein Access Market
Intravenous (IV) Therapy and Vein Access Market 2026 Outlook
Intravenous (IV) Therapy and Vein Access Market by Product Type (IV Catheters, Administration Sets & Connectors, IV Fluids & Solutions, Infusion Pumps, Implantable Ports, Hypodermic Needles), by Application (Oncology, Infectious Diseases, Gastroenterology & Parenteral Nutrition, Neurology, Pain Management), by End-User (Hospitals & Clinics, Homecare Settings, Ambulatory Surgical Centers), by Therapy Mode (Continuous IV Therapy, Intermittent IV Therapy, IV Push Therapy), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 214
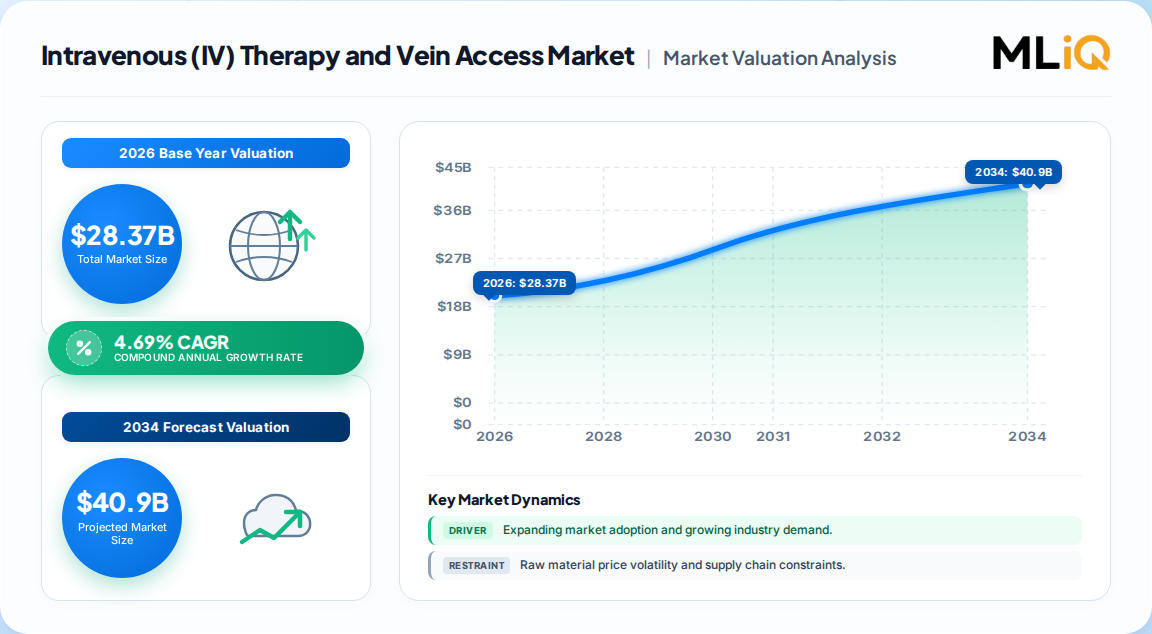
USD 28.37 billion in 2026, rising to USD 35.66 billion by 2031 at a 4.69% CAGR for the global intravenous (IV) therapy and vein access market.
IV catheters remain the largest product category at 36.78% of 2025 revenue, while infusion pumps grow fastest at a 5.19% CAGR.
Oncology is the leading application at 44.02% share; neurology is the fastest-growing application at a 5.49% CAGR.
Hospitals and clinics hold 62.51% of end-user revenue; homecare settings expand fastest at a 5.78% CAGR.
North America leads with 40.66% share (2025); Asia-Pacific posts the fastest regional CAGR at 6.12%.
Leading suppliers include Becton, Dickinson and Company, Terumo, Vygon, Teleflex, Fresenius Kabi, B. Braun and ICU Medical.
Why this matters for decision-makers: Vendors must pivot toward connected, closed-system and home-infusion portfolios to avoid margin compression in commoditized tubing and standard catheter categories.
Intravenous (IV) Therapy and Vein Access Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
27.10 B
2025
28.37 B
2026
29.70 B
2027
31.09 B
2028
32.55 B
2029
34.08 B
2030
35.66 B
2031
Intravenous (IV) Therapy and Vein Access Market Size (In Billion)
Year
Market Size
2025
27.10 B
2026
28.37 B
2027
29.70 B
2028
31.09 B
2029
32.55 B
2030
34.08 B
2031
35.66 B
What is the Intravenous (IV) Therapy and Vein Access Market?
The intravenous (IV) therapy and vein access market covers devices and consumables used to deliver fluids, drugs, nutrition and blood products directly into the venous system. It spans peripheral and central catheters, implantable ports, administration sets, connectors, infusion pumps and IV solutions, sold to hospitals, clinics and homecare providers.
Scope: what this report covers and excludes
This report covers global IV therapy and vein access devices, consumables and solutions across hospital, clinic, ambulatory and homecare settings, segmented by product type, application and end-user, with regional breakdowns for five continental regions. This analysis does not cover oral or subcutaneous drug delivery, standalone IV hydration wellness clinics, blood collection devices, or pharmaceutical manufacturing equipment.
How big is the market for Intravenous (IV) Therapy and Vein Access Market?
Published market estimates diverge sharply because analysts define the category differently: narrow device-only scopes produce roughly USD 25–28 billion base values, while device-plus-fluid scopes exceed USD 50 billion. The table below reconciles the leading published benchmarks.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 28.37 Billion
2026
2031
4.69%
Devices, sets, fluids and solutions
One published estimate
USD 25.42 Billion
2024
2031
5.50%
Devices plus solutions, global
One published estimate
USD 57 Billion
2024
2029
5.50%
Broad IV equipment including fluids
One published estimate
USD 34.19 Billion
2024
2035
4.01%
IV therapy and vein access devices
One published estimate
USD 22.8 Billion
2020
2030
5.30%
Device-focused, legacy base year
One published estimate
Our analysis suggests the USD 28.37 billion (2026) / 4.69% CAGR figure is the most defensible for device-and-consumable buyers: it sits in the middle of the device-focused cluster, uses a current base year, and its segment percentages reconcile against independent catheter and pump benchmarks. The USD 57 billion figure is credible only if IV fluids and broad equipment are included, which changes the competitive set entirely.
How is the market segmented?
Segment structure matters because growth is concentrated away from the largest categories: catheters dominate revenue, but pumps, homecare and neurology carry the highest growth rates.
Parent Segment
Children
Largest / Fastest
Product Type
IV catheters, administration sets and connectors, IV fluids and solutions, infusion pumps, implantable ports, hypodermic needles
Catheters largest (36.78%); pumps fastest (5.19% CAGR)
Application
Oncology, infectious diseases, gastroenterology and parenteral nutrition, neurology, pain management
Oncology largest (44.02%); neurology fastest (5.49% CAGR)
End-User
Hospitals and clinics, homecare settings, ambulatory surgical centers
Hospitals largest (62.51%); homecare fastest (5.78% CAGR)
Therapy Mode
Continuous IV therapy, intermittent IV therapy, IV push therapy
Continuous largest; intermittent fastest
Which region leads in Intravenous (IV) Therapy and Vein Access Market?
North America leads with 40.66% of 2025 revenue, but Asia-Pacific is the fastest-growing region at a 6.12% CAGR, and the gap between them is narrowing faster than most forecasts assume.
Intravenous (IV) Therapy and Vein Access Market Regional Market Share
Loading chart...
Intravenous (IV) Therapy and Vein Access Market Regional Market Share
Region
Market Share (%)
North America
0.41%
Europe
0.24%
Asia-Pacific
0.26%
Latin America
0.05%
Middle East & Africa
0.04%
North America — United States, Canada, Mexico
Europe — Germany, France, United Kingdom, Italy, Spain, Rest of Europe
Asia-Pacific — China, Japan, India, South Korea, Australia, Rest of APAC
Latin America — Brazil, Argentina, Colombia, Rest of Latin America
Middle East & Africa — Saudi Arabia, UAE, South Africa, Rest of MEA
Region
2025 Share
Growth Outlook
North America
40.66%
Moderate (mature, replacement-driven)
Europe
24%
Moderate (infection-control upgrades)
Asia-Pacific
26%
Fastest (6.12% CAGR)
Latin America
5%
Moderate
Middle East & Africa
4%
Emerging
What is driving growth — and what is holding it back?
Aging populations, oncology and biologics pipelines, home-infusion migration and infection-control mandates outweigh supply-chain fragility and antimicrobial resistance, but the restraint side is under-priced by most buyers.
Factor
Direction
Evidence Strength
Mechanism
Aging and chronic-disease burden
Driver (+1.2%)
High
~90% of hospitalized patients need IV access; geriatric multi-drug regimens
Home-infusion migration
Driver (+0.8%)
High
3.2 million patients/year; 7.5% annual home-infusion growth
Infection-control mandates
Driver (+0.6%)
High
Closed systems cut infection episodes 43% in tertiary deployments
AI-guided catheter placement
Driver (+0.4%)
Medium
>90% first-attempt success vs 78% manual in difficult access
Competition is medium-concentrated: diversified global players dominate catheters, pumps and fluids, while specialist firms defend niches through coatings, connectivity and vascular-access services.
Company
Portfolio Strength
Strategic Position
Becton, Dickinson and Company
Catheters, connectors, infusion systems
Scale leader; broad hospital installed base
Terumo Medical Corporation
Vascular access, administration sets
Strong in safety-engineered devices
B. Braun Melsungen
Catheters, pumps, IV solutions
Integrated device-plus-fluid model
Teleflex Incorporated
Central access, ultrasound guidance
Niche moat in difficult-access tools
Fresenius Kabi
IV fluids, infusion therapy
Fluids-led; homecare expansion lever
ICU Medical
Smart pumps, connectors
Closed-system and DERS differentiation
Vygon SAS
Neonatal and central access
Specialist premium positioning
Baxter International
Administration sets, solutions
Distribution breadth
What do buyers and operators need to know? (Decision Support)
Procurement decisions now hinge on total cost of failure, not unit price. A single failed peripheral IV episode costs roughly USD 1,100 in repeat sticks and delayed therapy, so buyers should score vendors on first-attempt success rates, catheter dwell time and infection-reduction evidence rather than catalogue price. Closed transfer devices and antimicrobial catheters command premiums but are increasingly mandated by infection-control scorecards and group-purchasing contracts.
Switching costs are highest in smart-pump fleets, where drug-library integration, EMR connectivity and nurse training create multi-year lock-in; buyers should negotiate interoperability and firmware-update clauses upfront. Regulatory compliance is non-negotiable: WHO and CDC catheter-management protocols and device-approval dossiers referencing quantitative microbial-ingress reduction targets now shape tender eligibility. Single-source resin and fluid dependencies remain the largest supply risk, and dual-sourcing plus inventory buffers are prudent.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a growth-accretive, technology-led repositioning rather than volume expansion. The market grows at only ~4.7%, but the premium segments — smart pumps, closed systems, antimicrobial catheters, home-infusion platforms — grow at 5.2–7.5%. Vendors anchored in standard tubing and commodity catheters will face price erosion; those that bundle connectivity, analytics and drug-library updates can defend margins.
The strongest counter-argument is reimbursement risk: payers are scrutinizing inpatient infusion and steering care to outpatient settings, which compresses per-procedure revenue even as volume rises. Our analysis suggests this is a mix shift, not a demand shock — homecare and ambulatory channels absorb the volume at lower prices but higher device attach rates. Asia-Pacific localization policies could also erode multinational share faster than the 6.12% CAGR implies.
Actionable strategy:
Prioritize closed-system and antimicrobial-coated portfolios to win infection-control-linked group-purchasing contracts.
Build home-infusion device-plus-service bundles with EMR connectivity to capture the 5.78% CAGR homecare channel.
Dual-source medical-grade resins and fluids to insulate against the supply disruptions that cost the sector in recent years.
Evidence that would change our conclusion: a sustained drop in oncology infusion volumes, or regulatory rejection of AI-guided access reimbursement, would weaken the premium-mix thesis and favor defensive, commodity-led positioning.
Intravenous (IV) Therapy and Vein Access Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Intravenous (IV) Therapy and Vein Access Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.69% from 2020-2034
Segmentation
By Product Type
IV Catheters
Administration Sets & Connectors
IV Fluids & Solutions
Infusion Pumps
Implantable Ports
Hypodermic Needles
By Application
Oncology
Infectious Diseases
Gastroenterology & Parenteral Nutrition
Neurology
Pain Management
By End-User
Hospitals & Clinics
Homecare Settings
Ambulatory Surgical Centers
By Therapy Mode
Continuous IV Therapy
Intermittent IV Therapy
IV Push Therapy
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Intravenous (IV) Therapy and Vein Access Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Intravenous (IV) Therapy and Vein Access Market Executive Summary
2.1. Market Snapshot
3. Intravenous (IV) Therapy and Vein Access Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Intravenous (IV) Therapy and Vein Access Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Intravenous (IV) Therapy and Vein Access Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. IV Catheters
5.1.2. Administration Sets & Connectors
5.1.3. IV Fluids & Solutions
5.1.4. Infusion Pumps
5.1.5. Implantable Ports
5.1.6. Hypodermic Needles
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Oncology
5.2.2. Infectious Diseases
5.2.3. Gastroenterology & Parenteral Nutrition
5.2.4. Neurology
5.2.5. Pain Management
5.3. Analysis, Insights and Forecast - by End-User
5.3.1. Hospitals & Clinics
5.3.2. Homecare Settings
5.3.3. Ambulatory Surgical Centers
5.4. Analysis, Insights and Forecast - by Therapy Mode
5.4.1. Continuous IV Therapy
5.4.2. Intermittent IV Therapy
5.4.3. IV Push Therapy
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Intravenous (IV) Therapy and Vein Access Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. IV Catheters
6.1.2. Administration Sets & Connectors
6.1.3. IV Fluids & Solutions
6.1.4. Infusion Pumps
6.1.5. Implantable Ports
6.1.6. Hypodermic Needles
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Oncology
6.2.2. Infectious Diseases
6.2.3. Gastroenterology & Parenteral Nutrition
6.2.4. Neurology
6.2.5. Pain Management
6.3. Analysis, Insights and Forecast - by End-User
6.3.1. Hospitals & Clinics
6.3.2. Homecare Settings
6.3.3. Ambulatory Surgical Centers
6.4. Analysis, Insights and Forecast - by Therapy Mode
6.4.1. Continuous IV Therapy
6.4.2. Intermittent IV Therapy
6.4.3. IV Push Therapy
7. Intravenous (IV) Therapy and Vein Access Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. IV Catheters
7.1.2. Administration Sets & Connectors
7.1.3. IV Fluids & Solutions
7.1.4. Infusion Pumps
7.1.5. Implantable Ports
7.1.6. Hypodermic Needles
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Oncology
7.2.2. Infectious Diseases
7.2.3. Gastroenterology & Parenteral Nutrition
7.2.4. Neurology
7.2.5. Pain Management
7.3. Analysis, Insights and Forecast - by End-User
7.3.1. Hospitals & Clinics
7.3.2. Homecare Settings
7.3.3. Ambulatory Surgical Centers
7.4. Analysis, Insights and Forecast - by Therapy Mode
7.4.1. Continuous IV Therapy
7.4.2. Intermittent IV Therapy
7.4.3. IV Push Therapy
8. Intravenous (IV) Therapy and Vein Access Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. IV Catheters
8.1.2. Administration Sets & Connectors
8.1.3. IV Fluids & Solutions
8.1.4. Infusion Pumps
8.1.5. Implantable Ports
8.1.6. Hypodermic Needles
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Oncology
8.2.2. Infectious Diseases
8.2.3. Gastroenterology & Parenteral Nutrition
8.2.4. Neurology
8.2.5. Pain Management
8.3. Analysis, Insights and Forecast - by End-User
8.3.1. Hospitals & Clinics
8.3.2. Homecare Settings
8.3.3. Ambulatory Surgical Centers
8.4. Analysis, Insights and Forecast - by Therapy Mode
8.4.1. Continuous IV Therapy
8.4.2. Intermittent IV Therapy
8.4.3. IV Push Therapy
9. Intravenous (IV) Therapy and Vein Access Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. IV Catheters
9.1.2. Administration Sets & Connectors
9.1.3. IV Fluids & Solutions
9.1.4. Infusion Pumps
9.1.5. Implantable Ports
9.1.6. Hypodermic Needles
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Oncology
9.2.2. Infectious Diseases
9.2.3. Gastroenterology & Parenteral Nutrition
9.2.4. Neurology
9.2.5. Pain Management
9.3. Analysis, Insights and Forecast - by End-User
9.3.1. Hospitals & Clinics
9.3.2. Homecare Settings
9.3.3. Ambulatory Surgical Centers
9.4. Analysis, Insights and Forecast - by Therapy Mode
9.4.1. Continuous IV Therapy
9.4.2. Intermittent IV Therapy
9.4.3. IV Push Therapy
10. Intravenous (IV) Therapy and Vein Access Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. IV Catheters
10.1.2. Administration Sets & Connectors
10.1.3. IV Fluids & Solutions
10.1.4. Infusion Pumps
10.1.5. Implantable Ports
10.1.6. Hypodermic Needles
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Oncology
10.2.2. Infectious Diseases
10.2.3. Gastroenterology & Parenteral Nutrition
10.2.4. Neurology
10.2.5. Pain Management
10.3. Analysis, Insights and Forecast - by End-User
10.3.1. Hospitals & Clinics
10.3.2. Homecare Settings
10.3.3. Ambulatory Surgical Centers
10.4. Analysis, Insights and Forecast - by Therapy Mode
10.4.1. Continuous IV Therapy
10.4.2. Intermittent IV Therapy
10.4.3. IV Push Therapy
11. Intravenous (IV) Therapy and Vein Access Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Intravenous (IV) Therapy and Vein Access Market Research Methodology
List of Figures
Figure 1: Intravenous (IV) Therapy and Vein Access Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Intravenous (IV) Therapy and Vein Access Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Intravenous (IV) Therapy and Vein Access Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Intravenous (IV) Therapy and Vein Access Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Intravenous (IV) Therapy and Vein Access Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Intravenous (IV) Therapy and Vein Access Market Revenue (Billion), by End-User 2026 & 2034
Figure 7: North America Intravenous (IV) Therapy and Vein Access Market Revenue Share (%), by End-User 2026 & 2034
Figure 8: North America Intravenous (IV) Therapy and Vein Access Market Revenue (Billion), by Therapy Mode 2026 & 2034
Figure 9: North America Intravenous (IV) Therapy and Vein Access Market Revenue Share (%), by Therapy Mode 2026 & 2034
Figure 10: North America Intravenous (IV) Therapy and Vein Access Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Intravenous (IV) Therapy and Vein Access Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Intravenous (IV) Therapy and Vein Access Market Revenue (Billion), by Product Type 2026 & 2034
Figure 13: Europe Intravenous (IV) Therapy and Vein Access Market Revenue Share (%), by Product Type 2026 & 2034
Figure 14: Europe Intravenous (IV) Therapy and Vein Access Market Revenue (Billion), by Application 2026 & 2034
Europe Intravenous (IV) Therapy and Vein Access Market Revenue Share (%), by Application 2026 & 2034
List of Tables
Table 1: Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 4: Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Therapy Mode 2020 & 2034
Table 5: Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 7: North America Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 9: North America Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Therapy Mode 2020 & 2034
Table 10: North America Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Intravenous (IV) Therapy and Vein Access Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Intravenous (IV) Therapy and Vein Access Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Intravenous (IV) Therapy and Vein Access Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Product Type 2020 & 2034
Europe Intravenous (IV) Therapy and Vein Access Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the intravenous (IV) therapy and vein access market?
The global intravenous (IV) therapy and vein access market is estimated at USD 28.37 billion in 2026 and is forecast to reach USD 35.66 billion by 2031, growing at a 4.69% CAGR over the period.
2. What is the fastest-growing segment in IV therapy and vein access?
Homecare settings are the fastest-growing end-user segment at a 5.78% CAGR, while infusion pumps lead product growth at 5.19% and neurology leads applications at 5.49% CAGR through 2031.
3. Which region dominates the IV therapy and vein access market?
North America held 40.66% of 2025 revenue, but Asia-Pacific is the fastest-growing region at a 6.12% CAGR, driven by healthcare modernization in China and India.
4. Who are the leading companies in IV therapy and vein access?
Key players include Becton, Dickinson and Company, Terumo Medical Corporation, B. Braun Melsungen, Teleflex, Fresenius Kabi, ICU Medical, Vygon and Baxter International, competing on catheters, pumps, fluids and connectivity.
5. Why is home infusion growing so quickly?
Medicare G-code reimbursement for remote dosing oversight, up to 30% lower total care costs, and compact two-way EMR-connected pumps are shifting oncology and infectious-disease therapy from wards to homes.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, with in-depth interviews across the IV therapy value chain: medical-grade resin and fluid suppliers, catheter and pump manufacturers, contract sterilizers and formulators, and global distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of R&D, Technical Directors for vascular access, and Commercial Operations Leads, ensuring both supply-side capacity and demand-side procurement behavior are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement
35%
Heads of R&D / Vascular Access
30%
Technical & Clinical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Catheter & Device Manufacturers
40%
IV Fluid & Solution Producers
25%
Contract Sterilizers & Formulators
20%
Global Distributors & GPOs
15%
Secondary Benchmarking & Public Trade Validation
Findings are benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent databases, and recognized technical standards bodies including ISO and AAMI infusion-device standards. These sources validate pricing, cross-border flow and regulatory compliance assumptions.
Demand Modeling & Market Sizing Triangulation
We triangulate simultaneously from the top down (macroeconomic and segment allocation across oncology, infectious disease and homecare) and the bottom up (manufacturer capacity, product pricing and end-use consumption modeling), reconciling gaps through iterative validation.


 Intravenous (IV) Therapy and Vein Access Market