Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
HCV Direct Acting Antiviral Market Outlook 2025
HCV Direct Acting Antiviral Market
HCV Direct Acting Antiviral Market Outlook 2025
HCV Direct Acting Antiviral Market by Drug Class (NS5B Polymerase Inhibitors, NS5A Inhibitors, NS3/4A Protease Inhibitors, Fixed-Dose Combinations), by Genotype Coverage (Pan-genotypic, Genotype-specific, Salvage/Retreatment), by Treatment Setting (Hospitals & Clinics, Community Pharmacies, Retail Clinics, Telemedicine), by Age Group (Below 18, 18-45, Above 45), by Component (Treatment, Diagnosis), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt) Forecast 2026-2034
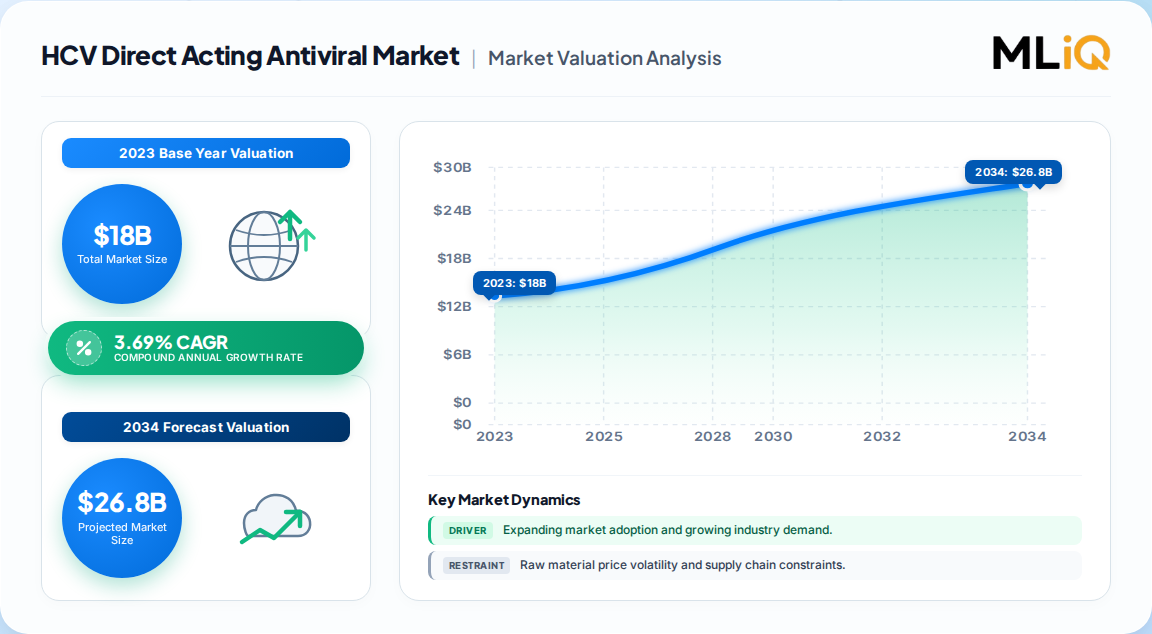
The global HCV direct acting antiviral market reached USD 18.0 Billion in 2023 across the total hepatitis C therapeutic and diagnostic envelope, with DAA regimens capturing roughly 87.6% of treatment revenue in 2025.
A published forecast projects the broader hepatitis C market to reach USD 47.1 Billion by 2034 at a 9.14% CAGR (2024–2034), while a second analysis projects only 3.69% CAGR to USD 18.96 Billion by 2031 — a definitional divergence we unpack below.
Pan-genotypic DAAs lead: sofosbuvir/velpatasvir holds ~55% share and glecaprevir/pibrentasvir ~34% of DAA dispensings in mature subsidised markets such as Australia.
North America leads with ~39.8% of 2025 hepatitis C revenue; Asia-Pacific is the fastest-growing region at ~4.8% CAGR on elimination-programme momentum.
Leading vendors include Gilead Sciences, AbbVie, Merck & Co., F. Hoffmann-La Roche, Bristol-Myers Squibb and Atea Pharmaceuticals (pipeline).
Why this matters for decision-makers: The curative success of DAAs is shrinking the chronic patient pool in high-income markets; vendors that do not pivot toward retreatment niches, resistance-guided salvage therapy and LMIC access pricing will face structural margin compression by 2030.
HCV Direct Acting Antiviral Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
18.00 B
2023
18.66 B
2024
19.36 B
2025
20.07 B
2026
20.81 B
2027
21.58 B
2028
22.38 B
2029
HCV Direct Acting Antiviral Market Size (In Billion)
Year
Market Size
2023
18.00 B
2024
18.66 B
2025
19.36 B
2026
20.07 B
2027
20.81 B
2028
21.58 B
2029
22.38 B
What is the HCV Direct Acting Antiviral Market?
The HCV direct acting antiviral market covers oral medicines that inhibit specific hepatitis C viral proteins (NS3/4A protease, NS5A, NS5B polymerase) to achieve sustained virologic response, plus the regimens, procurement contracts and payer pathways built around them. It excludes interferon-era therapies, vaccines and non-HCV antivirals.
Scope: what this report covers and excludes
This report covers the global market for HCV direct acting antivirals across branded and generic pan-genotypic and genotype-specific regimens, segmented by drug class, genotype coverage, treatment setting, distribution channel and geography. This analysis does not cover HCV diagnostics as a standalone market, hepatitis B or HIV antivirals, vaccines, or liver-transplant and oncology-adjacent therapeutics.
How big is the market for HCV Direct Acting Antiviral Market?
Estimates diverge sharply because some analyses size the entire hepatitis C envelope (diagnostics plus treatment) while others size DAAs alone. The table below reconciles the two anchor figures and clarifies which is most defensible for DAA-specific procurement.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 18.0 Billion
2023
2034
9.14%
Total hepatitis C market (DAA treatment + diagnostics + modulators)
One published trade estimate (2024)
USD 47.1 Billion
2034
2034
9.14%
Total hepatitis C market, same scope extended
Same published estimate
USD 15.83 Billion
2026
2031
3.69%
Hepatitis C market, component-segmented (treatment ~87.6%, diagnostics ~12.4%)
A competing analysis
USD 18.96 Billion
2031
2031
3.69%
Same competing analysis, forecast terminal
Same competing analysis
Our analysis suggests the 3.69% figure is more defensible for DAA-only revenue because the curative success of DAAs mechanically shrinks the treatable pool; the 9.14% CAGR likely embeds diagnostics expansion, immune-modulator combinations and emerging-market treatment volume that do not accrue to branded DAA pricing alone. Buyers should anchor procurement models on the lower DAA-specific trajectory and treat the higher figure as an upper bound contingent on aggressive elimination funding.
How is the market segmented?
Segmentation follows drug class, genotype coverage, treatment setting and channel. Treatment dominates revenue (~87.6% of 2025 hepatitis C spend), and the 18–45 age cohort is the largest patient segment at ~62.1%.
Hospitals & clinics, community pharmacies, retail clinics, telemedicine test-to-treat
By Age Group
Below 18, 18–45, above 45
By Component
Treatment (DAAs and combinations), diagnosis (blood tests, molecular assays)
Pan-genotypic fixed-dose combinations now account for nearly all DAA use in subsidised markets, which simplifies procurement but concentrates pricing power in two or three regimens.
Which regions lead in HCV Direct Acting Antiviral Market?
North America leads with approximately 39.8% of 2025 hepatitis C revenue, but Asia-Pacific is the fastest-growing region at ~4.8% CAGR, followed by community-pharmacy channels at ~5.4% CAGR. Geography below reflects the nested structure used throughout this report.
HCV Direct Acting Antiviral Market Regional Market Share
Loading chart...
HCV Direct Acting Antiviral Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Europe
0.22%
Asia-Pacific
0.26%
Latin America
0.06%
Middle East & Africa
0.06%
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy, Spain)
Asia Pacific (China, Japan, India, South Korea, Australia)
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt)
Region
2025 share
Growth signal
North America
40%
Largest revenue base; Medicaid expansion and USD 11 billion federal fund proposal
Europe
22%
Universal screening and subscription-style contracts
Asia-Pacific
26%
Fastest CAGR; Egypt-led elimination model spilling into MEA
Latin America
6%
Generic entry and PAHO procurement
Middle East & Africa
6%
Egypt programme treated >4 million at 87% cure
What is driving growth — and what is holding it back?
The principal driver is universal screening pulling undiagnosed cases into care, offset by the fact that curing patients removes them from the future revenue pool. The net balance is modest real growth in DAA-specific revenue, with regional divergence.
Uncovers hidden cases in primary care and ED settings
Government-funded national elimination initiatives
+0.9% CAGR
High
Egypt, Australia, Spain subscription models lock in volume
Point-of-care and molecular diagnostics
+0.8% CAGR
High
Finger-stick RNA results in <1 hour; 84% same-day initiation
Superior cure rates and shorter regimens
+0.6% CAGR
High
>95% SVR; 8–12 week therapy
Pharmacy-led test-to-treat models
+0.5% CAGR
Medium
Decentralised patient acquisition in developed markets
High branded cost & reimbursement gaps
-0.7% CAGR
High
~USD 24,000 course prices restrict access
Large undiagnosed pool & stigma
-0.4% CAGR
Medium
Sub-30% awareness in several countries
Specialist-prescription restrictions
-0.3% CAGR
Medium
Constrains treatment volume in regulated systems
Emerging resistance mutations
-0.2% CAGR
Medium
RAS in 3–5% of previously treated patients
Our analysis suggests the driver/restraint balance favours volume expansion in APAC and MEA while North America and Europe shift from growth to retreatment and salvage economics. The critical second-order effect: as pan-genotypic regimens simplify prescribing, procurement leverage migrates from specialists to national payers, compressing per-course pricing even as treated-patient counts rise.
Who are the leading vendors?
Gilead Sciences leads on pan-genotypic breadth (sofosbuvir/velpatasvir), with AbbVie strong in glecaprevir/pibrentasvir, Merck and Roche holding legacy and combination positions, and Atea Pharmaceuticals advancing a 2–4 week pipeline regimen. Differentiation rests on regimen duration, resistance profile and access pricing.
Competitive moats are built on pan-genotypic intellectual property, payer contracting and manufacturing scale rather than incremental efficacy; cure rates above 95% leave little clinical headroom, so price and access become the decisive battlegrounds.
What do buyers and operators need to know? (Decision Support)
Selection criteria should weight real-world SVR in retreatment populations, resistance-associated substitution coverage, regimen duration and total cost of cure rather than headline list price. Procurement risk concentrates in single-source pan-genotypic contracts and in reimbursement criteria tied to fibrosis stage or sobriety requirements, which can disqualify eligible patients.
Switching costs are moderate at the regimen level but high at the national-contract level, where multi-year subscription or capped-payment agreements lock in suppliers. Regulatory compliance spans WHO prequalification for LMIC procurement, national marketing authorisations, and pharmacovigilance obligations for direct-acting antiviral safety monitoring in cirrhotic patients.
Our analysis suggests buyers should require real-world retreatment efficacy data, not just registration-trial SVR, and should model generic entry timing in each jurisdiction, because generic sofosbuvir-based regimens are the principal price floor by 2028.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours a volume-up, price-down trajectory for HCV DAAs through 2031, with headline market growth of roughly 3.7–4.0% in DAA-specific terms despite the 9.14% figure published for the broader hepatitis C envelope. The strongest counter-argument is that a step-change in elimination funding — such as the proposed USD 11 billion US federal fund covering the uninsured — could add 400,000 annual treatment starts by 2027 and validate the higher growth path. We weight that scenario as plausible but not base case.
For operators, the strategic imperative is to move up the value chain: from selling cures to managing elimination programmes. Vendors that bundle diagnostics, telemedicine test-to-treat and outcome-based contracting will capture share as payers shift from per-course purchasing to population-health agreements. The corollary is that standalone DAA pricing will be commoditised faster than most forecasts assume.
Actionable strategy:
Investors should underweight pure-play branded DAA exposure and overweight integrated diagnostic-plus-therapeutic and elimination-programme service models.
Operators should build retreatment and resistance-guided salvage capabilities now, as 3–5% of treated patients will require them and this niche resists generic erosion.
Procurement teams should lock multi-year supply at capped-payment terms before generic entry resets the price floor in 2027–2028.
What would change our conclusion: a confirmed, fully funded US federal elimination fund exceeding USD 10 billion, or a Phase 3 ultra-short regimen achieving >95% SVR in 4 weeks, would justify upgrading the DAA-specific growth outlook toward the 6–8% range.
Strategic Outlook and Evidence Gaps
This overview synthesises the headline sizing, segmentation and vendor positions needed for board-level decisions. Precise sub-segment forecasting — by genotype, by retreatment cohort, by jurisdiction-level reimbursement timing — requires the full report's bottom-up model, which reconciles conflicting published estimates against real-world dispensing data and payer contract terms.
Buyers evaluating entry, expansion or divestment should treat the DAA-specific trajectory as the planning anchor and stress-test against the elimination-funding upside case. The gap between published estimates is itself the signal: disaggregating scope definitions is where competitive advantage is won.
HCV Direct Acting Antiviral Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
HCV Direct Acting Antiviral Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.69% from 2020-2034
Segmentation
By Drug Class
NS5B Polymerase Inhibitors
NS5A Inhibitors
NS3/4A Protease Inhibitors
Fixed-Dose Combinations
By Genotype Coverage
Pan-genotypic
Genotype-specific
Salvage/Retreatment
By Treatment Setting
Hospitals & Clinics
Community Pharmacies
Retail Clinics
Telemedicine
By Age Group
Below 18
18-45
Above 45
By Component
Treatment
Diagnosis
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Egypt
Table of Contents
1. HCV Direct Acting Antiviral Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. HCV Direct Acting Antiviral Market Executive Summary
2.1. Market Snapshot
3. HCV Direct Acting Antiviral Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. HCV Direct Acting Antiviral Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. HCV Direct Acting Antiviral Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Drug Class
5.1.1. NS5B Polymerase Inhibitors
5.1.2. NS5A Inhibitors
5.1.3. NS3/4A Protease Inhibitors
5.1.4. Fixed-Dose Combinations
5.2. Analysis, Insights and Forecast - by Genotype Coverage
5.2.1. Pan-genotypic
5.2.2. Genotype-specific
5.2.3. Salvage/Retreatment
5.3. Analysis, Insights and Forecast - by Treatment Setting
5.3.1. Hospitals & Clinics
5.3.2. Community Pharmacies
5.3.3. Retail Clinics
5.3.4. Telemedicine
5.4. Analysis, Insights and Forecast - by Age Group
5.4.1. Below 18
5.4.2. 18-45
5.4.3. Above 45
5.5. Analysis, Insights and Forecast - by Component
5.5.1. Treatment
5.5.2. Diagnosis
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. HCV Direct Acting Antiviral Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Drug Class
6.1.1. NS5B Polymerase Inhibitors
6.1.2. NS5A Inhibitors
6.1.3. NS3/4A Protease Inhibitors
6.1.4. Fixed-Dose Combinations
6.2. Analysis, Insights and Forecast - by Genotype Coverage
6.2.1. Pan-genotypic
6.2.2. Genotype-specific
6.2.3. Salvage/Retreatment
6.3. Analysis, Insights and Forecast - by Treatment Setting
6.3.1. Hospitals & Clinics
6.3.2. Community Pharmacies
6.3.3. Retail Clinics
6.3.4. Telemedicine
6.4. Analysis, Insights and Forecast - by Age Group
6.4.1. Below 18
6.4.2. 18-45
6.4.3. Above 45
6.5. Analysis, Insights and Forecast - by Component
6.5.1. Treatment
6.5.2. Diagnosis
7. HCV Direct Acting Antiviral Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Drug Class
7.1.1. NS5B Polymerase Inhibitors
7.1.2. NS5A Inhibitors
7.1.3. NS3/4A Protease Inhibitors
7.1.4. Fixed-Dose Combinations
7.2. Analysis, Insights and Forecast - by Genotype Coverage
7.2.1. Pan-genotypic
7.2.2. Genotype-specific
7.2.3. Salvage/Retreatment
7.3. Analysis, Insights and Forecast - by Treatment Setting
7.3.1. Hospitals & Clinics
7.3.2. Community Pharmacies
7.3.3. Retail Clinics
7.3.4. Telemedicine
7.4. Analysis, Insights and Forecast - by Age Group
7.4.1. Below 18
7.4.2. 18-45
7.4.3. Above 45
7.5. Analysis, Insights and Forecast - by Component
7.5.1. Treatment
7.5.2. Diagnosis
8. HCV Direct Acting Antiviral Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Drug Class
8.1.1. NS5B Polymerase Inhibitors
8.1.2. NS5A Inhibitors
8.1.3. NS3/4A Protease Inhibitors
8.1.4. Fixed-Dose Combinations
8.2. Analysis, Insights and Forecast - by Genotype Coverage
8.2.1. Pan-genotypic
8.2.2. Genotype-specific
8.2.3. Salvage/Retreatment
8.3. Analysis, Insights and Forecast - by Treatment Setting
8.3.1. Hospitals & Clinics
8.3.2. Community Pharmacies
8.3.3. Retail Clinics
8.3.4. Telemedicine
8.4. Analysis, Insights and Forecast - by Age Group
8.4.1. Below 18
8.4.2. 18-45
8.4.3. Above 45
8.5. Analysis, Insights and Forecast - by Component
8.5.1. Treatment
8.5.2. Diagnosis
9. HCV Direct Acting Antiviral Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Drug Class
9.1.1. NS5B Polymerase Inhibitors
9.1.2. NS5A Inhibitors
9.1.3. NS3/4A Protease Inhibitors
9.1.4. Fixed-Dose Combinations
9.2. Analysis, Insights and Forecast - by Genotype Coverage
9.2.1. Pan-genotypic
9.2.2. Genotype-specific
9.2.3. Salvage/Retreatment
9.3. Analysis, Insights and Forecast - by Treatment Setting
9.3.1. Hospitals & Clinics
9.3.2. Community Pharmacies
9.3.3. Retail Clinics
9.3.4. Telemedicine
9.4. Analysis, Insights and Forecast - by Age Group
9.4.1. Below 18
9.4.2. 18-45
9.4.3. Above 45
9.5. Analysis, Insights and Forecast - by Component
9.5.1. Treatment
9.5.2. Diagnosis
10. HCV Direct Acting Antiviral Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Drug Class
10.1.1. NS5B Polymerase Inhibitors
10.1.2. NS5A Inhibitors
10.1.3. NS3/4A Protease Inhibitors
10.1.4. Fixed-Dose Combinations
10.2. Analysis, Insights and Forecast - by Genotype Coverage
10.2.1. Pan-genotypic
10.2.2. Genotype-specific
10.2.3. Salvage/Retreatment
10.3. Analysis, Insights and Forecast - by Treatment Setting
10.3.1. Hospitals & Clinics
10.3.2. Community Pharmacies
10.3.3. Retail Clinics
10.3.4. Telemedicine
10.4. Analysis, Insights and Forecast - by Age Group
10.4.1. Below 18
10.4.2. 18-45
10.4.3. Above 45
10.5. Analysis, Insights and Forecast - by Component
10.5.1. Treatment
10.5.2. Diagnosis
11. HCV Direct Acting Antiviral Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. HCV Direct Acting Antiviral Market Research Methodology
List of Figures
Figure 1: HCV Direct Acting Antiviral Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America HCV Direct Acting Antiviral Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 3: North America HCV Direct Acting Antiviral Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 4: North America HCV Direct Acting Antiviral Market Revenue (Billion), by Genotype Coverage 2026 & 2034
Figure 5: North America HCV Direct Acting Antiviral Market Revenue Share (%), by Genotype Coverage 2026 & 2034
Figure 6: North America HCV Direct Acting Antiviral Market Revenue (Billion), by Treatment Setting 2026 & 2034
Figure 7: North America HCV Direct Acting Antiviral Market Revenue Share (%), by Treatment Setting 2026 & 2034
Figure 8: North America HCV Direct Acting Antiviral Market Revenue (Billion), by Age Group 2026 & 2034
Figure 9: North America HCV Direct Acting Antiviral Market Revenue Share (%), by Age Group 2026 & 2034
Figure 10: North America HCV Direct Acting Antiviral Market Revenue (Billion), by Component 2026 & 2034
Figure 11: North America HCV Direct Acting Antiviral Market Revenue Share (%), by Component 2026 & 2034
Figure 12: North America HCV Direct Acting Antiviral Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America HCV Direct Acting Antiviral Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe HCV Direct Acting Antiviral Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 15: Europe HCV Direct Acting Antiviral Market Revenue Share (%), by Drug Class 2026 & 2034
List of Tables
Table 1: HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 2: HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Genotype Coverage 2020 & 2034
Table 3: HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Treatment Setting 2020 & 2034
Table 4: HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Age Group 2020 & 2034
Table 5: HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Component 2020 & 2034
Table 6: HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 8: North America HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Genotype Coverage 2020 & 2034
Table 9: North America HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Treatment Setting 2020 & 2034
Table 10: North America HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Age Group 2020 & 2034
Table 11: North America HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Component 2020 & 2034
Table 12: North America HCV Direct Acting Antiviral Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA HCV Direct Acting Antiviral Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada HCV Direct Acting Antiviral Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico HCV Direct Acting Antiviral Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the HCV direct acting antiviral market size?
The broader hepatitis C market reached USD 18.0 Billion in 2023, with DAA treatment capturing roughly 87.6% of treatment revenue. DAA-specific spend is best modelled in the mid-teens of billions for 2025, growing at a low-to-mid single-digit CAGR through 2031.
2. What is the HCV DAA market growth rate?
Published CAGRs diverge: 9.14% for the total hepatitis C envelope to 2034 versus 3.69% for DAA-weighted treatment revenue to 2031. The lower figure is more defensible for DAA-only revenue because curative therapy shrinks the treatable pool.
3. Which region leads the HCV direct acting antiviral market?
North America leads with approximately 39.8% of 2025 hepatitis C revenue, but Asia-Pacific is the fastest-growing region at roughly 4.8% CAGR, driven by national elimination programmes and generic entry.
4. Who are the leading HCV DAA companies?
Gilead Sciences leads with sofosbuvir/velpatasvir, followed by AbbVie with glecaprevir/pibrentasvir. Merck, Roche and Bristol-Myers Squibb hold portfolio positions, while Atea Pharmaceuticals is advancing an ultra-short regimen pipeline.
5. What is driving HCV DAA market growth?
Universal screening, point-of-care diagnostics and government-funded elimination programmes are the primary drivers, adding roughly 1.2%, 0.8% and 0.9% to CAGR respectively. High branded cost and reimbursement gaps are the largest restraints at -0.7%.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study employed a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the HCV antiviral value chain, including active pharmaceutical ingredient suppliers, specialised DAA formulators, contract manufacturing organisations, national procurement agencies and global distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors and Commercial Operations Leads at branded and generic manufacturers. Interviews targeted regimen selection economics, retreatment pathways and payer contracting dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Clinical Development Heads
40%
Procurement & Sourcing Directors
35%
Regulatory & Market Access Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
API & Specialty Chemical Producers
40%
DAA Formulators & CMOs
35%
Global Distributors & Procurement Agencies
25%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on UN Comtrade and WTO pharmaceutical trade statistics, US ITC and Eurostat data, corporate 10-K and SEC filings, annual investor presentations, patent databases including the EPO register, and recognised standards and clinical bodies such as the WHO and the European Association for the Study of the Liver. Public health programme disclosures from national elimination initiatives provided real-world dispensing validation.
Demand Modeling & Market Sizing Triangulation
Market sizing combined top-down macroeconomic and segment allocation with bottom-up manufacturer capacity, per-course pricing and treated-patient volume modelling. Dispensing data from national reimbursement schemes were used to reconcile published estimates and to isolate DAA-specific revenue from total hepatitis C envelope figures.


 HCV Direct Acting Antiviral Market