 Prenatal Vitamin Supplements Market
 Outlook 2025
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Prenatal Vitamin Supplements Market

Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 596.0 M |
| 2026 | 624.0 M |
| 2027 | 652.0 M |
| 2028 | 682.0 M |
| 2029 | 714.0 M |
| 2030 | 747.0 M |
| 2031 | 781.0 M |

The prenatal vitamin supplements market covers formulated vitamin and mineral products — folic acid, iron, calcium, essential fatty acids, and broader multivitamin complexes — consumed before conception, during pregnancy, and through lactation to support maternal health and fetal development. It spans prescription and over-the-counter formats sold via pharmacies, online channels, hospitals, and retail. This definition excludes infant formula and general adult multivitamins.
This report covers global prenatal vitamin supplement formulations across product type (folic acid, iron, calcium, essential fatty acids, and combination multivitamins), dosage form (tablets, capsules and softgels, gummies, liquids), and distribution channel (online pharmacies, hospital pharmacies, drug stores, supermarkets). It covers preconception through lactation use. This analysis does not cover infant formula, pediatric supplements, general adult multivitamins, or prenatal diagnostics and testing services.
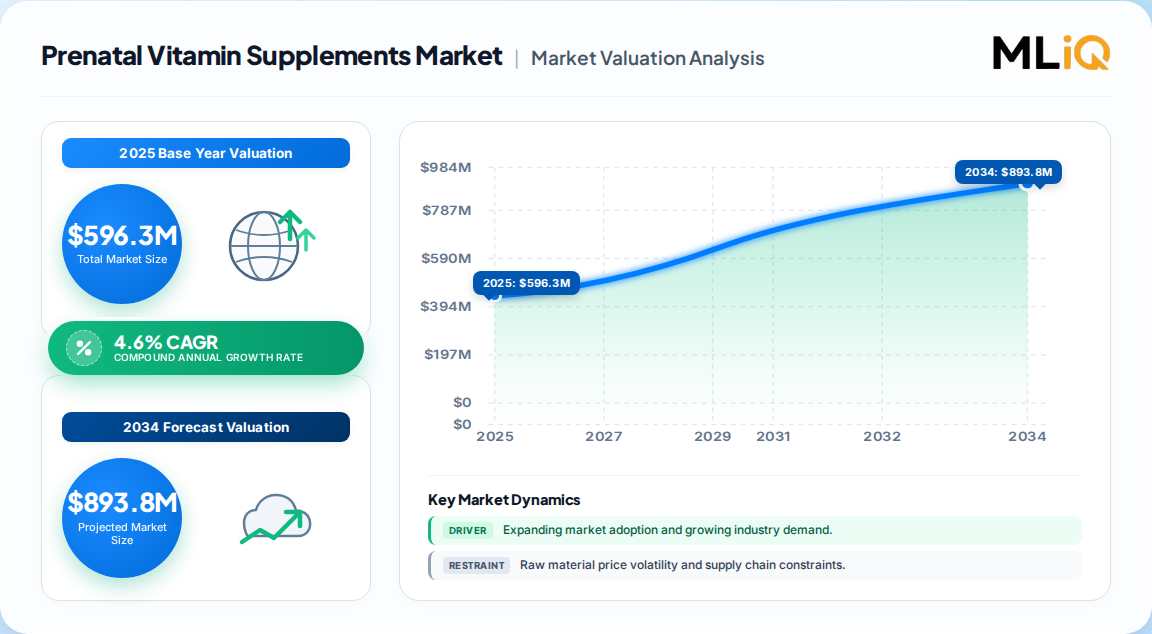
The most defensible base-year valuation is USD 596.3 million in 2025, rising to USD 934.9 million by 2035 at 4.6% CAGR, derived from a comprehensive preparation-level scope. Competing estimates diverge sharply because of definitional scope differences.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 596.3 Mn | 2025 | 2035 | 4.6% | Prenatal vitamin preparations, all channels | One published estimate |
| USD 1.25 Bn (North America only) | 2025 | 2031 | 9.19% | North America prenatal supplements, broader inclusion | A competing analysis |
| USD 73.2 Mn (ingredients only) | 2023 | 2032 | 6.1% | Prenatal vitamin ingredients, upstream only | A competing analysis |
Our analysis suggests the USD 596.3 million figure is the most defensible global preparation-level benchmark, while the North America figure reflects a broader supplements definition and a faster-growing regional base. The threefold divergence between the global preparation estimate and the North America supplements estimate is a definitional artifact, not a contradiction — buyers must align scope before comparing. The ingredients-market figure (USD 73.2 million) is an upstream subset and should not be read as a downstream demand signal.
Segmentation is structured around product type, dosage form, and distribution channel. Folic acid and online pharmacies are the leading segments in their respective dimensions, but the fastest growth is concentrated in gummies, essential fatty acids, and online retail.
| Parent Segment | Children | Leading Child (2025) | Fastest-Growing Child |
|---|---|---|---|
| Product Type | Folic Acid, Iron, Calcium, Essential Fatty Acids, Multivitamin Combinations | Folic Acid (37.8%) | Essential Fatty Acids |
| Dosage Form | Tablets, Capsules & Softgels, Gummies, Liquids | Capsules & Softgels | Gummies |
| Distribution Channel | Online Pharmacies, Hospital Pharmacies, Drug Stores, Supermarkets | Online Pharmacies (40.2%) | Online Pharmacies |
Our analysis suggests the folic acid segment will retain leadership through the forecast horizon because of entrenched clinical guidance, but essential fatty acids and gummies represent the highest-margin growth lanes for vendors seeking differentiation.
North America leads the global prenatal vitamin supplements market, anchored by the United States' dominant share, strong obstetric guidance, and high per-capita supplement spend. Asia-Pacific follows as the fastest-growing region, driven by rising maternal health awareness and expanding digital commerce.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.24% |
| Asia-Pacific | 0.31% |
| Latin America | 0.08% |
| Middle East & Africa | 0.05% |
| Region | Estimated Share (2025) | Growth Profile |
|---|---|---|
| North America | ~32% | Mature, premium-led |
| Asia-Pacific | ~31% | Fastest-growing |
| Europe | ~24% | Stable, regulation-driven |
| Latin America | ~8% | Emerging |
| Middle East & Africa | ~5% | Nascent |
This divergence implies that vendors should treat North America as a margin-defense market and Asia-Pacific as a volume-growth market — a dual strategy that most legacy players have not yet operationalized.
Growth is driven by rising maternal health awareness, clinical endorsement of folic acid and DHA, and the shift to preventive healthcare, while declining birth rates and inconsistent formulation standards restrain volume expansion. The net effect is moderate but durable mid-single-digit growth.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Maternal nutrition awareness and clinical guidance | Driver | High | Universal folic acid and DHA recommendations expand baseline demand |
| Online pharmacy and DTC expansion | Driver | High | Convenience, subscription models, and pricing transparency widen reach |
| Rising maternal age and premiumization | Driver | Medium | Older mothers spend more on preventive and personalized nutrition |
| Declining birth rates and smaller family sizes | Restraint | High | Shrinks the core addressable population in mature markets |
| Formulation inconsistency and weak regulation | Restraint | Medium | Undermines clinical trust and caps premium pricing power |
| Price sensitivity in emerging markets | Restraint | Medium | Limits premium tier penetration despite growing awareness |
Our analysis suggests the balance favors growth, but the quality of growth is shifting from volume to value — a distinction that materially affects vendor strategy.
The vendor landscape is fragmented and medium-concentration, with global nutrition majors competing against specialized prenatal brands and fast-scaling DTC players. Differentiation rests on clinical validation, formulation breadth, and channel reach.
| Company | Positioning | Strengths |
|---|---|---|
| Abbott Laboratories | Global nutrition major | Brand trust, hospital channel access |
| Rainbow Light | Specialized prenatal brand | Natural positioning, retail presence |
| Zahler | Premium formulations | Advanced ingredient profiles |
| FoodState, Inc | Whole-food nutrients | Bioavailability narrative |
| Contract NUTRA | Contract formulator | Manufacturing scale |
| Matsun Nutrition | Specialized manufacturer | Formulation flexibility |
| Mission Pharmacal | Clinical channel | Prescription-grade credibility |
Our analysis suggests competitive moats are built less on ingredient access and more on clinical endorsement and channel control — particularly hospital and online pharmacy relationships, which create switching costs.
Buyers should prioritize clinical validation and formulation transparency over brand recognition. The evidence base shows that many commercial prenatal supplements contain only a subset of essential vitamins and often at sub-optimal levels, creating real procurement risk for institutional buyers specifying products against clinical guidelines.
Regulatory compliance varies widely by market — from FDA dietary supplement frameworks in the US to stricter EU health claim regimes — and non-compliance can trigger recall and reputational exposure. Switching costs are moderate for consumers but high for institutional buyers bound by formulary and protocol validation. Operators should also monitor supply chain concentration in folic acid and DHA inputs, where single-source dependency creates pricing volatility. Online channel expansion introduces new compliance and counterfeit risk that buyers must diligence explicitly.
The balance of evidence favors a value-led growth thesis over a volume-led one: 4.6% CAGR is moderate, but premiumization, personalization, and online channel shift create disproportionate margin opportunity for vendors positioned at the clinical frontier. The strongest counter-argument is that declining birth rates in mature markets could compress the addressable base faster than premiumization offsets — a risk that is real but mitigated by rising maternal age and higher per-pregnancy spend.
Our analysis further suggests the market is under-served at the intersection of evidence-based dosing and convenient formats. The published research showing most commercial supplements fall short of optimal vitamin levels implies a credible differentiation pathway for vendors willing to invest in clinical substantiation — and a latent procurement risk for buyers who assume category equivalence.
Actionable strategy:
Evidence that would change this conclusion: a sustained acceleration in birth rates across North America and Europe, or regulatory harmonization that commoditizes formulation differences, would shift the thesis toward volume-led competition.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.6% from 2020-2034 |
| Segmentation |
|
The global prenatal vitamin supplements market was valued at USD 596.3 million in 2025 and is forecast to reach USD 934.9 million by 2035, growing at a 4.6% CAGR over the period.
Folic acid is the leading product segment at 37.8% revenue share in 2025, driven by universal clinical guidance for neural tube defect prevention before and during pregnancy.
Online pharmacies lead with 40.2% revenue share in 2025, supported by convenience, subscription delivery, competitive pricing, and growing trust in regulated e-pharmacy platforms.
Leading vendors include Abbott Laboratories, Rainbow Light, Zahler, FoodState, Contract NUTRA, Matsun Nutrition, and Mission Pharmacal, competing on clinical validation, formulation breadth, and channel access.
Asia-Pacific is the fastest-growing region, driven by rising maternal health awareness, expanding digital commerce, and growing disposable income, while North America retains the largest revenue share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material and vitamin ingredient suppliers, specialized prenatal supplement producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring coverage of both supply-side capability and demand-side procurement behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing | 30% |
| Heads of R&D & Formulation | 35% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ingredient Suppliers | 30% |
| Specialized Prenatal Producers | 35% |
| Contract Formulators | 20% |
| Global Distributors | 15% |
Secondary validation draws on official multilateral trade and standards databases — UN Comtrade, WTO, US ITC, and Eurostat — alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. These sources anchor market sizing in verifiable trade flows and published corporate disclosures rather than unverified aggregations.
We apply simultaneous Top-Down and Bottom-Up triangulation. The top-down model allocates macroeconomic and industry segment data to prenatal supplement demand, while the bottom-up model builds from manufacturer capacity, product pricing, and end-use consumption patterns across distribution channels. Convergence between the two approaches is required before a figure is accepted.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |