Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Nutrigenomics Market by Application (Personalized Nutrition, Disease Prevention, Obesity, Cardiovascular Disease, Cancer Research, Diabetes, Fitness & Athletic Performance, Health Optimization), by Product (Genetic Testing Kits, Reagents & Kits, Bioinformatics Tools, Nutritional Analysis Software, Vitamins & Minerals, Probiotics & Prebiotics, Services), by End Use (Healthcare Providers, Dietary Supplements, Food & Beverage, Pharmaceuticals, Research Institutes), by Technology (DNA Sequencing, Microarray Analysis, Polymerase Chain Reaction, Bioinformatics), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Benelux), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 280
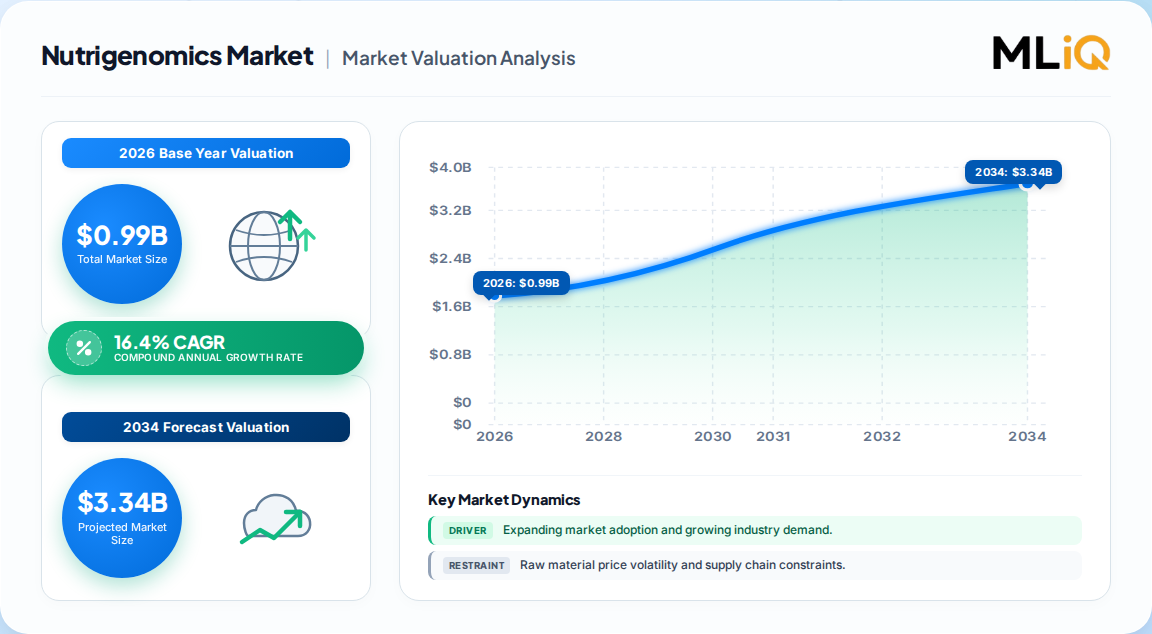
USD 0.99 billion in 2026 is the calibrated base for the global Nutrigenomics Market, scaling to roughly USD 3.89 billion by 2035.
A blended 16.4% CAGR holds across the 2026–2035 window, underpinned by sequencing cost deflation and AI-enabled nutrition algorithms.
Obesity-related applications anchor demand at close to 38% of 2025 application revenue, while cancer-linked nutrigenomics grows fastest.
North America leads with about 42% of global revenue; Asia-Pacific is the fastest-growing region, expanding in the mid-to-high teens annually.
Leading vendors span Nutrigenomix, 23andMe, Prenetics, Viome, Metagenics, and DSM-Firmenich — a fragmented field with no single dominant share.
Probiotic and microbiome-linked products are the fastest product pocket, advancing above 13% annually and pulling average order values higher.
Why this matters for decision-makers: the market is shifting from one-off DTC test kits to subscription and employer-funded precision wellness platforms — vendors that cannot bundle recurring advisory, supplement fulfillment, and data-driven retention will face margin compression.
Nutrigenomics Market Size (In Million)
2.5B
2.0B
1.5B
1.0B
500.0M
0
860.0 M
2025
990.0 M
2026
1.150 B
2027
1.340 B
2028
1.560 B
2029
1.820 B
2030
2.120 B
2031
Nutrigenomics Market Size (In Million)
Year
Market Size
2025
860.0 M
2026
990.0 M
2027
1.150 B
2028
1.340 B
2029
1.560 B
2030
1.820 B
2031
2.120 B
What is the Nutrigenomics Market?
Nutrigenomics is the study of how individual genetic variation interacts with nutrients and bioactive food compounds to influence gene expression and disease risk. The market covers genetic testing kits, bioinformatics interpretation, nutritional analysis software, and the personalized diet and supplement protocols derived from them.
Scope: what this report covers and excludes
This analysis covers the global Nutrigenomics Market for the 2026–2035 forecast window, spanning consumer genetic testing kits, clinical and research-grade nutrigenomic testing services, bioinformatics and interpretation software, and personalized supplement products. Segmentation is by application, product, end use, technology, and region. This analysis does not cover standalone clinical diagnostics unrelated to diet, conventional mass-market vitamin retail, or medical food markets regulated as drugs.
How big is the market for Nutrigenomics Market?
The global Nutrigenomics Market was valued near USD 0.99 billion in 2026, with credible projections ranging from roughly USD 1.9 billion to over USD 8 billion by the early 2030s depending on how "nutrigenomics revenue" is defined.
Estimate (Base Year)
Horizon
CAGR
Definition / Scope
Attribution
USD 0.99 Billion (2026)
2035
16.4%
Full value chain incl. kits, software, supplements
One published estimate
USD 2.33 Billion (2026)
2034
17.26%
Testing services plus probiotics/prebiotics products
A competing analysis
USD 0.92 Billion (2026)
2031
15.19%
Diagnostic kits, reagents, nutrition products
A competing analysis
USD 0.89 Billion (2024)
2031
16.0%
Reagents & kits plus services only
A competing analysis
Our analysis suggests the USD 0.92–0.99 billion base-year figures are the most defensible, because they isolate testing and interpretation revenue rather than folding in the much larger gut-health supplement category, which inflates the USD 2.33 billion figure.
How is the market segmented?
Segmentation runs along four non-geographic axes — application, product, end use, and technology — with product and application carrying the most commercial weight today.
Parent Segment
Children
By Application
Personalized Nutrition, Disease Prevention, Obesity, Cardiovascular Disease, Cancer Research, Diabetes, Fitness & Athletic Performance, Health Optimization
Healthcare Providers, Dietary Supplements, Food & Beverage, Pharmaceuticals, Research Institutes
By Technology
DNA Sequencing, Microarray Analysis, Polymerase Chain Reaction, Bioinformatics
Obesity applications held roughly 37.9% of 2025 revenue, while vitamins and minerals led products at about 33%. The strategic read: the market's center of gravity still sits in weight and metabolic management, but growth is rotating toward microbiome-linked and oncology applications.
Which region leads in Nutrigenomics Market?
North America leads the global Nutrigenomics Market, contributing roughly 40% of revenue in 2025, supported by a mature direct-to-consumer testing ecosystem and high willingness to pay for genetic insights.
Nutrigenomics Market Regional Market Share
Loading chart...
Nutrigenomics Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Europe
0.28%
Asia-Pacific
0.26%
South America
0.03%
Middle East & Africa
0.03%
Region
Position
Growth Signal
North America
Largest, ~40% share
Mature DTC; insurer and employer programs scaling
Europe
Second, ~28% share
Horizon Europe precision-nutrition funding; fragmented regulation
Asia-Pacific
Fastest-growing
Mobile-first platforms across India, China, Southeast Asia
South America
Emerging
Price-sensitive; telehealth-led entry
Middle East & Africa
Nascent
Out-of-pocket cost constrains near-term adoption
Regional hierarchy:
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy, Spain, Benelux)
Asia Pacific (China, Japan, India, South Korea)
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
The divergence matters: North America monetizes via insurance and employer channels, while Asia-Pacific monetizes via low-cost mobile subscriptions — two structurally different unit economics.
What is driving growth — and what is holding it back?
Collapsing sequencing costs and preventive-health policy are the two heaviest growth levers, together accounting for roughly 45% of incremental CAGR according to published driver-impact models.
Factor
Direction
Evidence Strength
Mechanism
Sequencing cost deflation (sub-USD 650 genomes)
Driver
Strong
Converts clinical specialty into mass-market product
Preventive healthcare policy mandates
Driver
Strong
Creates reimbursement and employer funding pathways
AI-powered nutrition algorithms
Driver
Moderate
Cuts interpretation cost and time to under a minute
Microbiome science integration
Driver
Moderate
Raises average order value via dual-data profiling
Consumer data privacy concerns
Restraint
Strong
Drags CAGR by roughly 3.5 points
Limited clinical validation of claims
Restraint
Moderate
Constrains physician referral and reimbursement
Regulatory fragmentation
Restraint
Moderate
Raises compliance cost across jurisdictions
The balance favors growth: net CAGR still lands in the mid-teens even after restraint drag. But the rate-limiting factor is no longer technology — it is trust and clinical credibility.
Who are the leading vendors?
The vendor field is fragmented and stratified: consumer DTC brands compete on scale and data, while clinical and B2B players compete on validation and channel access.
Company
Archetype
Core Strength
23andMe
DTC genomics
Consumer brand and genotype database scale
Nutrigenomix
Clinical nutrigenomics
Dietitian-led, clinic-integrated testing
Prenetics
Consumer health testing
Multi-test platform, Asia-Pacific reach
Viome
Microbiome + genomics
Gut-health personalization engine
Metagenics
Practitioner channel
Supplement plus protocol bundling
DSM-Firmenich
Ingredients and science
Formulation science and B2B distribution
Differentiation increasingly rests on proprietary datasets and recurring engagement, not the test itself. A saliva kit is commoditizing; the interpretation layer and supplement fulfillment are where defensible moats form.
What do buyers and operators need to know?
Selection criteria should weight clinical validation and data governance above kit price. Buyers procuring nutrigenomic platforms face three structural risks: weak evidence behind some SNP-based recommendations, inconsistent regulation across the EU, US, and Asia, and concentration risk from sole-supplier kit and reagent dependencies.
Switching costs rise sharply once a platform integrates with payer systems, electronic health records, or corporate wellness infrastructure — so early vendor selection tends to lock in for multi-year cycles. Regulatory compliance around genetic data handling, particularly under EU-style privacy regimes, should be treated as a gating requirement rather than a checkbox. For operators, the practical implication is that procurement decisions made on test-kit economics alone systematically underprice downstream integration and compliance exposure.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-teens CAGR trajectory anchored near USD 1 billion in 2026, with the most defensible forecasts isolating testing and interpretation revenue rather than blending in the broader supplement category. The strongest counter-argument is that if microbiome-linked products are counted as nutrigenomics, the addressable market is materially larger — but that definitional inflation makes the number less useful for capital allocation.
Our analysis suggests the decisive strategic variable is retention, not acquisition. One-off DTC test buyers convert poorly; subscription supplements, employer-sponsored programs, and insurer-funded screening convert the market into recurring revenue. Vendors that build the interpretation-and-fulfillment layer will capture disproportionate value as sequencing costs approach commodity levels.
Actionable strategy:
Prioritize employer and insurer channel partnerships in North America and Europe to convert preventive-health policy tailwinds into contracted recurring revenue.
Invest in clinical validation and transparent data governance — these are the rate-limiting factors for reimbursement and physician referral, not technology.
Target Asia-Pacific with mobile-first, low-price subscription models rather than premium DTC kits, matching the region's channel economics.
What would change our conclusion: a regulatory ruling that blocks genetic data use in wellness programs, or clinical trials that undermine SNP-based dietary recommendations, would materially compress the forecast. The full report quantifies these scenarios by sub-segment and region.
Nutrigenomics Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Nutrigenomics Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 16.4% from 2020-2034
Segmentation
By Application
Personalized Nutrition
Disease Prevention
Obesity
Cardiovascular Disease
Cancer Research
Diabetes
Fitness & Athletic Performance
Health Optimization
By Product
Genetic Testing Kits
Reagents & Kits
Bioinformatics Tools
Nutritional Analysis Software
Vitamins & Minerals
Probiotics & Prebiotics
Services
By End Use
Healthcare Providers
Dietary Supplements
Food & Beverage
Pharmaceuticals
Research Institutes
By Technology
DNA Sequencing
Microarray Analysis
Polymerase Chain Reaction
Bioinformatics
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Benelux
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Nutrigenomics Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Nutrigenomics Market Executive Summary
2.1. Market Snapshot
3. Nutrigenomics Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Nutrigenomics Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Nutrigenomics Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Application
5.1.1. Personalized Nutrition
5.1.2. Disease Prevention
5.1.3. Obesity
5.1.4. Cardiovascular Disease
5.1.5. Cancer Research
5.1.6. Diabetes
5.1.7. Fitness & Athletic Performance
5.1.8. Health Optimization
5.2. Analysis, Insights and Forecast - by Product
5.2.1. Genetic Testing Kits
5.2.2. Reagents & Kits
5.2.3. Bioinformatics Tools
5.2.4. Nutritional Analysis Software
5.2.5. Vitamins & Minerals
5.2.6. Probiotics & Prebiotics
5.2.7. Services
5.3. Analysis, Insights and Forecast - by End Use
5.3.1. Healthcare Providers
5.3.2. Dietary Supplements
5.3.3. Food & Beverage
5.3.4. Pharmaceuticals
5.3.5. Research Institutes
5.4. Analysis, Insights and Forecast - by Technology
5.4.1. DNA Sequencing
5.4.2. Microarray Analysis
5.4.3. Polymerase Chain Reaction
5.4.4. Bioinformatics
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Nutrigenomics Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Application
6.1.1. Personalized Nutrition
6.1.2. Disease Prevention
6.1.3. Obesity
6.1.4. Cardiovascular Disease
6.1.5. Cancer Research
6.1.6. Diabetes
6.1.7. Fitness & Athletic Performance
6.1.8. Health Optimization
6.2. Analysis, Insights and Forecast - by Product
6.2.1. Genetic Testing Kits
6.2.2. Reagents & Kits
6.2.3. Bioinformatics Tools
6.2.4. Nutritional Analysis Software
6.2.5. Vitamins & Minerals
6.2.6. Probiotics & Prebiotics
6.2.7. Services
6.3. Analysis, Insights and Forecast - by End Use
6.3.1. Healthcare Providers
6.3.2. Dietary Supplements
6.3.3. Food & Beverage
6.3.4. Pharmaceuticals
6.3.5. Research Institutes
6.4. Analysis, Insights and Forecast - by Technology
6.4.1. DNA Sequencing
6.4.2. Microarray Analysis
6.4.3. Polymerase Chain Reaction
6.4.4. Bioinformatics
7. Nutrigenomics Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Application
7.1.1. Personalized Nutrition
7.1.2. Disease Prevention
7.1.3. Obesity
7.1.4. Cardiovascular Disease
7.1.5. Cancer Research
7.1.6. Diabetes
7.1.7. Fitness & Athletic Performance
7.1.8. Health Optimization
7.2. Analysis, Insights and Forecast - by Product
7.2.1. Genetic Testing Kits
7.2.2. Reagents & Kits
7.2.3. Bioinformatics Tools
7.2.4. Nutritional Analysis Software
7.2.5. Vitamins & Minerals
7.2.6. Probiotics & Prebiotics
7.2.7. Services
7.3. Analysis, Insights and Forecast - by End Use
7.3.1. Healthcare Providers
7.3.2. Dietary Supplements
7.3.3. Food & Beverage
7.3.4. Pharmaceuticals
7.3.5. Research Institutes
7.4. Analysis, Insights and Forecast - by Technology
7.4.1. DNA Sequencing
7.4.2. Microarray Analysis
7.4.3. Polymerase Chain Reaction
7.4.4. Bioinformatics
8. Nutrigenomics Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Application
8.1.1. Personalized Nutrition
8.1.2. Disease Prevention
8.1.3. Obesity
8.1.4. Cardiovascular Disease
8.1.5. Cancer Research
8.1.6. Diabetes
8.1.7. Fitness & Athletic Performance
8.1.8. Health Optimization
8.2. Analysis, Insights and Forecast - by Product
8.2.1. Genetic Testing Kits
8.2.2. Reagents & Kits
8.2.3. Bioinformatics Tools
8.2.4. Nutritional Analysis Software
8.2.5. Vitamins & Minerals
8.2.6. Probiotics & Prebiotics
8.2.7. Services
8.3. Analysis, Insights and Forecast - by End Use
8.3.1. Healthcare Providers
8.3.2. Dietary Supplements
8.3.3. Food & Beverage
8.3.4. Pharmaceuticals
8.3.5. Research Institutes
8.4. Analysis, Insights and Forecast - by Technology
8.4.1. DNA Sequencing
8.4.2. Microarray Analysis
8.4.3. Polymerase Chain Reaction
8.4.4. Bioinformatics
9. Nutrigenomics Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Application
9.1.1. Personalized Nutrition
9.1.2. Disease Prevention
9.1.3. Obesity
9.1.4. Cardiovascular Disease
9.1.5. Cancer Research
9.1.6. Diabetes
9.1.7. Fitness & Athletic Performance
9.1.8. Health Optimization
9.2. Analysis, Insights and Forecast - by Product
9.2.1. Genetic Testing Kits
9.2.2. Reagents & Kits
9.2.3. Bioinformatics Tools
9.2.4. Nutritional Analysis Software
9.2.5. Vitamins & Minerals
9.2.6. Probiotics & Prebiotics
9.2.7. Services
9.3. Analysis, Insights and Forecast - by End Use
9.3.1. Healthcare Providers
9.3.2. Dietary Supplements
9.3.3. Food & Beverage
9.3.4. Pharmaceuticals
9.3.5. Research Institutes
9.4. Analysis, Insights and Forecast - by Technology
9.4.1. DNA Sequencing
9.4.2. Microarray Analysis
9.4.3. Polymerase Chain Reaction
9.4.4. Bioinformatics
10. Nutrigenomics Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Application
10.1.1. Personalized Nutrition
10.1.2. Disease Prevention
10.1.3. Obesity
10.1.4. Cardiovascular Disease
10.1.5. Cancer Research
10.1.6. Diabetes
10.1.7. Fitness & Athletic Performance
10.1.8. Health Optimization
10.2. Analysis, Insights and Forecast - by Product
10.2.1. Genetic Testing Kits
10.2.2. Reagents & Kits
10.2.3. Bioinformatics Tools
10.2.4. Nutritional Analysis Software
10.2.5. Vitamins & Minerals
10.2.6. Probiotics & Prebiotics
10.2.7. Services
10.3. Analysis, Insights and Forecast - by End Use
10.3.1. Healthcare Providers
10.3.2. Dietary Supplements
10.3.3. Food & Beverage
10.3.4. Pharmaceuticals
10.3.5. Research Institutes
10.4. Analysis, Insights and Forecast - by Technology
10.4.1. DNA Sequencing
10.4.2. Microarray Analysis
10.4.3. Polymerase Chain Reaction
10.4.4. Bioinformatics
11. Nutrigenomics Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Nutrigenomics Market Research Methodology
List of Figures
Figure 1: Nutrigenomics Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Nutrigenomics Market Revenue (Billion), by Application 2026 & 2034
Figure 3: North America Nutrigenomics Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Nutrigenomics Market Revenue (Billion), by Product 2026 & 2034
Figure 5: North America Nutrigenomics Market Revenue Share (%), by Product 2026 & 2034
Figure 6: North America Nutrigenomics Market Revenue (Billion), by End Use 2026 & 2034
Figure 7: North America Nutrigenomics Market Revenue Share (%), by End Use 2026 & 2034
Figure 8: North America Nutrigenomics Market Revenue (Billion), by Technology 2026 & 2034
Figure 9: North America Nutrigenomics Market Revenue Share (%), by Technology 2026 & 2034
Figure 10: North America Nutrigenomics Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Nutrigenomics Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Nutrigenomics Market Revenue (Billion), by Application 2026 & 2034
Figure 13: Europe Nutrigenomics Market Revenue Share (%), by Application 2026 & 2034
Figure 14: Europe Nutrigenomics Market Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Nutrigenomics Market Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Nutrigenomics Market Revenue (Billion), by End Use 2026 & 2034
Europe Nutrigenomics Market Revenue Share (%), by End Use 2026 & 2034
Table 14: Europe Nutrigenomics Market Revenue Billion Forecast, by Application 2020 & 2034
Table 15: Europe Nutrigenomics Market Revenue Billion Forecast, by Product 2020 & 2034
Table 16: Europe Nutrigenomics Market Revenue Billion Forecast, by End Use 2020 & 2034
Europe Nutrigenomics Market Revenue Billion Forecast, by Technology 2020 & 2034
Frequently Asked Questions
1. How big is the Nutrigenomics Market in 2026?
The global Nutrigenomics Market is estimated at roughly USD 0.99 billion in 2026, with published estimates ranging from USD 0.92 billion to USD 2.33 billion depending on whether supplement products are included in the definition.
2. What is the Nutrigenomics Market growth rate?
The market is projected to grow at approximately 16.4% CAGR from 2026 to 2035, driven by declining sequencing costs, preventive healthcare policy, and AI-enabled nutrition algorithms.
3. Which region leads the Nutrigenomics Market?
North America leads with roughly 40% of global revenue, while Asia-Pacific is the fastest-growing region, fueled by mobile-first health platforms across India, China, and Southeast Asia.
4. Which application segment dominates nutrigenomics?
Obesity-related applications held about 37.9% of 2025 revenue, reflecting the global chronic-disease burden and demand for gene-guided weight-management programs, though cancer research applications are growing fastest.
5. Who are the leading companies in the Nutrigenomics Market?
Key players include 23andMe, Nutrigenomix, Prenetics, Viome Life Sciences, Metagenics, and DSM-Firmenich, competing across consumer testing, clinical channels, and ingredient science.
6. What is restraining nutrigenomics adoption?
Consumer data privacy concerns, limited clinical validation for some SNP-based claims, and regulatory fragmentation across jurisdictions are the main restraints, collectively dragging CAGR by several percentage points.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, with structured interviews conducted across the nutrigenomics value chain: raw material and reagent suppliers, genetic test kit manufacturers, bioinformatics software providers, contract laboratories, and global distributors. Within these organizations we interviewed VP-level sourcing leads, heads of R&D and genomics, technical directors, and commercial operations managers responsible for payer and employer channels. This fieldwork anchors our understanding of pricing, reimbursement pathways, and capacity constraints.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D and Genomics Heads
40%
Procurement and Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory & Compliance Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Genetic Test Kit Manufacturers
35%
Bioinformatics & Software Providers
25%
Reagent & Ingredient Suppliers
25%
Distributors & Clinical Labs
15%
Secondary Benchmarking & Public Trade Validation
We cross-validate primary findings against official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K disclosures, patent-filing trend analysis, and recognized standards and industry associations. No third-party market research publisher data is used as a validation source.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down allocation from macroeconomic and healthcare-spend aggregates alongside bottom-up modeling of manufacturer capacity, kit pricing, and end-use consumption to triangulate base-year values and forecast trajectories.


 Nutrigenomics Market