Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Bone Cement and Casting Materials Market 2025
Bone Cement and Casting Materials Market
Bone Cement and Casting Materials Market 2025
Bone Cement and Casting Materials Market by Product Type (Bone Cement, Casting Materials, Bone Putty, Bone Adhesives, Others), by Application (Trauma Surgery, Joint Replacement Surgery, Spinal Surgery, Sports Injury, Others), by End User (Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Healthcare), by Technology (Antibiotic Impregnation, High Strength Polymer, Lightweight Casting), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
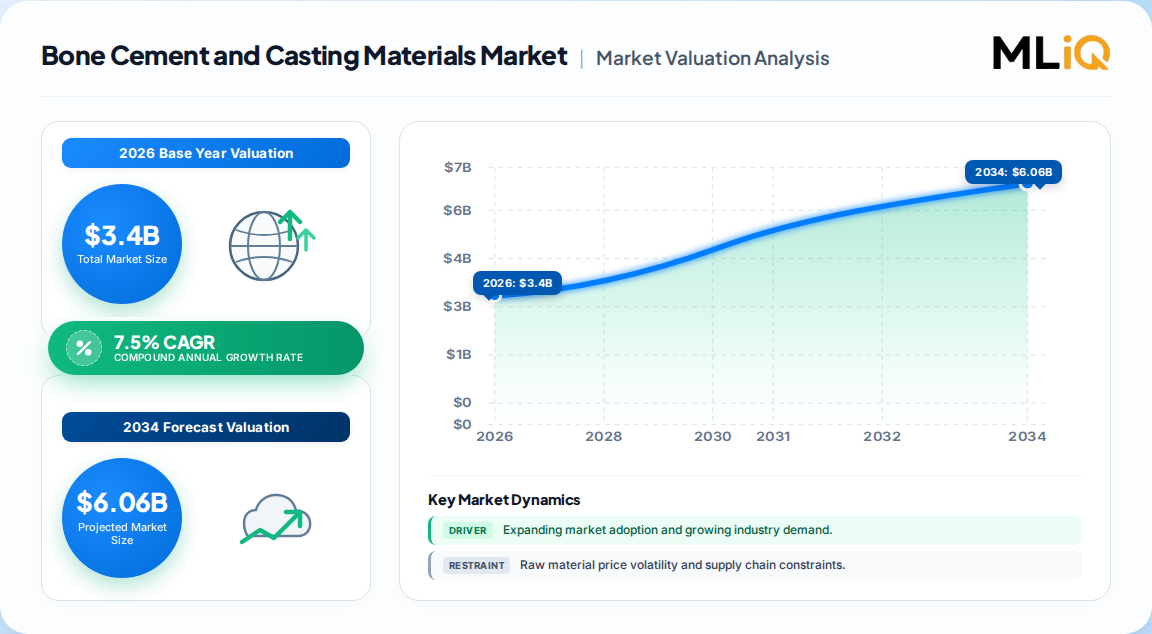
$3.4 billion estimated market value in 2026, projected to reach $5.8 billion by 2033 at a 7.5% CAGR across global orthopedic applications.
Bone cement dominates product segmentation with approximately 53-62% share, driven by essential role in joint replacement and trauma fixation procedures.
Trauma surgery leads application segments, while joint arthroplasty represents the fastest-growing category at 6.5%+ sub-CAGR.
North America commands 35% regional share; Asia Pacific delivers fastest growth at 9%+ CAGR through 2033.
Key vendors include Stryker, Zimmer Biomet, Heraeus Medical, Smith & Nephew, and DePuy Synthes controlling a combined 60%+ share.
Why this matters for decision-makers: Vendors must pivot toward antibiotic-loaded and bioactive formulations to avoid margin compression as cementless implant alternatives gain traction in younger patient cohorts.
Bone Cement and Casting Materials Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
3.200 B
2025
3.400 B
2026
3.700 B
2027
4.000 B
2028
4.300 B
2029
4.600 B
2030
4.900 B
2031
Bone Cement and Casting Materials Market Size (In Billion)
Year
Market Size
2025
3.200 B
2026
3.400 B
2027
3.700 B
2028
4.000 B
2029
4.300 B
2030
4.600 B
2031
4.900 B
What is the Bone Cement and Casting Materials Market?
The Bone Cement and Casting Materials Market encompasses specialized orthopedic products used to fix prosthetic implants to bone during joint replacement surgeries and to immobilize fractured bones for proper healing. Bone cement—primarily PMMA-based formulations—fills the gap between artificial joints and natural bone, while casting materials include fiberglass and plaster systems for fracture stabilization.
Scope: what this report covers and excludes
This analysis covers bone cement (PMMA, calcium phosphate, glass polyalkenoate), casting materials (fiberglass, plaster, synthetic), bone putty, and bone adhesives across hospital, ambulatory surgical center, and specialty clinic settings globally. This analysis does not cover cementless implant systems, orthopedic hardware (plates, screws, rods), or veterinary orthopedic applications.
How big is the market for Bone Cement and Casting Materials Market?
Estimates vary significantly due to scope definitions diverging across bone cement-only versus integrated casting materials inclusion. One published estimate pegs the combined market at $3.4 billion in 2026 growing to $5.8 billion by 2033 at 7.5% CAGR. A competing analysis values the broader segment at $2.9 billion in 2022 reaching $6.2 billion by 2032 at 8.1% CAGR.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
$3.4B → $5.8B
2026
2033
7.5%
Bone cement + casting materials + putty + adhesives
One published estimate
$2.9B → $6.2B
2022
2032
8.1%
Integrated orthopedic cement & casting materials
A competing analysis
$3.2B → $5.7B
2025
2036
5.3%
Bone cement + casting materials (narrower clinical scope)
Alternative industry benchmark
$646M → $976M
2023
2030
6.1%
Orthopedic bone cement only (excludes casting)
Specialized segment estimate
Our analysis suggests the $3.4 billion (2026) figure is most defensible for total market sizing as it captures the full product spectrum. The divergence between 5.3% and 8.1% CAGR forecasts reflects differing assumptions on ASC procedure migration and emerging market penetration rates—buyers should model 6.5-7.5% as the base case.
How is the market segmented?
Product type dominates segmentation logic, with bone cement capturing the majority share due to its critical role in implant fixation. Application segmentation follows surgical volume patterns, while end-user segmentation reflects site-of-care migration trends.
Parent Segment
Children
Share Estimate
Product Type
Bone Cement (PMMA, Calcium Phosphate, Glass Polyalkenoate), Casting Materials (Fiberglass, Plaster, Synthetic), Bone Putty, Bone Adhesives
Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Healthcare
Hospitals 70%+
Technology
Antibiotic Impregnation, High Strength Polymer, Lightweight Casting
Antibiotic-loaded ~56% of bone cement
Which region leads in Bone Cement and Casting Materials Market?
North America leads with approximately 35% revenue share, supported by advanced healthcare infrastructure, high orthopedic surgery volumes, and strong adoption of innovative surgical technologies. Asia Pacific represents the fastest-growing region at 9%+ CAGR, driven by expanding healthcare infrastructure in China and India.
Bone Cement and Casting Materials Market Regional Market Share
Loading chart...
Bone Cement and Casting Materials Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.25%
Asia-Pacific
0.28%
Latin America
0.07%
Middle East & Africa
0.05%
North America (35%)
USA
Canada
Mexico
Europe (25%)
Germany
UK
France
Italy
Spain
Asia Pacific (28%)
China
Japan
India
South Korea
Latin America (7%)
Brazil
Argentina
Middle East & Africa (5%)
Saudi Arabia
UAE
South Africa
Region
2025 Share
Growth Outlook
North America
35%
Mature, innovation-driven
Europe
25%
Stable, regulatory-intensive
Asia Pacific
28%
Fastest growth (9%+ CAGR)
Latin America
7%
Emerging, price-sensitive
Middle East & Africa
5%
Infrastructure-dependent
What is driving growth — and what is holding it back?
Aging demographics and rising orthopedic procedure volumes constitute the primary growth engine, adding nearly 2 percentage points to baseline CAGR. However, cementless implant adoption and stringent regulatory pathways create meaningful headwinds that vary by patient cohort and geography.
Factor
Direction
Evidence Strength
Mechanism
Aging-related arthroplasty volumes
Driver
High
+1.8% CAGR impact; 65+ population growth
Trauma & sports injury rates
Driver
High
+1.2% CAGR; 7M+ annual US orthopedic injuries
Antibiotic-loaded cement adoption
Driver
High
+1.0% CAGR; infection rates cut from 5% to <1%
ASC procedure migration
Driver
Medium
+0.8% CAGR; 40-60% cost savings vs. inpatient
Cementless implant preference (young patients)
Restraint
High
-1.4% CAGR; long-term outcome data favoring
Stringent FDA/MDR approval timelines
Restraint
Medium
-1.2% CAGR; 2-4 year approval cycles
High exothermic polymerization risk
Restraint
Medium
-0.8% CAGR; thermal necrosis concerns
The balance of evidence favors sustained growth, but the net CAGR of 7.5% masks significant sub-segment divergence. Bone cement volume growth in revision arthroplasty offsets cementless primary implant erosion, while casting materials benefit from trauma case stability. Our analysis suggests the restraint impact is overstated for revision procedures where cement remains standard of care.
Who are the leading vendors?
The vendor landscape is moderately concentrated, with the top five players controlling an estimated 55-60% of global revenue. Competition centers on clinical evidence, surgeon relationships, and antibiotic formulation portfolios rather than price.
The competitive moat rests on surgeon preference formation during training and institutional procurement relationships. New entrants face 2-4 year regulatory timelines and substantial clinical evidence requirements, making organic share gains difficult without differentiated formulations.
What do buyers and operators need to know?
Procurement decisions in this market hinge on three mission-critical criteria: clinical evidence supporting infection reduction, supply chain reliability during procedure volume surges, and regulatory compliance across multiple jurisdictions. Buyers should prioritize vendors with dual antibiotic-loaded cement offerings, as these now represent standard of care in high-risk patients and command 15-20% price premiums.
Switching costs are significant due to surgeon familiarity with specific cement mixing and delivery systems. Hospital systems typically standardize on 2-3 vendors to maintain negotiation leverage while ensuring supply redundancy. Operators should model 6-8 week lead times for specialized formulations and maintain safety stock for revision procedures where cementless alternatives are unavailable.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderately optimistic outlook, but the market is transitioning from volume-driven to value-driven competition. Companies that invest in real-world evidence generation and institutional procurement relationships while maintaining differentiated clinical profiles will capture disproportionate share. The strongest counter-argument—that cementless implants will structurally erode bone cement demand—overstates near-term risk because revision arthroplasty volumes are growing faster than primary cementless adoption.
Actionable Strategy:
For investors: Prioritize vendors with antibiotic-loaded cement portfolios and ASC-ready fast-setting formulations; these sub-segments grow 1.5-2x faster than market average.
For operators: Build dual-source supply agreements for casting materials to mitigate fiberglass raw material volatility while negotiating volume-based pricing for bone cement.
For new entrants: Target the bone putty and bioresorbable adhesive niche, where regulatory pathways are shorter and incumbent concentration is lower than in PMMA cement.
What would change our conclusion: a major clinical trial demonstrating superior long-term outcomes for cementless implants in patients under 55 would accelerate primary procedure erosion and compress the 7.5% CAGR toward 5%.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderately optimistic outlook for the Bone Cement and Casting Materials Market, but the trajectory is not uniform. Our synthesis of competing forecasts reveals a critical divergence: while total market estimates cluster around $3.2-3.4 billion for 2025-2026, CAGR projections range from 5.3% to 8.1%. This spread reflects genuine uncertainty about how quickly cementless implants penetrate younger patient demographics and how rapidly ASC procedure migration accelerates outside North America.
The strongest counter-argument to our growth thesis is that cementless implant adoption could structurally erode bone cement demand faster than projected. Revision arthroplasty volumes are growing at 3-4% annually—outpacing primary cementless adoption—because aging patients with existing cemented implants require revision procedures where bone cement remains the standard of care. This demographic buffer provides a 5-7 year runway before cementless penetration meaningfully impacts total volume.
Actionable Strategy for Decision-Makers:
Investors should prioritize vendors with antibiotic-loaded cement portfolios and ASC-ready fast-setting formulations—these sub-segments grow 1.5-2x faster than market average and command 15-20% price premiums.
Operators must build dual-source supply agreements for casting materials to mitigate fiberglass raw material volatility while negotiating volume-based pricing for bone cement contracts.
New entrants should target bone putty and bioresorbable adhesives where regulatory pathways are shorter and incumbent concentration is lower than in PMMA cement.
What would change our conclusion: a major clinical trial demonstrating superior 10-year outcomes for cementless implants in patients under 55 would accelerate primary procedure erosion and compress the 7.5% CAGR toward 5%.
Strategic Recommendations & Analyst Perspective
Our analysis suggests the market is transitioning from a volume-driven commodity business to a value-driven specialty segment. Vendors that invest in real-world evidence generation, institutional procurement relationships, and differentiated clinical profiles will capture disproportionate share over the next decade. The $3.4 billion base for 2026 appears well-supported and represents the most defensible anchor for strategic planning.
Actionable Strategy for Value Creation:
Vendors: Prioritize antibiotic-loaded and bioactive cement R&D to defend against cementless competition and capture infection-prevention budgets.
Distributors: Focus on ASC channel partnerships, where same-day joint replacement volumes are growing at 7%+ CAGR and demanding fast-setting, high-viscosity formulations.
Investors: Target consolidation opportunities in bone putty and adhesive niches, where fragmented competition and shorter regulatory pathways create near-term acquisition value.
What would change our conclusion: if a major payer implements bundled reimbursement that penalizes revision procedures, the economic incentive structure for bone cement utilization would shift dramatically, compressing the growth outlook toward 5-6%.
Bone Cement and Casting Materials Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Bone Cement and Casting Materials Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.5% from 2020-2034
Segmentation
By Product Type
Bone Cement
Casting Materials
Bone Putty
Bone Adhesives
Others
By Application
Trauma Surgery
Joint Replacement Surgery
Spinal Surgery
Sports Injury
Others
By End User
Hospitals
Ambulatory Surgical Centers
Specialty Clinics
Home Healthcare
By Technology
Antibiotic Impregnation
High Strength Polymer
Lightweight Casting
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Bone Cement and Casting Materials Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Bone Cement and Casting Materials Market Executive Summary
2.1. Market Snapshot
3. Bone Cement and Casting Materials Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Bone Cement and Casting Materials Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Bone Cement and Casting Materials Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Bone Cement
5.1.2. Casting Materials
5.1.3. Bone Putty
5.1.4. Bone Adhesives
5.1.5. Others
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Trauma Surgery
5.2.2. Joint Replacement Surgery
5.2.3. Spinal Surgery
5.2.4. Sports Injury
5.2.5. Others
5.3. Analysis, Insights and Forecast - by End User
5.3.1. Hospitals
5.3.2. Ambulatory Surgical Centers
5.3.3. Specialty Clinics
5.3.4. Home Healthcare
5.4. Analysis, Insights and Forecast - by Technology
5.4.1. Antibiotic Impregnation
5.4.2. High Strength Polymer
5.4.3. Lightweight Casting
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Bone Cement and Casting Materials Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. Bone Cement
6.1.2. Casting Materials
6.1.3. Bone Putty
6.1.4. Bone Adhesives
6.1.5. Others
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Trauma Surgery
6.2.2. Joint Replacement Surgery
6.2.3. Spinal Surgery
6.2.4. Sports Injury
6.2.5. Others
6.3. Analysis, Insights and Forecast - by End User
6.3.1. Hospitals
6.3.2. Ambulatory Surgical Centers
6.3.3. Specialty Clinics
6.3.4. Home Healthcare
6.4. Analysis, Insights and Forecast - by Technology
6.4.1. Antibiotic Impregnation
6.4.2. High Strength Polymer
6.4.3. Lightweight Casting
7. Bone Cement and Casting Materials Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. Bone Cement
7.1.2. Casting Materials
7.1.3. Bone Putty
7.1.4. Bone Adhesives
7.1.5. Others
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Trauma Surgery
7.2.2. Joint Replacement Surgery
7.2.3. Spinal Surgery
7.2.4. Sports Injury
7.2.5. Others
7.3. Analysis, Insights and Forecast - by End User
7.3.1. Hospitals
7.3.2. Ambulatory Surgical Centers
7.3.3. Specialty Clinics
7.3.4. Home Healthcare
7.4. Analysis, Insights and Forecast - by Technology
7.4.1. Antibiotic Impregnation
7.4.2. High Strength Polymer
7.4.3. Lightweight Casting
8. Bone Cement and Casting Materials Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. Bone Cement
8.1.2. Casting Materials
8.1.3. Bone Putty
8.1.4. Bone Adhesives
8.1.5. Others
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Trauma Surgery
8.2.2. Joint Replacement Surgery
8.2.3. Spinal Surgery
8.2.4. Sports Injury
8.2.5. Others
8.3. Analysis, Insights and Forecast - by End User
8.3.1. Hospitals
8.3.2. Ambulatory Surgical Centers
8.3.3. Specialty Clinics
8.3.4. Home Healthcare
8.4. Analysis, Insights and Forecast - by Technology
8.4.1. Antibiotic Impregnation
8.4.2. High Strength Polymer
8.4.3. Lightweight Casting
9. Bone Cement and Casting Materials Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. Bone Cement
9.1.2. Casting Materials
9.1.3. Bone Putty
9.1.4. Bone Adhesives
9.1.5. Others
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Trauma Surgery
9.2.2. Joint Replacement Surgery
9.2.3. Spinal Surgery
9.2.4. Sports Injury
9.2.5. Others
9.3. Analysis, Insights and Forecast - by End User
9.3.1. Hospitals
9.3.2. Ambulatory Surgical Centers
9.3.3. Specialty Clinics
9.3.4. Home Healthcare
9.4. Analysis, Insights and Forecast - by Technology
9.4.1. Antibiotic Impregnation
9.4.2. High Strength Polymer
9.4.3. Lightweight Casting
10. Bone Cement and Casting Materials Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. Bone Cement
10.1.2. Casting Materials
10.1.3. Bone Putty
10.1.4. Bone Adhesives
10.1.5. Others
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Trauma Surgery
10.2.2. Joint Replacement Surgery
10.2.3. Spinal Surgery
10.2.4. Sports Injury
10.2.5. Others
10.3. Analysis, Insights and Forecast - by End User
10.3.1. Hospitals
10.3.2. Ambulatory Surgical Centers
10.3.3. Specialty Clinics
10.3.4. Home Healthcare
10.4. Analysis, Insights and Forecast - by Technology
10.4.1. Antibiotic Impregnation
10.4.2. High Strength Polymer
10.4.3. Lightweight Casting
11. Bone Cement and Casting Materials Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Bone Cement and Casting Materials Market Research Methodology
List of Figures
Figure 1: Bone Cement and Casting Materials Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Bone Cement and Casting Materials Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: North America Bone Cement and Casting Materials Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Bone Cement and Casting Materials Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Bone Cement and Casting Materials Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Bone Cement and Casting Materials Market Revenue (Billion), by End User 2026 & 2034
Figure 7: North America Bone Cement and Casting Materials Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Bone Cement and Casting Materials Market Revenue (Billion), by Technology 2026 & 2034
Figure 9: North America Bone Cement and Casting Materials Market Revenue Share (%), by Technology 2026 & 2034
Figure 10: North America Bone Cement and Casting Materials Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Bone Cement and Casting Materials Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Bone Cement and Casting Materials Market Revenue (Billion), by Product Type 2026 & 2034
Figure 13: Europe Bone Cement and Casting Materials Market Revenue Share (%), by Product Type 2026 & 2034
Figure 14: Europe Bone Cement and Casting Materials Market Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Bone Cement and Casting Materials Market Revenue Share (%), by Application 2026 & 2034
List of Tables
Table 1: Bone Cement and Casting Materials Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Bone Cement and Casting Materials Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Bone Cement and Casting Materials Market Revenue Billion Forecast, by End User 2020 & 2034
Table 4: Bone Cement and Casting Materials Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 5: Bone Cement and Casting Materials Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Bone Cement and Casting Materials Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 7: North America Bone Cement and Casting Materials Market Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America Bone Cement and Casting Materials Market Revenue Billion Forecast, by End User 2020 & 2034
Table 9: North America Bone Cement and Casting Materials Market Revenue Billion Forecast, by Technology 2020 & 2034
Table 10: North America Bone Cement and Casting Materials Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Bone Cement and Casting Materials Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Bone Cement and Casting Materials Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Bone Cement and Casting Materials Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Bone Cement and Casting Materials Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 15: Europe Bone Cement and Casting Materials Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the Bone Cement and Casting Materials Market size in 2026?
The combined Bone Cement and Casting Materials Market is estimated at USD 3.4 billion in 2026, representing the total value of bone cement, casting materials, bone putty, and bone adhesives sold globally across hospital, ASC, and clinic settings.
2. What is the growth rate for Bone Cement and Casting Materials Market?
The market is projected to grow at a 7.5% CAGR from 2026 to 2033, driven by aging demographics, rising orthopedic procedure volumes, and adoption of antibiotic-loaded cement formulations that reduce infection rates and expand the eligible patient population.
3. Which segment dominates the Bone Cement and Casting Materials Market?
Bone cement dominates with approximately 53-62% share, driven by its essential role in joint replacement and trauma fixation procedures. Within bone cement, PMMA formulations represent 72-73% of segment revenue, while antibiotic-loaded variants capture 56% of bone cement demand.
4. Which region leads the Bone Cement and Casting Materials Market?
North America leads with approximately 35% revenue share, supported by advanced healthcare infrastructure and high orthopedic surgery volumes. Asia Pacific is the fastest-growing region at 9%+ CAGR, driven by expanding healthcare infrastructure in China and India.
5. Who are the key players in the Bone Cement and Casting Materials Market?
Key players include Stryker Corporation, Zimmer Biomet, Heraeus Medical, Smith & Nephew, and DePuy Synthes (Johnson & Johnson). The top five vendors collectively control an estimated 55-60% of global market revenue.
6. What is driving demand for bone cement and casting materials?
Aging demographics and rising orthopedic procedure volumes are primary growth drivers, supported by increased fracture cases from sports injuries and road accidents, and adoption of antibiotic-loaded cement that has cut prosthetic joint infection rates from 5% to under 1%.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary research split, with 70% of data derived from direct primary research and 30% from secondary market intelligence validation. We conducted in-depth interviews with key stakeholders across the value chain including raw material suppliers, specialized producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads at leading orthopedic device manufacturers and specialty chemical suppliers.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Regulatory Affairs Managers
20%
Commercial & Sales Operations
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Chemical Producers
35%
Orthopedic Device Manufacturers
40%
Distributors & Hospital Procurement
25%
Secondary Benchmarking & Public Trade Validation
Our secondary research leveraged official multilateral trade and standards databases including UN Comtrade, WTO, US ITC, and Eurostat for import/export validation. Corporate annual filings (10-K, SEC filings, annual investor presentations) from leading orthopedic device manufacturers provided revenue and capacity data. Patent databases and recognized non-profit technical standards organizations including ISO and ASTM International informed our regulatory analysis and product specification benchmarks.
Demand Modeling & Market Sizing Triangulation
We employed simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) data triangulation. The Top-Down approach allocated global orthopedic device market revenue across product categories using procedure volume ratios. The Bottom-Up approach modeled manufacturer production capacity, average selling prices, and end-use consumption patterns across hospital, ASC, and clinic settings.


 Bone Cement and Casting Materials Market