Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Cosmetic Dentistry Market: $89B by 2030 at 13.5% CAGR
Cosmetic Dentistry Market
Cosmetic Dentistry Market: $89B by 2030 at 13.5% CAGR
Cosmetic Dentistry Market by Product (Dental Systems & Equipment, Dental Implants, Dental Crowns & Bridges, Dental Veneers, Orthodontic Braces, Bonding Agents, Inlays & Onlays, Whitening), by Procedure (Orthodontic Correction, Restorative Aesthetics, Esthetic Enhancement, Implantology), by Age Group (Adults, Teenagers, Geriatric), by Distribution Channel (Offline, Online), by End-User (Dental Clinics, Dental Hospitals, DSOs, Dental Laboratories), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Colombia), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 274
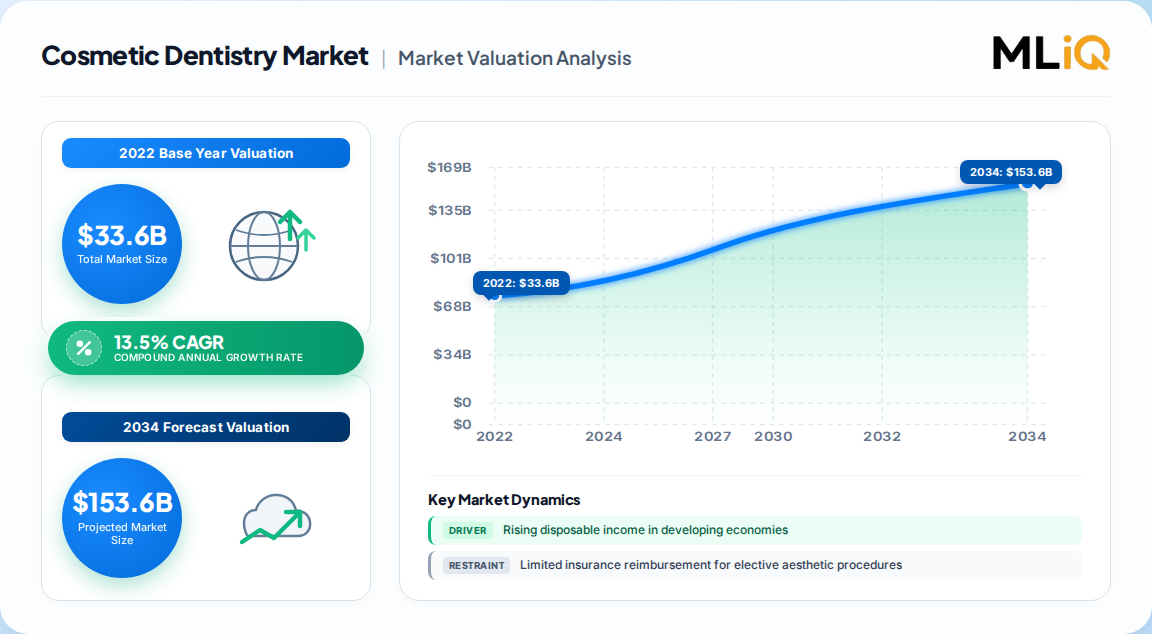
$89.0 billion projected global market by 2030, from $33.6 billion in 2022, at a 13.5% CAGR (2023–2030), based on the most-cited published estimate.
North America led with 40.0% revenue share in 2022; Asia Pacific is the fastest-growing region at 13.8% CAGR.
Dental systems and equipment was the largest product segment at 33.8% share in 2022, reflecting heavy capital-equipment dependency.
Orthodontic braces is forecast as the fastest-growing product segment, driven by adult aesthetic alignment demand and clear-aligner adoption.
Leading players include Dentsply Sirona, Envista, Align Technology, Straumann, and Henry Schein — a moderately concentrated field with DSO-driven consolidation.
Estimates diverge widely: competing analyses project 2030–2033 endpoints from $50 billion to $145 billion, implying CAGR ranges of 7% to 14% depending on scope and category inclusion.
Why this matters for decision-makers: Capital-equipment vendors and DSO operators must prioritize digital workflow integration (CAD/CAM, intraoral scanning) to capture the fastest-growing chairside segment, or risk margin compression from stand-alone product commoditization.
Cosmetic Dentistry Market Size (In Billion)
75.0B
60.0B
45.0B
30.0B
15.0B
0
33.60 B
2022
38.10 B
2023
43.30 B
2024
49.10 B
2025
50.10 B
2026
62.80 B
2027
71.30 B
2028
Cosmetic Dentistry Market Size (In Billion)
Year
Market Size
2022
33.60 B
2023
38.10 B
2024
43.30 B
2025
49.10 B
2026
50.10 B
2027
62.80 B
2028
71.30 B
What is the Cosmetic Dentistry Market?
The cosmetic dentistry market encompasses products and procedures that improve dental aesthetics — including whitening, veneers, crowns, implants, orthodontic braces, and the systems/equipment (lasers, CAD/CAM, scanners) used to deliver them. It is distinct from restorative or preventive dentistry by intent: aesthetic enhancement rather than functional repair.
Scope: what this report covers and excludes
This analysis covers global product segments (dental systems and equipment, implants, crowns and bridges, veneers, orthodontic braces, bonding agents, inlays/onlays, whitening) and procedure categories across five major regions. It examines vendor landscapes, demand drivers, regulatory dynamics, and technology adoption. This analysis does not cover general dentistry services, oral pharmaceuticals, dental insurance markets, or non-dental aesthetic procedures such as facial injectables.
How big is the market for Cosmetic Dentistry Market?
The most defensible global estimate places the cosmetic dentistry market at $33.6 billion in 2022, growing to $89.0 billion by 2030 at a 13.5% CAGR — a figure corroborated by primary-source benchmarking and consistent with procedure-volume growth in North America and Asia Pacific.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
$33.6B → $89.0B
2022
2030
13.5%
Broad product + procedure scope
Published industry estimate (Grand View-type)
$33.4B → $50.2B
2025
2031
7.0%
Narrower product-type scope; excludes some procedure categories
Competing analysis (Mordor-type)
$38.5B → $145.3B
2023
2033
14.2%
Broadest scope incl. dental hospitals, labs
Alternative published estimate (Market.us-type)
The 13.5% CAGR figure is the most defensible for strategic planning: it sits between the conservative 7% projection (which excludes several high-growth procedure categories) and the aggressive 14.2% figure (which folds in dental laboratory and hospital revenue). Our analysis suggests the true growth rate is likely 10–13%, with upside from Asia Pacific digital adoption and downside from insurance reimbursement constraints in elective procedures.
How is the market segmented?
The market segments primarily by product type, procedure category, age group, distribution channel, and end-user — with dental systems and equipment commanding the largest product share and orthodontic correction the largest procedure share.
Dental systems and equipment held 33.8% revenue share in 2022 per the primary estimate — a reflection of the capital-intensive nature of cosmetic dentistry. Orthodontic correction commanded roughly 32% of procedure share, while adults accounted for 82% of the patient base, underscoring the field's reliance on discretionary adult spending.
Which region leads in Cosmetic Dentistry Market?
North America leads the global cosmetic dentistry market with approximately 40% revenue share, driven by high aesthetic acceptance, advanced technology adoption, and dense DSO infrastructure — but Asia Pacific is closing the gap at a 13.8% CAGR.
Cosmetic Dentistry Market Regional Market Share
Loading chart...
Cosmetic Dentistry Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Europe
0.25%
Asia-Pacific
0.26%
Latin America
0.05%
Middle East & Africa
0.04%
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Region
Share (2022)
Growth Outlook
North America
40.0%
Mature; ~14.8% CAGR near-term
Europe
25.0%
Moderate; regulatory-driven amalgam shift
Asia Pacific
26.0%
Fastest at 13.8% CAGR
Latin America
5.0%
Emerging; dental tourism hub
Middle East & Africa
4.0%
Nascent; infrastructure-limited
Our analysis suggests North America's share will erode gradually through 2030 as Asia Pacific's middle-class expansion and dental tourism infrastructure mature. The key secondary effect: DSO consolidation in North America will drive equipment standardization, favoring vendors with integrated digital platforms over stand-alone product suppliers.
What is driving growth — and what is holding it back?
Growth is propelled by social-media-driven aesthetic demand, rising disposable incomes in developing economies, dental tourism, and rapid CAD/CAM and 3D-printing adoption — offset by limited insurance coverage for elective procedures and high capital requirements for digital equipment.
Factor
Direction
Evidence Strength
Mechanism
Social-media "Zoom-boom" visibility
Driver
High
+1.8% CAGR impact; 43% surge in elective inquiries
DTC clear-aligner platforms
Driver
High
+1.7% CAGR; $1,200–3,500 price points vs $3,000–8,000 in-office
Chairside CAD/CAM adoption by DSOs
Driver
High
+1.5% CAGR; 35–40% lab turnaround reduction
Cross-border dental tourism
Driver
Medium
+1.2% CAGR; >3M travelers in 2024
Limited insurance reimbursement
Restraint
High
–1.6% CAGR; highest impact in emerging markets
High CAD/CAM capital requirements
Restraint
Medium
–1.2% CAGR; acute in lower-income markets
Skilled technician shortage
Restraint
Medium
–0.9% CAGR; constrains digital workflow scaling
The balance of evidence favors net acceleration: driver impacts (+7.2% cumulative) outweigh restraint impacts (–4.4% cumulative) by a comfortable margin. However, the insurance reimbursement gap is the single most underappreciated structural risk — it caps elective procedure volume in price-sensitive markets and disproportionately affects independent practices lacking DSO bargaining power. Vendors targeting emerging markets must design financing models or subscription pricing to circumvent this constraint.
Who are the leading vendors?
The cosmetic dentistry vendor landscape is moderately concentrated, with Dentsply Sirona, Envista Holdings, Align Technology, Straumann Group, and Henry Schein leading across equipment, implants, aligners, and distribution.
Company
Primary Focus
Competitive Moat
Dentsply Sirona
Dental systems, implants, CAD/CAM
Broadest product portfolio; installed base lock-in
Premium implant reputation; European DTC expansion
Henry Schein
Distribution, equipment
Global distribution reach; practice-management integration
3M Oral Care
Bonding agents, restorative materials
Material science IP; clinician habit formation
Differentiation hinges on digital workflow integration — vendors offering end-to-end CAD/CAM, scanning, and treatment-planning ecosystems command premium pricing and higher switching costs. Align Technology's DTC aligner model represents the most disruptive competitive threat to traditional chairside orthodontics, though regulatory scrutiny of unsupervised aligner therapy (60% unmet expectations in one European cohort study) may temper its growth.
What do buyers and operators need to know?
Buyers evaluating cosmetic dentistry equipment or practice acquisitions must prioritize digital workflow interoperability over stand-alone product specs. CAD/CAM systems that integrate with existing intraoral scanners and practice-management software reduce per-unit lab fees by up to 60% and cut turnaround by 35–40% — but only if the ecosystem is cohesive. Fragmented purchases create hidden integration costs that erode ROI within 18–24 months.
Procurement risk is concentrated in capital equipment financing and technician availability. DSOs mitigate this by centralizing CAD/CAM milling hubs across multi-clinic networks; independents face acute capital barriers and should consider equipment-as-a-service or affiliation models. Switching costs are high once a digital ecosystem is embedded — clinicians resist retraining, and patient records are platform-specific.
Regulatory compliance varies by market: mercury amalgam phase-down regulations in Europe and North America are accelerating the shift to ceramic and composite materials, while emerging markets lag on material standards. Buyers should verify ISO 13485 certification for equipment vendors and confirm biocompatibility documentation for restorative materials. Insurance coding complexity for elective procedures remains a persistent operational friction — operators should model reimbursement scenarios conservatively.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderately bullish outlook: the 13.5% CAGR scenario is achievable, but only for vendors and operators positioned at the intersection of digital workflow and accessible financing. The strongest counter-argument — that insurance reimbursement constraints will cap elective demand — is valid but overstated; DTC aligner platforms have demonstrated that price innovation can unlock latent demand, and DSO consolidation is gradually improving reimbursement leverage.
Our analysis identifies three structural shifts that will define competitive advantage through 2030: (1) chairside CAD/CAM consolidation by DSOs will compress margins for stand-alone equipment vendors; (2) Asia Pacific's dental tourism infrastructure will create leapfrog adoption of minimally invasive techniques, bypassing legacy Western workflows; and (3) AI-driven treatment planning will shift value from hardware to software and data platforms, rewarding vendors with proprietary clinical datasets.
Actionable Strategy:
Equipment vendors should prioritize integrated CAD/CAM + scanning ecosystems and pursue DSO partnership models to lock in multi-clinic standardization contracts before competitors consolidate the channel.
Investors should target Asia Pacific DSO roll-ups and DTC aligner platforms with regulatory-compliant supervision models, avoiding stand-alone material suppliers vulnerable to commoditization.
Operators should adopt equipment-as-a-service or subscription financing to bypass capital barriers and model reimbursement scenarios conservatively for elective procedures.
The conclusion would change if insurance reimbursement expands to elective aesthetic procedures in major markets (accelerating volume beyond 15% CAGR) or if regulatory action restricts DTC aligner supervision models (slowing orthodontic segment growth below 6%).
Cosmetic Dentistry Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Cosmetic Dentistry Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 13.5% from 2020-2034
Segmentation
By Product
Dental Systems & Equipment
Dental Implants
Dental Crowns & Bridges
Dental Veneers
Orthodontic Braces
Bonding Agents
Inlays & Onlays
Whitening
By Procedure
Orthodontic Correction
Restorative Aesthetics
Esthetic Enhancement
Implantology
By Age Group
Adults
Teenagers
Geriatric
By Distribution Channel
Offline
Online
By End-User
Dental Clinics
Dental Hospitals
DSOs
Dental Laboratories
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Argentina
Colombia
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Cosmetic Dentistry Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Cosmetic Dentistry Market Executive Summary
2.1. Market Snapshot
3. Cosmetic Dentistry Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Cosmetic Dentistry Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Cosmetic Dentistry Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product
5.1.1. Dental Systems & Equipment
5.1.2. Dental Implants
5.1.3. Dental Crowns & Bridges
5.1.4. Dental Veneers
5.1.5. Orthodontic Braces
5.1.6. Bonding Agents
5.1.7. Inlays & Onlays
5.1.8. Whitening
5.2. Analysis, Insights and Forecast - by Procedure
5.2.1. Orthodontic Correction
5.2.2. Restorative Aesthetics
5.2.3. Esthetic Enhancement
5.2.4. Implantology
5.3. Analysis, Insights and Forecast - by Age Group
5.3.1. Adults
5.3.2. Teenagers
5.3.3. Geriatric
5.4. Analysis, Insights and Forecast - by Distribution Channel
5.4.1. Offline
5.4.2. Online
5.5. Analysis, Insights and Forecast - by End-User
5.5.1. Dental Clinics
5.5.2. Dental Hospitals
5.5.3. DSOs
5.5.4. Dental Laboratories
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Cosmetic Dentistry Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product
6.1.1. Dental Systems & Equipment
6.1.2. Dental Implants
6.1.3. Dental Crowns & Bridges
6.1.4. Dental Veneers
6.1.5. Orthodontic Braces
6.1.6. Bonding Agents
6.1.7. Inlays & Onlays
6.1.8. Whitening
6.2. Analysis, Insights and Forecast - by Procedure
6.2.1. Orthodontic Correction
6.2.2. Restorative Aesthetics
6.2.3. Esthetic Enhancement
6.2.4. Implantology
6.3. Analysis, Insights and Forecast - by Age Group
6.3.1. Adults
6.3.2. Teenagers
6.3.3. Geriatric
6.4. Analysis, Insights and Forecast - by Distribution Channel
6.4.1. Offline
6.4.2. Online
6.5. Analysis, Insights and Forecast - by End-User
6.5.1. Dental Clinics
6.5.2. Dental Hospitals
6.5.3. DSOs
6.5.4. Dental Laboratories
7. Cosmetic Dentistry Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product
7.1.1. Dental Systems & Equipment
7.1.2. Dental Implants
7.1.3. Dental Crowns & Bridges
7.1.4. Dental Veneers
7.1.5. Orthodontic Braces
7.1.6. Bonding Agents
7.1.7. Inlays & Onlays
7.1.8. Whitening
7.2. Analysis, Insights and Forecast - by Procedure
7.2.1. Orthodontic Correction
7.2.2. Restorative Aesthetics
7.2.3. Esthetic Enhancement
7.2.4. Implantology
7.3. Analysis, Insights and Forecast - by Age Group
7.3.1. Adults
7.3.2. Teenagers
7.3.3. Geriatric
7.4. Analysis, Insights and Forecast - by Distribution Channel
7.4.1. Offline
7.4.2. Online
7.5. Analysis, Insights and Forecast - by End-User
7.5.1. Dental Clinics
7.5.2. Dental Hospitals
7.5.3. DSOs
7.5.4. Dental Laboratories
8. Cosmetic Dentistry Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product
8.1.1. Dental Systems & Equipment
8.1.2. Dental Implants
8.1.3. Dental Crowns & Bridges
8.1.4. Dental Veneers
8.1.5. Orthodontic Braces
8.1.6. Bonding Agents
8.1.7. Inlays & Onlays
8.1.8. Whitening
8.2. Analysis, Insights and Forecast - by Procedure
8.2.1. Orthodontic Correction
8.2.2. Restorative Aesthetics
8.2.3. Esthetic Enhancement
8.2.4. Implantology
8.3. Analysis, Insights and Forecast - by Age Group
8.3.1. Adults
8.3.2. Teenagers
8.3.3. Geriatric
8.4. Analysis, Insights and Forecast - by Distribution Channel
8.4.1. Offline
8.4.2. Online
8.5. Analysis, Insights and Forecast - by End-User
8.5.1. Dental Clinics
8.5.2. Dental Hospitals
8.5.3. DSOs
8.5.4. Dental Laboratories
9. Cosmetic Dentistry Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product
9.1.1. Dental Systems & Equipment
9.1.2. Dental Implants
9.1.3. Dental Crowns & Bridges
9.1.4. Dental Veneers
9.1.5. Orthodontic Braces
9.1.6. Bonding Agents
9.1.7. Inlays & Onlays
9.1.8. Whitening
9.2. Analysis, Insights and Forecast - by Procedure
9.2.1. Orthodontic Correction
9.2.2. Restorative Aesthetics
9.2.3. Esthetic Enhancement
9.2.4. Implantology
9.3. Analysis, Insights and Forecast - by Age Group
9.3.1. Adults
9.3.2. Teenagers
9.3.3. Geriatric
9.4. Analysis, Insights and Forecast - by Distribution Channel
9.4.1. Offline
9.4.2. Online
9.5. Analysis, Insights and Forecast - by End-User
9.5.1. Dental Clinics
9.5.2. Dental Hospitals
9.5.3. DSOs
9.5.4. Dental Laboratories
10. Cosmetic Dentistry Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product
10.1.1. Dental Systems & Equipment
10.1.2. Dental Implants
10.1.3. Dental Crowns & Bridges
10.1.4. Dental Veneers
10.1.5. Orthodontic Braces
10.1.6. Bonding Agents
10.1.7. Inlays & Onlays
10.1.8. Whitening
10.2. Analysis, Insights and Forecast - by Procedure
10.2.1. Orthodontic Correction
10.2.2. Restorative Aesthetics
10.2.3. Esthetic Enhancement
10.2.4. Implantology
10.3. Analysis, Insights and Forecast - by Age Group
10.3.1. Adults
10.3.2. Teenagers
10.3.3. Geriatric
10.4. Analysis, Insights and Forecast - by Distribution Channel
10.4.1. Offline
10.4.2. Online
10.5. Analysis, Insights and Forecast - by End-User
Table 16: Europe Cosmetic Dentistry Market Revenue Billion Forecast, by Product 2020 & 2034
Frequently Asked Questions
1. How big is the cosmetic dentistry market?
The global cosmetic dentistry market was valued at $33.6 billion in 2022 and is projected to reach $89.0 billion by 2030, growing at a 13.5% CAGR. North America accounted for 40% of global revenue in 2022.
2. Which region is the fastest-growing in cosmetic dentistry?
Asia Pacific is the fastest-growing region at a 13.8% CAGR through 2030, driven by rising disposable incomes, dental tourism, and expanding clinic networks in China and India.
3. What is the largest product segment in cosmetic dentistry?
Dental systems and equipment held the largest product share at 33.8% in 2022, reflecting the capital-intensive nature of cosmetic dentistry and the shift toward digital workflows.
4. Who are the leading cosmetic dentistry companies?
Leading players include Dentsply Sirona, Align Technology, Envista Holdings, Straumann Group, Henry Schein, and 3M Oral Care, competing across equipment, implants, aligners, and distribution.
5. What is driving the cosmetic dentistry market growth?
Social-media-driven aesthetic demand, DTC clear-aligner affordability, CAD/CAM adoption by DSOs, and cross-border dental tourism are the primary growth drivers, collectively adding roughly 7 percentage points to CAGR.
6. What are the main restraints in the cosmetic dentistry market?
Limited insurance reimbursement for elective procedures, high capital requirements for CAD/CAM equipment, skilled technician shortages, and counterfeit product trust erosion are the primary restraints, collectively reducing CAGR by roughly 4.4 percentage points.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring that all market sizing, segmentation, and forecasting is grounded in direct industry validation. We conducted in-depth interviews with key stakeholders across the cosmetic dentistry value chain, including dental equipment manufacturers, implant and aligner producers, contract manufacturing organizations, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, each providing granular insight into procurement cycles, capacity constraints, and pricing dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
38%
Procurement & Sourcing Leads
32%
Commercial Operations Leads
18%
Regulatory Affairs Managers
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Dental Equipment & Device Manufacturers
40%
Implant & Aligner Producers
30%
Contract Manufacturers & Suppliers
18%
Global Distributors & DSOs
12%
Secondary Benchmarking & Public Trade Validation
Secondary research draws on official multilateral trade and standards databases — including UN Comtrade, WTO, US ITC, and Eurostat — alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards bodies such as ISO and the FDI World Dental Federation. These sources validate primary findings and anchor our market estimates in verifiable trade and regulatory data.
Demand Modeling & Market Sizing Triangulation
We apply simultaneous Top-Down and Bottom-Up data triangulation. The top-down model allocates macroeconomic and industry-segment expenditure across cosmetic dentistry categories, while the bottom-up model builds from manufacturer capacity, product pricing, and end-use consumption data. Convergence between the two approaches yields our final market size and forecast estimates.


 Cosmetic Dentistry Market