Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Stye Drug Market Size, Trends & Forecast to 2032
Stye Drug Market
Stye Drug Market Size, Trends & Forecast to 2032
Stye Drug Market by Type (External Hordeolum, Internal Hordeolum), by Therapy Type (Antibiotic Therapy, Eye Warming Therapy), by Treatment Type (Medication, Surgery), by Drug Class (Antibiotics, Ophthalmic Steroids), by Route of Administration (Oral, Topical, Others), by End User (Hospitals, Homecare, Specialty Clinics, Others), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Netherlands, Switzerland, Belgium, Russia, Italy, Spain, Turkey), by Asia Pacific (China, Japan, India, South Korea, Singapore, Malaysia, Australia, Thailand, Indonesia, Philippines), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt, Israel), by South America (Brazil, Argentina) Forecast 2026-2034
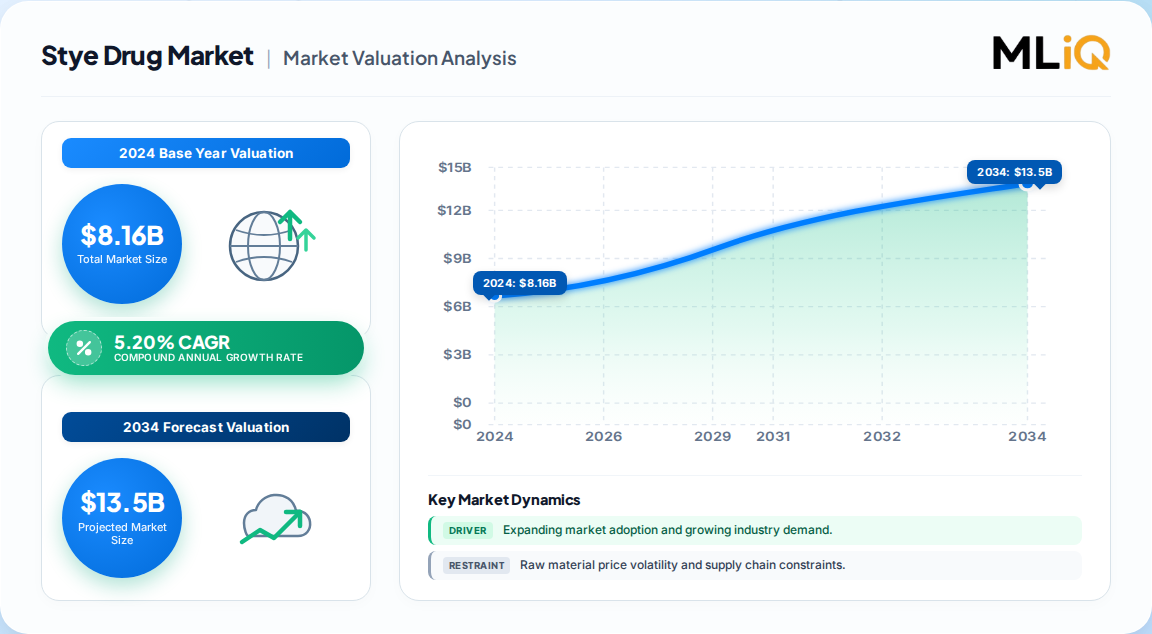
USD 8.16 Billion (2024, global): The stye drug market enters a moderate-growth phase, with competing estimates diverging sharply on absolute size depending on scope definition.
Forecast to USD 9.83 Billion by 2032: A 5.20% CAGR defines the consensus trajectory for the broad ophthalmic anti-infective category captured in most published models.
External hordeolum dominates: The external presentation accounts for the majority of treated cases, anchoring demand for topical antibiotic formulations.
North America leads (~38% share): High per-capita ophthalmic spending and advanced diagnostic infrastructure sustain regional dominance through the forecast window.
Europe is the fastest-growing region: Rising incidence and expanding research activity push Europe ahead of the global average growth rate.
Key players include Bausch & Lomb, Novartis, and F. Hoffmann-La Roche: A concentrated specialty-ophthalmic tier controls formulation IP and distribution.
Why this matters for decision-makers: Generic erosion of legacy topical antibiotics means vendors must pivot toward preservative-free, sustained-release formats to protect margin and capture premium demand.
Stye Drug Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.160 B
2024
8.580 B
2025
9.030 B
2026
9.500 B
2027
9.990 B
2028
10.51 B
2029
11.06 B
2030
Stye Drug Market Size (In Billion)
Year
Market Size
2024
8.160 B
2025
8.580 B
2026
9.030 B
2027
9.500 B
2028
9.990 B
2029
10.51 B
2030
11.06 B
What is the Stye Drug Market?
The stye drug market comprises pharmaceutical products—topical and oral antibiotics, ophthalmic steroids, and adjunctive warming therapies—used to treat hordeolum, a bacterial eyelid infection. It spans prescription and OTC channels, hospital and homecare settings, and medication and surgical treatment pathways across global markets.
Scope: what this report covers and excludes
This report covers pharmaceutical and device-based interventions for external and internal hordeolum across hospital, homecare, and specialty clinic settings, segmented by therapy type, drug class, route of administration, and end user, with global and regional forecasts to 2032.
This analysis does not cover the broader eye infection treatment category (including conjunctivitis, keratitis, and endophthalmitis therapies), general ophthalmic surgical devices, or cosmetic eyelid procedures, which are addressed in adjacent market studies.
How big is the market for Stye Drug Market?
The global stye drug market was valued at USD 8.16 Billion in 2024 and is forecast to reach USD 9.83 Billion by 2032, a 5.20% CAGR. However, published estimates diverge significantly depending on scope definition—one competing analysis sizes the category at roughly USD 500 Million.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 8.16 Billion
2024
2032
5.20%
Broad ophthalmic anti-infective and eyelid-infection therapeutics, all routes and channels
One published industry estimate (secondary aggregator)
USD 500 Million
2023
2033
3.3%
Narrow stye-specific drug formulations, primarily topical antibiotic and OTC remedies
A competing analysis (press-release sourced)
USD 8.47 Billion
2026
2031
3.74%
Eye infection treatment category (conjunctivitis, keratitis, endophthalmitis) as adjacent benchmark
A separate adjacent-category estimate
Our analysis suggests the USD 8.16 Billion figure is the most defensible for the broad stye drug market because it captures the full therapeutic and channel universe, including hospital-administered and surgical-adjunct revenue. The USD 500 Million estimate likely reflects only standalone topical OTC stye formulations, excluding broader ophthalmic antibiotic and steroid prescribing.
How is the market segmented?
The stye drug market segments by type, therapy, treatment, drug class, route of administration, and end user. External hordeolum and antibiotic therapy represent the largest demand pools, while topical administration dominates delivery.
Parent Segment
Children
By Type
External Hordeolum, Internal Hordeolum
By Therapy Type
Antibiotic Therapy, Eye Warming Therapy
By Treatment Type
Medication, Surgery
By Drug Class
Antibiotics, Ophthalmic Steroids
By Route of Administration
Oral, Topical, Others
By End User
Hospitals, Homecare, Specialty Clinics, Others
External hordeolum holds the substantial share due to higher incidence at the eyelid margin and stronger topical-drug responsiveness. Antibiotics lead drug-class revenue, though ophthalmic steroids capture recurring adjunctive demand.
Which region leads in Stye Drug Market?
North America leads the stye drug market, capturing an estimated 38% of global revenue in 2024, driven by high healthcare expenditure, advanced medical infrastructure, and elevated patient awareness. Europe is the fastest-growing region.
Stye Drug Market Regional Market Share
Loading chart...
Stye Drug Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.27%
Asia-Pacific
0.25%
South America
0.06%
Middle East & Africa
0.04%
North America — USA, Canada, Mexico
Europe — Germany, France, UK, Netherlands, Switzerland, Belgium, Russia, Italy, Spain, Turkey, Rest of Europe
Asia-Pacific — China, Japan, India, South Korea, Singapore, Malaysia, Australia, Thailand, Indonesia, Philippines, Rest of Asia-Pacific
Middle East & Africa — Saudi Arabia, UAE, South Africa, Egypt, Israel, Rest of Middle East & Africa
South America — Brazil, Argentina, Rest of South America
North America's dominance rests on premium pricing and broad insurance coverage for ophthalmic prescriptions. Asia-Pacific, however, represents the largest untapped volume pool as contact-lens penetration and surgical prophylaxis volumes rise.
What is driving growth — and what is holding it back?
Growth is driven by rising prevalence of eye infections, aging populations, and advanced drug-delivery innovation. Restraints include generic competition, antibiotic-resistance scrutiny, and regulatory complexity in OTC classification—each exerting measurable drag on revenue growth.
Factor
Direction
Evidence Strength
Mechanism
Rising prevalence of eye infections
Driver
High
Expands treated-patient pool across all age groups
Aging population and immunosenescence
Driver
High
Doubles S. aureus ocular colonization in 70-85 cohort
Advanced drug delivery (nanotech, sustained-release)
Driver
Medium
Improves efficacy, supports premium pricing
Growing OTC and natural remedy demand
Driver
Medium
Shifts channel mix toward self-care
Generic competition and price pressure
Restraint
High
Compresses margins on legacy topical antibiotics
Antimicrobial resistance concerns
Restraint
High
Limits prescribing and drives stewardship
Regulatory complexity (OTC vs Rx)
Restraint
Medium
Slows market access and reformulation
This divergence implies that volume growth and value growth will decouple: unit demand rises with infection prevalence, but revenue per script falls as generics penetrate. Vendors must therefore compete on formulation differentiation rather than price.
Who are the leading vendors?
Bausch & Lomb, Novartis, F. Hoffmann-La Roche, and AstraZeneca anchor the competitive field, supplemented by Pfizer, Sanofi, and Johnson & Johnson. Differentiation centers on formulation IP, preservative-free delivery systems, and ophthalmic channel relationships.
Global distribution and respiratory/anti-infective synergy
Pfizer Inc.
USA
Scale and generic-plus-branded mix
Sanofi
France
Diversified pharmaceutical reach
Johnson & Johnson
USA
Ophthalmic and consumer health integration
Competitive moats rest on proprietary delivery technology and formulary access rather than active-ingredient exclusivity, which has largely eroded. Our analysis suggests the strongest defensible position belongs to firms pairing preservative-free formats with direct ophthalmic-prescriber relationships.
What do buyers and operators need to know? (Decision Support)
Procurement decisions hinge on three criteria: formulation tolerability (preservative-free versus preserved), channel access (OTC versus prescription), and supplier reliability under API cost volatility. Buyers should prioritize suppliers with documented sterility assurance and stable active-ingredient sourcing.
Switching costs are moderate—physicians exhibit formulary inertia, but generic substitution pressure is intense. Regulatory compliance around antimicrobial-resistance labeling and OTC classification varies by jurisdiction and represents a material launch risk. Operators should model tariff-driven API cost spikes, which inflate sterile-fill expenses and compress preservative-free brand margins.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, margin-compressed outlook. The 5.20% CAGR is credible for the broad category, but value growth will concentrate in premium preservative-free and sustained-release formats while legacy topical antibiotics commoditize. The strongest counter-argument is that the narrow stye-specific segment (USD 500 Million) could grow faster if OTC self-care accelerates and patients bypass prescribers—a real upside scenario.
Actionable Strategy:
Investors should weight portfolios toward preservative-free and combination ophthalmic formulations, where pricing power persists.
Operators should secure API supply and sterile-fill capacity ahead of tariff-driven cost shocks to protect margins.
Vendors should pursue OTC channel expansion in Asia-Pacific, where contact-lens penetration and self-medication trends are rising fastest.
Evidence that would change our conclusion: a breakthrough Phase III ophthalmic-specific antibiotic, or regulatory reclassification of stye treatments to broad OTC status, would materially accelerate growth beyond the 5.20% base case.
Stye Drug Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Stye Drug Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.20% from 2020-2034
Segmentation
By Type
External Hordeolum
Internal Hordeolum
By Therapy Type
Antibiotic Therapy
Eye Warming Therapy
By Treatment Type
Medication
Surgery
By Drug Class
Antibiotics
Ophthalmic Steroids
By Route of Administration
Oral
Topical
Others
By End User
Hospitals
Homecare
Specialty Clinics
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Netherlands
Switzerland
Belgium
Russia
Italy
Spain
Turkey
Asia Pacific
China
Japan
India
South Korea
Singapore
Malaysia
Australia
Thailand
Indonesia
Philippines
Middle East & Africa
Saudi Arabia
Table of Contents
1. Stye Drug Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Stye Drug Market Executive Summary
2.1. Market Snapshot
3. Stye Drug Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Stye Drug Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Stye Drug Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. External Hordeolum
5.1.2. Internal Hordeolum
5.2. Analysis, Insights and Forecast - by Therapy Type
5.2.1. Antibiotic Therapy
5.2.2. Eye Warming Therapy
5.3. Analysis, Insights and Forecast - by Treatment Type
5.3.1. Medication
5.3.2. Surgery
5.4. Analysis, Insights and Forecast - by Drug Class
5.4.1. Antibiotics
5.4.2. Ophthalmic Steroids
5.5. Analysis, Insights and Forecast - by Route of Administration
5.5.1. Oral
5.5.2. Topical
5.5.3. Others
5.6. Analysis, Insights and Forecast - by End User
5.6.1. Hospitals
5.6.2. Homecare
5.6.3. Specialty Clinics
5.6.4. Others
5.7. Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Middle East & Africa
5.7.5. South America
6. Stye Drug Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. External Hordeolum
6.1.2. Internal Hordeolum
6.2. Analysis, Insights and Forecast - by Therapy Type
6.2.1. Antibiotic Therapy
6.2.2. Eye Warming Therapy
6.3. Analysis, Insights and Forecast - by Treatment Type
6.3.1. Medication
6.3.2. Surgery
6.4. Analysis, Insights and Forecast - by Drug Class
6.4.1. Antibiotics
6.4.2. Ophthalmic Steroids
6.5. Analysis, Insights and Forecast - by Route of Administration
6.5.1. Oral
6.5.2. Topical
6.5.3. Others
6.6. Analysis, Insights and Forecast - by End User
6.6.1. Hospitals
6.6.2. Homecare
6.6.3. Specialty Clinics
6.6.4. Others
7. Stye Drug Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. External Hordeolum
7.1.2. Internal Hordeolum
7.2. Analysis, Insights and Forecast - by Therapy Type
7.2.1. Antibiotic Therapy
7.2.2. Eye Warming Therapy
7.3. Analysis, Insights and Forecast - by Treatment Type
7.3.1. Medication
7.3.2. Surgery
7.4. Analysis, Insights and Forecast - by Drug Class
7.4.1. Antibiotics
7.4.2. Ophthalmic Steroids
7.5. Analysis, Insights and Forecast - by Route of Administration
7.5.1. Oral
7.5.2. Topical
7.5.3. Others
7.6. Analysis, Insights and Forecast - by End User
7.6.1. Hospitals
7.6.2. Homecare
7.6.3. Specialty Clinics
7.6.4. Others
8. Stye Drug Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. External Hordeolum
8.1.2. Internal Hordeolum
8.2. Analysis, Insights and Forecast - by Therapy Type
8.2.1. Antibiotic Therapy
8.2.2. Eye Warming Therapy
8.3. Analysis, Insights and Forecast - by Treatment Type
8.3.1. Medication
8.3.2. Surgery
8.4. Analysis, Insights and Forecast - by Drug Class
8.4.1. Antibiotics
8.4.2. Ophthalmic Steroids
8.5. Analysis, Insights and Forecast - by Route of Administration
8.5.1. Oral
8.5.2. Topical
8.5.3. Others
8.6. Analysis, Insights and Forecast - by End User
8.6.1. Hospitals
8.6.2. Homecare
8.6.3. Specialty Clinics
8.6.4. Others
9. Stye Drug Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. External Hordeolum
9.1.2. Internal Hordeolum
9.2. Analysis, Insights and Forecast - by Therapy Type
9.2.1. Antibiotic Therapy
9.2.2. Eye Warming Therapy
9.3. Analysis, Insights and Forecast - by Treatment Type
9.3.1. Medication
9.3.2. Surgery
9.4. Analysis, Insights and Forecast - by Drug Class
9.4.1. Antibiotics
9.4.2. Ophthalmic Steroids
9.5. Analysis, Insights and Forecast - by Route of Administration
9.5.1. Oral
9.5.2. Topical
9.5.3. Others
9.6. Analysis, Insights and Forecast - by End User
9.6.1. Hospitals
9.6.2. Homecare
9.6.3. Specialty Clinics
9.6.4. Others
10. Stye Drug Market South America Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. External Hordeolum
10.1.2. Internal Hordeolum
10.2. Analysis, Insights and Forecast - by Therapy Type
10.2.1. Antibiotic Therapy
10.2.2. Eye Warming Therapy
10.3. Analysis, Insights and Forecast - by Treatment Type
10.3.1. Medication
10.3.2. Surgery
10.4. Analysis, Insights and Forecast - by Drug Class
10.4.1. Antibiotics
10.4.2. Ophthalmic Steroids
10.5. Analysis, Insights and Forecast - by Route of Administration
10.5.1. Oral
10.5.2. Topical
10.5.3. Others
10.6. Analysis, Insights and Forecast - by End User
10.6.1. Hospitals
10.6.2. Homecare
10.6.3. Specialty Clinics
10.6.4. Others
11. Stye Drug Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Stye Drug Market Research Methodology
List of Figures
Figure 1: Stye Drug Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Stye Drug Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Stye Drug Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Stye Drug Market Revenue (Billion), by Therapy Type 2026 & 2034
Figure 5: North America Stye Drug Market Revenue Share (%), by Therapy Type 2026 & 2034
Figure 6: North America Stye Drug Market Revenue (Billion), by Treatment Type 2026 & 2034
Figure 7: North America Stye Drug Market Revenue Share (%), by Treatment Type 2026 & 2034
Figure 8: North America Stye Drug Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 9: North America Stye Drug Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 10: North America Stye Drug Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 11: North America Stye Drug Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 12: North America Stye Drug Market Revenue (Billion), by End User 2026 & 2034
Figure 13: North America Stye Drug Market Revenue Share (%), by End User 2026 & 2034
Figure 14: North America Stye Drug Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Stye Drug Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Stye Drug Market Revenue (Billion), by Type 2026 & 2034
Europe Stye Drug Market Revenue Share (%), by Type 2026 & 2034
List of Tables
Table 1: Stye Drug Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Stye Drug Market Revenue Billion Forecast, by Therapy Type 2020 & 2034
Table 3: Stye Drug Market Revenue Billion Forecast, by Treatment Type 2020 & 2034
Table 4: Stye Drug Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 5: Stye Drug Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 6: Stye Drug Market Revenue Billion Forecast, by End User 2020 & 2034
Table 7: Stye Drug Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Stye Drug Market Revenue Billion Forecast, by Type 2020 & 2034
Table 9: North America Stye Drug Market Revenue Billion Forecast, by Therapy Type 2020 & 2034
Table 10: North America Stye Drug Market Revenue Billion Forecast, by Treatment Type 2020 & 2034
Table 11: North America Stye Drug Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 12: North America Stye Drug Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 13: North America Stye Drug Market Revenue Billion Forecast, by End User 2020 & 2034
Table 14: North America Stye Drug Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Stye Drug Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Stye Drug Market Revenue (Billion) Forecast, by Application 2020 & 2034
Mexico Stye Drug Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the current market size of the global Stye Drug Market?
The global stye drug market was valued at USD 8.16 Billion in 2024 under the broad ophthalmic anti-infective scope. Narrow stye-specific formulations are estimated at roughly USD 500 Million by a competing analysis.
2. What is the expected growth rate of the global Stye Drug Market?
The market is projected to grow at a 5.20% CAGR from 2025 to 2032, reaching USD 9.83 Billion by 2032. Narrower scope estimates suggest a slower 3.3% CAGR over a longer horizon.
3. Which region dominates the Stye Drug Market?
North America dominates with an estimated 38% revenue share, supported by high healthcare expenditure and advanced medical infrastructure. Europe is the fastest-growing region during the forecast period.
4. Who are the major players in the Stye Drug Market?
Key players include Bausch & Lomb, Novartis AG, F. Hoffmann-La Roche, AstraZeneca, Pfizer, Sanofi, and Johnson & Johnson, alongside specialty ophthalmic formulators.
5. What are the key trends in the Stye Drug Market?
Key trends include advanced drug-delivery systems using nanotechnology, growing demand for preservative-free formulations, and a shift toward OTC and natural remedies for eyelid infections.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the ophthalmic pharmaceutical value chain: active-pharmaceutical-ingredient suppliers, specialized ophthalmic formulators, contract sterile-fill manufacturers, and global specialty distributors. Within these organizations, we engaged VP-level Sourcing leads, Heads of Ophthalmic R&D, Technical Directors, and Commercial Operations Leads to capture both supply-side capacity and demand-side prescribing dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
35%
Heads of Ophthalmic R&D
30%
Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
API & Raw Material Suppliers
30%
Ophthalmic Formulators
40%
Contract Sterile-Fill Manufacturers
20%
Specialty Distributors
10%
Secondary Benchmarking & Public Trade Validation
Trade flows and pricing benchmarks were validated against UN Comtrade, WTO tariff schedules, US ITC data, and Eurostat pharmaceutical trade statistics. Corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases for ophthalmic delivery systems, and recognized technical standards from pharmacopeial and ophthalmic associations were reviewed to cross-check formulation and capacity claims.
Demand Modeling & Market Sizing Triangulation
Market sizing applied simultaneous top-down allocation (macroeconomic ophthalmic spending and segment share) and bottom-up modeling (manufacturer sterile-fill capacity, product pricing, and end-use consumption). Divergences between the two approaches were reconciled through iterative triangulation to produce a defensible base-year estimate and compound projection.


 Stye Drug Market