Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Water Treatment Equipment Market Outlook 2026
Water Treatment Equipment Market
Water Treatment Equipment Market Outlook 2026
Water Treatment Equipment Market by Equipment Type (Filtration Equipment, Membrane Equipment, Disinfection Equipment, Sedimentation & Clarification, Biological Treatment, Thermal Distillation & Evaporators, Sludge Treatment), by Process Stage (Primary, Secondary, Tertiary), by Application (Municipal, Industrial, Commercial, Residential), by Component (Pumps, Valves, Filters & Clarifiers, Drives, Motors & Generators, Automation & Monitoring), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy, Spain), by Asia Pacific (China, India, Japan, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 286
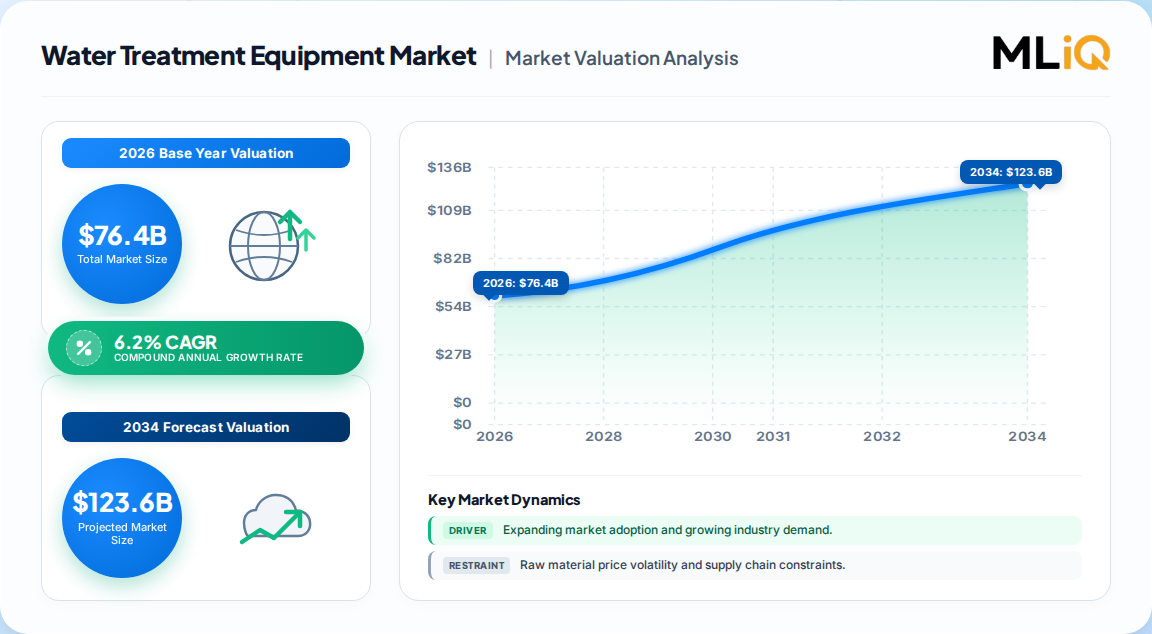
USD 76.4 billion is the estimated 2026 global water treatment equipment market size, up from USD 72.5 billion in 2025, per one published estimate.
6.2% CAGR is the consensus 2026–2035 expansion rate, carrying the market to roughly USD 131.7 billion by 2035.
Asia Pacific is both the largest and fastest-growing region, with China, India, Japan and South Korea driving municipal and industrial capacity build-out.
Membrane and filtration equipment represent the largest and highest-growth equipment blocks, with each adding roughly USD 3 billion of incremental wastewater revenue to 2030.
Xylem, Pentair, Veolia, SUEZ and DuPont collectively hold about 38% of the market; Xylem alone exceeded 8% in 2025.
Decentralized, modular and reuse-oriented systems are the structural demand shift, rewarding vendors with service, automation and commissioning capability.
Why this matters for decision-makers: Vendors competing on equipment price alone will face margin compression; the defensible position is lifecycle service, membrane performance and compliance assurance bundled with the asset.
Water Treatment Equipment Market Size (In Billion)
150.0B
100.0B
50.0B
0
72.50 B
2025
76.40 B
2026
81.10 B
2027
86.20 B
2028
91.50 B
2029
97.20 B
2030
103.2 B
2031
Water Treatment Equipment Market Size (In Billion)
Year
Market Size
2025
72.50 B
2026
76.40 B
2027
81.10 B
2028
86.20 B
2029
91.50 B
2030
97.20 B
2031
103.2 B
What is the Water Treatment Equipment Market?
The water treatment equipment market covers the physical systems—filtration, membrane, disinfection, sedimentation, biological and thermal—that remove contaminants from drinking water, process water and wastewater before discharge or reuse. It spans residential, municipal, commercial and industrial deployments. Value is measured at equipment level, excluding chemicals, EPC services and utility operations.
Scope: what this report covers and excludes
This analysis covers global water and wastewater treatment equipment by product type, process stage, application and region, with a 2025 base year and forecast to 2035. It includes capital equipment, modular trains and associated controls. This analysis does not cover treatment chemicals, membranes as standalone consumables sold aftermarket, engineering and construction services, bottled water, or desalination plant ownership and operations.
How big is the market for Water Treatment Equipment Market?
Estimates converge on a low-to-mid USD 70 billion base in 2025, but the forecast spreads are wide because definitions differ on whether wastewater treatment equipment is counted inside or outside the broader water treatment equipment envelope.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
USD 72.5 B → 131.7 B
2025
2035
6.2%
Broad water treatment equipment, all applications
One published estimate
USD 70.28 B → 92.59 B
2025
2034
3.11%
Wastewater treatment equipment, component-level
A competing analysis
USD 34.69 B → 44.59 B
2025
2030
5.2%
Wastewater equipment only, equipment classes
A third published estimate
Our analysis suggests the USD 72.5 billion base is the most defensible anchor for total-address-market work, because it reconciles drinking water, industrial process water and wastewater in one envelope. The lower USD 34.7–70.3 billion figures are wastewater-only slices, not contradictory readings. Buyers sizing a wastewater-specific opportunity should use the narrower baseline and layer the membrane and filtration increments.
How is the market segmented?
Segmentation runs along four axes—equipment type, treatment process stage, end-use application and component—and the mix shifts materially with feedwater quality and discharge rules.
Sedimentation tanks alone accounted for USD 5.8 billion in 2025 and are forecast to reach USD 10.54 billion by 2035, confirming that conventional pretreatment remains commercially foundational even as membrane adoption rises. Biological equipment is the fastest-growing block as nutrient-removal mandates tighten.
Which region leads in Water Treatment Equipment Market?
Asia Pacific leads, holding an estimated 36–40% of global value in 2025, and is also the fastest-growing region at roughly 3.6–4.2% in the narrower wastewater definition and materially higher in the broad definition.
Water Treatment Equipment Market Regional Market Share
Loading chart...
Water Treatment Equipment Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.38%
North America
0.26%
Europe
0.24%
Latin America
0.06%
Middle East & Africa
0.06%
Global
Asia Pacific — China, India, Japan, South Korea, Australia
North America — USA, Canada, Mexico
Europe — Germany, France, UK, Italy, Spain
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
North America holds an estimated 26% share, with the U.S. representing 76–80% of that regional total, driven by replacement demand and reuse programs. Europe sits near 24%, led by Germany, France and the UK under tight discharge rules. The divergence implies that growth capital and replacement capital are flowing to different regions: Asia Pacific for greenfield capacity, North America and Europe for retrofit and compliance upgrades.
What is driving growth — and what is holding it back?
Tightening water quality and discharge regulation is the single largest growth mechanism, contributing roughly 1.7 percentage points of the forecast CAGR, followed by demand for safe drinking and process water at about 1.25 points.
Rising demand for safe drinking and industrial process water
Driver
High
Expands addressable market beyond greenfield municipal builds
Membrane and filtration technology advances
Driver
Medium-High
Enables reuse, high-purity output and compact layouts
Water scarcity and reuse mandates
Driver
High
Converts wastewater into a supply asset, justifies advanced treatment
High capital and operating cost of advanced systems
Restraint
Medium-High
Energy, membrane replacement and cleaning raise total cost of ownership
Technical complexity and skilled labor shortage
Restraint
Medium
Fouling and calibration risk reduce realized performance
Infrastructure and financing constraints
Restraint
Medium
Delays deployment in emerging markets, shifts to phased packages
The balance favors growth, but the restraints explain why adoption is uneven. Advanced systems win where the cost of non-compliance, downtime or water disposal exceeds the incremental treatment cost. Where that arithmetic fails, robust lower-complexity equipment retains share—and suppliers with remote monitoring convert the skills gap into a service moat.
Who are the leading vendors?
The top five vendors—Xylem, Pentair, Veolia Water Technologies, SUEZ and DuPont—collectively held about 38% of 2025 market value, indicating a moderately consolidated but still fragmented competitive field.
Company
Position
Strategic strength
Xylem Inc.
Market leader, >8% share 2025
Broad pump-to-analytics portfolio, digital monitoring, municipal installed base
Veolia Water Technologies
Top-tier integrated player
Full treatment train engineering, operations and concession capability
SUEZ SA
Top-tier integrated player
Municipal and industrial water cycle, reuse and sludge valorization
Pentair plc
Top-tier equipment specialist
Residential, commercial and filtration systems, distribution reach
DuPont
Membrane technology leader
RO, UF and NF membrane performance and materials IP
Ecolab, Kurita, Aquatech, Siemens, Thermax
Challengers and specialists
Industrial water, zero-liquid-discharge, automation and thermal niches
Differentiation has shifted from nameplate capacity to repeatable output. Vendors that bundle commissioning, consumables, remote monitoring and operator support are better positioned than those competing on initial equipment price, because the buyer's real risk is compliance continuity rather than capital cost alone.
What do buyers and operators need to know?
Selection should be driven by feedwater variability, not by catalog specification. A system rated for clean surface water will underperform on variable turbidity or high silica feed without adequate pretreatment, and the resulting fouling cost lands on the operator, not the vendor.
Procurement risk concentrates in three areas: total cost of ownership, commissioning risk and skills dependency. Energy, membrane replacement, chemical cleaning and concentrate handling can exceed the original capital outlay over the asset life, so lifecycle modeling should be mandatory in tender evaluation.
Switching costs are high once a treatment train is installed—controls, spares and service contracts are typically vendor-specific—so buyers should negotiate data access and interoperability at award, not after commissioning. Regulatory compliance also increasingly requires continuous demonstration rather than periodic sampling, which raises the value of instrumentation and audit-ready reporting. Our analysis suggests operators should score vendors on service coverage density and remote diagnostics as heavily as on membrane flux or recovery rates.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-single-digit growth market with a quality-of-growth story rather than a volume story. The 6.2% headline and the 3.1–5.2% narrower readings are reconcilable: the broad envelope grows faster because reuse, high-purity industrial water and decentralized systems are additive to traditional municipal demand. Investors should treat the spread as a definitional signal, not a contradiction.
The strongest counter-argument is that capital cost and skills shortages will cap advanced adoption in emerging markets, pushing growth toward low-complexity, standardized packages rather than membrane-intensive trains. That is credible in parts of Latin America, MEA and emerging Asia, but it argues for a different product mix, not a smaller market.
Actionable strategy:
Equipment vendors should attach service, consumables and remote monitoring contracts at the point of sale to defend margin against commoditizing hardware.
Industrial buyers should model ten-year total cost of ownership—including energy, membrane replacement and cleaning—before award, not capital price alone.
Investors should weight exposure toward membrane, biological nutrient removal and digital monitoring, where regulatory drivers are strongest and pricing power is most durable.
What would change this conclusion: a sustained fall in membrane and energy costs would accelerate advanced adoption into cost-constrained markets; conversely, a rollback of discharge regulation in major economies would compress the compliance-driven premium faster than the base-case forecast implies. Precise sub-segment forecasting by equipment class and country requires the full dataset beyond this overview.
Water Treatment Equipment Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Water Treatment Equipment Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.2% from 2020-2034
Segmentation
By Equipment Type
Filtration Equipment
Membrane Equipment
Disinfection Equipment
Sedimentation & Clarification
Biological Treatment
Thermal Distillation & Evaporators
Sludge Treatment
By Process Stage
Primary
Secondary
Tertiary
By Application
Municipal
Industrial
Commercial
Residential
By Component
Pumps
Valves
Filters & Clarifiers
Drives
Motors & Generators
Automation & Monitoring
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Italy
Spain
Asia Pacific
China
India
Japan
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Water Treatment Equipment Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Water Treatment Equipment Market Executive Summary
2.1. Market Snapshot
3. Water Treatment Equipment Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Water Treatment Equipment Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Water Treatment Equipment Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Equipment Type
5.1.1. Filtration Equipment
5.1.2. Membrane Equipment
5.1.3. Disinfection Equipment
5.1.4. Sedimentation & Clarification
5.1.5. Biological Treatment
5.1.6. Thermal Distillation & Evaporators
5.1.7. Sludge Treatment
5.2. Analysis, Insights and Forecast - by Process Stage
5.2.1. Primary
5.2.2. Secondary
5.2.3. Tertiary
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Municipal
5.3.2. Industrial
5.3.3. Commercial
5.3.4. Residential
5.4. Analysis, Insights and Forecast - by Component
5.4.1. Pumps
5.4.2. Valves
5.4.3. Filters & Clarifiers
5.4.4. Drives
5.4.5. Motors & Generators
5.4.6. Automation & Monitoring
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Water Treatment Equipment Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Equipment Type
6.1.1. Filtration Equipment
6.1.2. Membrane Equipment
6.1.3. Disinfection Equipment
6.1.4. Sedimentation & Clarification
6.1.5. Biological Treatment
6.1.6. Thermal Distillation & Evaporators
6.1.7. Sludge Treatment
6.2. Analysis, Insights and Forecast - by Process Stage
6.2.1. Primary
6.2.2. Secondary
6.2.3. Tertiary
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Municipal
6.3.2. Industrial
6.3.3. Commercial
6.3.4. Residential
6.4. Analysis, Insights and Forecast - by Component
6.4.1. Pumps
6.4.2. Valves
6.4.3. Filters & Clarifiers
6.4.4. Drives
6.4.5. Motors & Generators
6.4.6. Automation & Monitoring
7. Water Treatment Equipment Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Equipment Type
7.1.1. Filtration Equipment
7.1.2. Membrane Equipment
7.1.3. Disinfection Equipment
7.1.4. Sedimentation & Clarification
7.1.5. Biological Treatment
7.1.6. Thermal Distillation & Evaporators
7.1.7. Sludge Treatment
7.2. Analysis, Insights and Forecast - by Process Stage
7.2.1. Primary
7.2.2. Secondary
7.2.3. Tertiary
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Municipal
7.3.2. Industrial
7.3.3. Commercial
7.3.4. Residential
7.4. Analysis, Insights and Forecast - by Component
7.4.1. Pumps
7.4.2. Valves
7.4.3. Filters & Clarifiers
7.4.4. Drives
7.4.5. Motors & Generators
7.4.6. Automation & Monitoring
8. Water Treatment Equipment Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Equipment Type
8.1.1. Filtration Equipment
8.1.2. Membrane Equipment
8.1.3. Disinfection Equipment
8.1.4. Sedimentation & Clarification
8.1.5. Biological Treatment
8.1.6. Thermal Distillation & Evaporators
8.1.7. Sludge Treatment
8.2. Analysis, Insights and Forecast - by Process Stage
8.2.1. Primary
8.2.2. Secondary
8.2.3. Tertiary
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Municipal
8.3.2. Industrial
8.3.3. Commercial
8.3.4. Residential
8.4. Analysis, Insights and Forecast - by Component
8.4.1. Pumps
8.4.2. Valves
8.4.3. Filters & Clarifiers
8.4.4. Drives
8.4.5. Motors & Generators
8.4.6. Automation & Monitoring
9. Water Treatment Equipment Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Equipment Type
9.1.1. Filtration Equipment
9.1.2. Membrane Equipment
9.1.3. Disinfection Equipment
9.1.4. Sedimentation & Clarification
9.1.5. Biological Treatment
9.1.6. Thermal Distillation & Evaporators
9.1.7. Sludge Treatment
9.2. Analysis, Insights and Forecast - by Process Stage
9.2.1. Primary
9.2.2. Secondary
9.2.3. Tertiary
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Municipal
9.3.2. Industrial
9.3.3. Commercial
9.3.4. Residential
9.4. Analysis, Insights and Forecast - by Component
9.4.1. Pumps
9.4.2. Valves
9.4.3. Filters & Clarifiers
9.4.4. Drives
9.4.5. Motors & Generators
9.4.6. Automation & Monitoring
10. Water Treatment Equipment Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Equipment Type
10.1.1. Filtration Equipment
10.1.2. Membrane Equipment
10.1.3. Disinfection Equipment
10.1.4. Sedimentation & Clarification
10.1.5. Biological Treatment
10.1.6. Thermal Distillation & Evaporators
10.1.7. Sludge Treatment
10.2. Analysis, Insights and Forecast - by Process Stage
10.2.1. Primary
10.2.2. Secondary
10.2.3. Tertiary
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Municipal
10.3.2. Industrial
10.3.3. Commercial
10.3.4. Residential
10.4. Analysis, Insights and Forecast - by Component
10.4.1. Pumps
10.4.2. Valves
10.4.3. Filters & Clarifiers
10.4.4. Drives
10.4.5. Motors & Generators
10.4.6. Automation & Monitoring
11. Water Treatment Equipment Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Water Treatment Equipment Market Research Methodology
List of Figures
Figure 1: Water Treatment Equipment Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Water Treatment Equipment Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 3: North America Water Treatment Equipment Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 4: North America Water Treatment Equipment Market Revenue (Billion), by Process Stage 2026 & 2034
Figure 5: North America Water Treatment Equipment Market Revenue Share (%), by Process Stage 2026 & 2034
Figure 6: North America Water Treatment Equipment Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Water Treatment Equipment Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Water Treatment Equipment Market Revenue (Billion), by Component 2026 & 2034
Figure 9: North America Water Treatment Equipment Market Revenue Share (%), by Component 2026 & 2034
Figure 10: North America Water Treatment Equipment Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Water Treatment Equipment Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Water Treatment Equipment Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 13: Europe Water Treatment Equipment Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 14: Europe Water Treatment Equipment Market Revenue (Billion), by Process Stage 2026 & 2034
Figure 15: Europe Water Treatment Equipment Market Revenue Share (%), by Process Stage 2026 & 2034
Europe Water Treatment Equipment Market Revenue (Billion), by Application 2026 & 2034
List of Tables
Table 1: Water Treatment Equipment Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 2: Water Treatment Equipment Market Revenue Billion Forecast, by Process Stage 2020 & 2034
Table 3: Water Treatment Equipment Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Water Treatment Equipment Market Revenue Billion Forecast, by Component 2020 & 2034
Table 5: Water Treatment Equipment Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Water Treatment Equipment Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 7: North America Water Treatment Equipment Market Revenue Billion Forecast, by Process Stage 2020 & 2034
Table 8: North America Water Treatment Equipment Market Revenue Billion Forecast, by Application 2020 & 2034
Table 9: North America Water Treatment Equipment Market Revenue Billion Forecast, by Component 2020 & 2034
Table 10: North America Water Treatment Equipment Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Water Treatment Equipment Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Water Treatment Equipment Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Water Treatment Equipment Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Water Treatment Equipment Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 15: Europe Water Treatment Equipment Market Revenue Billion Forecast, by Process Stage 2020 & 2034
Frequently Asked Questions
1. How big is the water treatment equipment market in 2026?
The global water treatment equipment market is estimated at USD 76.4 billion in 2026, up from USD 72.5 billion in 2025. Broader definitions that include all drinking, process and wastewater equipment support this figure; narrower wastewater-only estimates are considerably lower.
2. What is the water treatment equipment market growth rate?
The consensus forecast CAGR is 6.2% for 2026 to 2035, reaching roughly USD 131.7 billion by 2035. Narrower wastewater-only definitions produce lower rates of 3.1% to 5.2%, reflecting different scope boundaries rather than conflicting demand signals.
3. Which region dominates water treatment equipment demand?
Asia Pacific is the largest and fastest-growing region, holding roughly 36–40% of global value. North America follows at about 26%, driven by replacement and reuse investment, with Europe near 24% under strict discharge regulation.
4. Who are the leading water treatment equipment companies?
Xylem leads with over 8% share in 2025. Xylem, Pentair, Veolia Water Technologies, SUEZ and DuPont together hold about 38% of the market, with Ecolab, Kurita, Aquatech, Siemens and Thermax competing in specialist industrial niches.
5. What equipment segment is growing fastest?
Biological treatment equipment is the fastest-growing block as nutrient removal requirements expand, while membrane and filtration equipment each add roughly USD 3 billion of incremental wastewater revenue to 2030. Sedimentation remains foundational for pretreatment at USD 5.8 billion in 2025.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with membrane and filter media producers, pump and valve manufacturers, skid and modular treatment packagers, and global industrial distributors. Respondents were designated at decision-maker level, including Vice Presidents of Sourcing, Heads of R&D and Product Engineering, Technical Directors, and Commercial Operations Leads. Interviews probed procurement criteria, total cost of ownership assumptions, replacement cycles and commissioning risk.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Technical & Engineering Directors
38%
Procurement & Sourcing Leads
32%
Plant Operations Managers
18%
Regulatory & Compliance Leads
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Equipment & Component Manufacturers
42%
Membrane & Filtration Producers
28%
Integrators & Modular Packagers
18%
Distributors & Service Providers
12%
Secondary Benchmarking & Public Trade Validation
Findings were benchmarked against UN Comtrade and WITS bilateral trade flows, WTO tariff schedules, US ITC and Eurostat trade statistics, corporate 10-K and annual investor filings, patent databases, and technical standards published by ISO and recognized water industry associations. Municipal capital improvement plans and utility rate filings supplemented demand validation.
Demand Modeling & Market Sizing Triangulation
Top-down allocation from macroeconomic and municipal/industrial capital expenditure benchmarks was run simultaneously with bottom-up modeling of manufacturer capacity, equipment pricing and end-use consumption by application. Divergences between the two approaches were reconciled at segment and regional level before forecast finalization.


 Water Treatment Equipment Market