Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Physical Vapor Deposition Coatings Industry Market 2026
Physical Vapor Deposition Coatings Industry
Physical Vapor Deposition Coatings Industry Market 2026
Physical Vapor Deposition Coatings Industry by Process Type (Sputter Deposition, Thermal/E-Beam Evaporation, Arc Vapor Deposition, HiPIMS, Others), by Substrate (Metals, Plastics, Glass, Ceramics), by Material Type (Metals, Ceramics and Oxides, DLC and Nitride Superlattices, Others), by End User (Tools and Components, Semiconductor and Electronics, Medical Devices, Automotive, Aerospace, Optics, Solar), by Asia Pacific (China, Japan, South Korea, Taiwan, India, Southeast Asia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Rest of Europe), by Middle East & Africa (Saudi Arabia, UAE, South Africa), by South America (Brazil, Argentina, Colombia) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 234
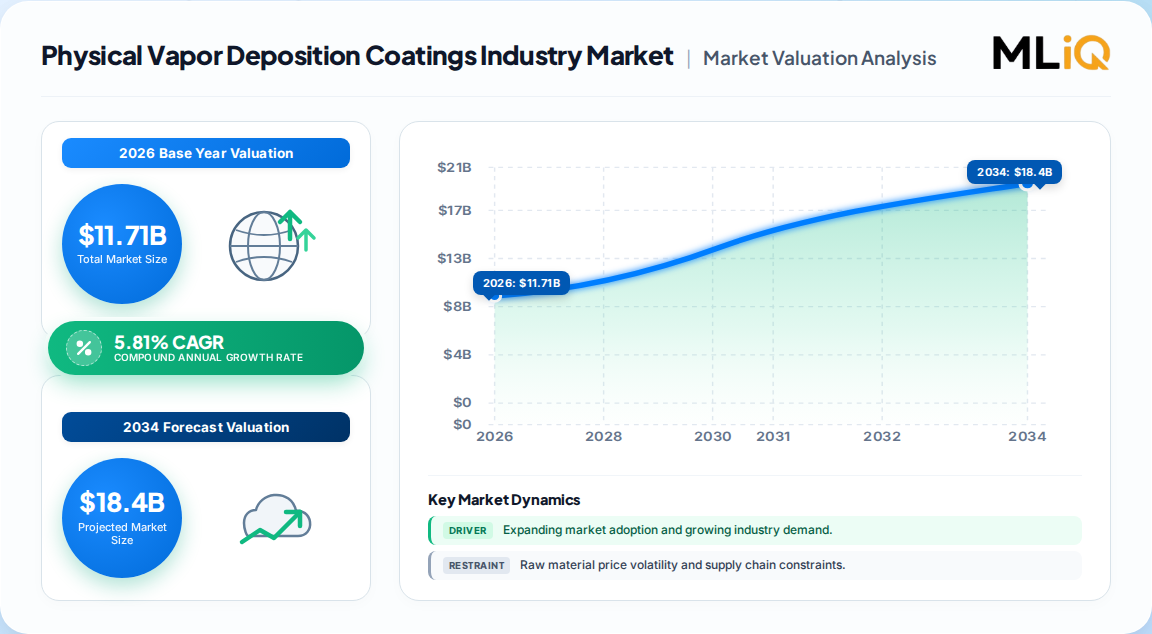
11.71 Billion — the Physical Vapor Deposition Coatings Industry market's 2026 global valuation, spanning equipment, materials, and coating services.
15.53 Billion — forecast 2031 size, implying a 5.81% CAGR over 2026–2031; a separate estimate places the base near 27.4 Billion, a definitional gap addressed below.
Sputter deposition is the leading process at 42.74% of 2025 revenue; HiPIMS is the fastest-growing at a 7.25% CAGR.
Ceramics and oxides captured 46.85% of 2025 material revenue, while metals substrates held 61.28%.
Asia-Pacific leads with 47.96% of 2025 revenue; Middle East & Africa is the fastest-growing region at 6.09% CAGR.
Leading vendors include Oerlikon Balzers, Applied Materials, IHI Corporation, and specialist coating-service providers.
Why this matters for decision-makers: Regulatory phase-out of hexavalent chromium is removing electroplating capacity within 24 months, making PVD line qualification a procurement priority, not a capital deferral.
Physical Vapor Deposition Coatings Industry Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
11.14 B
2025
11.71 B
2026
12.39 B
2027
13.11 B
2028
13.87 B
2029
14.68 B
2030
15.53 B
2031
Physical Vapor Deposition Coatings Industry Market Size (In Billion)
Year
Market Size
2025
11.14 B
2026
11.71 B
2027
12.39 B
2028
13.11 B
2029
13.87 B
2030
14.68 B
2031
15.53 B
What is the Physical Vapor Deposition Coatings Industry market?
The Physical Vapor Deposition Coatings Industry market covers vacuum-based thin-film deposition — sputtering, evaporation, and arc vapor techniques — applied to metals, plastics, glass, and ceramics for semiconductor, tooling, medical, automotive, and optical end uses. It includes deposition equipment, target materials, and contract coating services valued globally.
Scope: what this report covers and excludes
This analysis covers global PVD coating equipment, consumable targets, and coating services across semiconductor, cutting tools, medical devices, automotive, aerospace, optics, and solar applications. It addresses process types, substrate classes, material families, and end-user segments in value terms from 2021 to 2031.
This analysis does not cover chemical vapor deposition (CVD), atomic layer deposition (ALD), thermal spray, electroplating, or wet-chemistry coating processes except where referenced as substitution threats. Equipment-only aftermarket parts and non-coating vacuum metallurgy are excluded.
How big is the market for Physical Vapor Deposition Coatings Industry market?
The most defensible 2026 global figure is 11.71 Billion, growing at 5.81% CAGR to 15.53 Billion by 2031. A competing 27.4 Billion estimate reflects broader inclusion of equipment and services, not a contradiction in underlying demand.
Broader PVD industry incl. equipment and consumables adjacencies
Competing analysis
3.6 Billion
2026
2033
7.6%
PVD equipment-centric measure, narrower boundary
Alternate published estimate
Our analysis suggests the ~2.3× spread between the 11.71 Billion and 27.40 Billion figures is almost entirely definitional: one counts coating value and service revenue, the other sweeps in equipment, targets, and adjacent vacuum services. For procurement planning, the 11.71 Billion figure is the cleaner coatings-market denominator; for capital-equipment strategy, the equipment-centric view is more appropriate.
How is the market segmented?
Sputter deposition leads process type, ceramics and oxides lead material, and tools and components lead end use — a concentration pattern that makes the market sensitive to semiconductor and industrial capex cycles.
Metals, Ceramics and Oxides, DLC and Nitride Superlattices, Others
By End User
Tools and Components, Semiconductor and Electronics, Medical Devices, Automotive, Aerospace, Optics, Solar
Sputter deposition's 42.74% share reflects its versatility in alloy and compound films. The 6.38% CAGR on plastics substrates — driven by low-temperature decorative PVD replacing chrome trim — is the segment most likely to surprise on the upside. Aerospace components at 6.44% CAGR benefit from 3D-printed turbine part coating demand.
Which regions lead in Physical Vapor Deposition Coatings Industry market?
Asia-Pacific leads with 47.96% of 2025 revenue, anchored by semiconductor fabrication concentration in China, Taiwan, Japan, and South Korea. Middle East & Africa posts the fastest growth at 6.09% CAGR, driven by Saudi downstream manufacturing investment.
Physical Vapor Deposition Coatings Industry Regional Market Share
Loading chart...
Physical Vapor Deposition Coatings Industry Regional Market Share
China, Japan, South Korea, Taiwan, India, Southeast Asia
North America — Medical device, aerospace, and reshoring-driven semiconductor fab investment.
USA, Canada, Mexico
Europe — MDR compliance, REACH hex-chrome phase-out, and automotive decorative PVD.
Germany, UK, France, Italy, Rest of Europe
Middle East & Africa — Fastest-growing region; Vision 2030 downstream manufacturing.
Saudi Arabia, UAE, South Africa
South America — Smaller base, automotive and industrial tooling demand.
Brazil, Argentina, Colombia
What is driving growth — and what is holding it back?
Semiconductor node migration below 7nm and the hex-chrome regulatory phase-out are the two highest-impact drivers, each adding over 1 percentage point to CAGR. High capital intensity and vacuum-equipment maintenance costs remain the principal structural restraint.
Factor
Direction
Evidence Strength
Mechanism
Semiconductor node transition below 7nm
Driver
High
+1.4pp CAGR; cobalt/ruthenium liners add 3–4 deposition steps per wafer
Hex-chrome electroplating phase-out
Driver
High
+1.2pp CAGR; EPA NESHAP and EU REACH remove electroplating capacity
Minimally-invasive medical device growth
Driver
Medium-High
+0.9pp CAGR; TiN and DLC implant coatings meet ISO 10993
3D-printed parts needing conformal PVD
Driver
Medium
+0.7pp CAGR; 35% fatigue-life improvement on coated AM parts
Low-temperature decorative PVD on plastics
Driver
Medium
+0.8pp CAGR; automotive chrome-trim replacement
High upfront capital and operating cost
Restraint
High
Barrier for SME manufacturers; expensive equipment maintenance
Our analysis suggests the driver stack is unusually durable because regulatory and semiconductor cycles are non-correlated. A semiconductor capex slowdown would not offset the hex-chrome substitution wave, and vice versa — a portfolio effect that supports mid-single-digit growth even in a downturn.
Who are the leading vendors?
The market is moderately concentrated, with Oerlikon Balzers and Applied Materials anchoring equipment and service leadership while regional coating-service providers compete on application expertise and turnaround time.
Vendor
Position
Differentiation
Oerlikon Balzers
Global coating services and equipment
INVENTA PVD platform with Advanced Arc Technology; 45% jump in decorative automotive PVD requests in 2025
Applied Materials
Semiconductor PVD equipment
22% more PVD systems shipped in 2025; cobalt/ruthenium liner leadership at sub-3nm
IHI Corporation
Coating division, regional strength
Specialized coating services with Asia-Pacific footprint
Competitive moats rest on process qualification rather than equipment alone. Aerospace NADCAP AC7108 and medical ISO 10993 qualifications create multi-year switching costs that protect incumbents. Our analysis suggests service-based PVD providers face lower entry barriers than equipment manufacturers, intensifying price competition in commodity decorative coatings while premium segments remain defensible.
What do buyers and operators need to know?
Buyers should prioritize vendors with documented qualification to NADCAP AC7108 for aerospace and ISO 10993 for medical implants, because requalification costs dwarf initial coating price differences. Procurement risk concentrates in single-source target materials — cobalt, ruthenium, and yttria-stabilized zirconia supply — where geopolitical concentration creates lead-time exposure.
Switching costs are highest in semiconductor liner applications, where process requalification at sub-3nm nodes can consume 6–12 months. Operators should model total cost of ownership including vacuum pump maintenance, target utilization rates, and effluent handling, not just per-part coating price. Regulatory compliance is non-negotiable: EPA NESHAP mandates a 90% hex-chrome emissions cut by 2027, and EU REACH Annex XIV authorization rates below 30% mean electroplating alternatives may simply disappear. Buyers still relying on hex-chrome supply chains face a hard 2027 deadline.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-single-digit growth, regulation-driven substitution story rather than a pure semiconductor-cycle play. The 5.81% CAGR is credible and arguably conservative: the hex-chrome phase-out alone removes electroplating capacity that PVD must replace, and the semiconductor driver adds incremental deposition steps per wafer regardless of unit volume. The strongest counter-argument is capital intensity — if SME manufacturers defer PVD line investment amid tight credit, near-term growth could undershoot. We judge this a timing risk, not a structural one.
Our analysis suggests the 27.40 Billion competing estimate should not be dismissed but re-scoped: it likely captures equipment and consumables that the 11.71 Billion coatings figure excludes. Buyers comparing vendor proposals must force definitional alignment on whether targets and service contracts are in scope.
Actionable Strategy:
Equipment and service vendors should prioritize hex-chrome replacement qualification in aerospace and automotive Tier-1 supply chains before the 2027 EPA deadline to capture displaced electroplating volume.
Operators should lock multi-year target-material supply contracts for cobalt, ruthenium, and yttria-stabilized zirconia to hedge geopolitical concentration risk.
Investors should weight exposure toward HiPIMS and plastics-substrate decorative PVD, the two fastest-growing process and substrate segments.
What would change our conclusion: a sustained semiconductor capex contraction exceeding four quarters, or a regulatory delay to the EPA NESHAP 2027 deadline, would push growth toward the low end or below the stated CAGR. While this overview covers market-level dynamics, precise sub-segment forecasting by process type and end user requires the full report's bottom-up model.
Physical Vapor Deposition Coatings Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Physical Vapor Deposition Coatings Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.81% from 2020-2034
Segmentation
By Process Type
Sputter Deposition
Thermal/E-Beam Evaporation
Arc Vapor Deposition
HiPIMS
Others
By Substrate
Metals
Plastics
Glass
Ceramics
By Material Type
Metals
Ceramics and Oxides
DLC and Nitride Superlattices
Others
By End User
Tools and Components
Semiconductor and Electronics
Medical Devices
Automotive
Aerospace
Optics
Solar
By Geography
Asia Pacific
China
Japan
South Korea
Taiwan
India
Southeast Asia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Rest of Europe
Middle East & Africa
Saudi Arabia
UAE
South Africa
South America
Brazil
Argentina
Colombia
Table of Contents
1. Physical Vapor Deposition Coatings Industry Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Physical Vapor Deposition Coatings Industry Executive Summary
2.1. Market Snapshot
3. Physical Vapor Deposition Coatings Industry Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Physical Vapor Deposition Coatings Industry Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Physical Vapor Deposition Coatings Industry Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Process Type
5.1.1. Sputter Deposition
5.1.2. Thermal/E-Beam Evaporation
5.1.3. Arc Vapor Deposition
5.1.4. HiPIMS
5.1.5. Others
5.2. Analysis, Insights and Forecast - by Substrate
5.2.1. Metals
5.2.2. Plastics
5.2.3. Glass
5.2.4. Ceramics
5.3. Analysis, Insights and Forecast - by Material Type
5.3.1. Metals
5.3.2. Ceramics and Oxides
5.3.3. DLC and Nitride Superlattices
5.3.4. Others
5.4. Analysis, Insights and Forecast - by End User
5.4.1. Tools and Components
5.4.2. Semiconductor and Electronics
5.4.3. Medical Devices
5.4.4. Automotive
5.4.5. Aerospace
5.4.6. Optics
5.4.7. Solar
5.5. Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. North America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. South America
6. Physical Vapor Deposition Coatings Industry Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Process Type
6.1.1. Sputter Deposition
6.1.2. Thermal/E-Beam Evaporation
6.1.3. Arc Vapor Deposition
6.1.4. HiPIMS
6.1.5. Others
6.2. Analysis, Insights and Forecast - by Substrate
6.2.1. Metals
6.2.2. Plastics
6.2.3. Glass
6.2.4. Ceramics
6.3. Analysis, Insights and Forecast - by Material Type
6.3.1. Metals
6.3.2. Ceramics and Oxides
6.3.3. DLC and Nitride Superlattices
6.3.4. Others
6.4. Analysis, Insights and Forecast - by End User
6.4.1. Tools and Components
6.4.2. Semiconductor and Electronics
6.4.3. Medical Devices
6.4.4. Automotive
6.4.5. Aerospace
6.4.6. Optics
6.4.7. Solar
7. Physical Vapor Deposition Coatings Industry North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Process Type
7.1.1. Sputter Deposition
7.1.2. Thermal/E-Beam Evaporation
7.1.3. Arc Vapor Deposition
7.1.4. HiPIMS
7.1.5. Others
7.2. Analysis, Insights and Forecast - by Substrate
7.2.1. Metals
7.2.2. Plastics
7.2.3. Glass
7.2.4. Ceramics
7.3. Analysis, Insights and Forecast - by Material Type
7.3.1. Metals
7.3.2. Ceramics and Oxides
7.3.3. DLC and Nitride Superlattices
7.3.4. Others
7.4. Analysis, Insights and Forecast - by End User
7.4.1. Tools and Components
7.4.2. Semiconductor and Electronics
7.4.3. Medical Devices
7.4.4. Automotive
7.4.5. Aerospace
7.4.6. Optics
7.4.7. Solar
8. Physical Vapor Deposition Coatings Industry Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Process Type
8.1.1. Sputter Deposition
8.1.2. Thermal/E-Beam Evaporation
8.1.3. Arc Vapor Deposition
8.1.4. HiPIMS
8.1.5. Others
8.2. Analysis, Insights and Forecast - by Substrate
8.2.1. Metals
8.2.2. Plastics
8.2.3. Glass
8.2.4. Ceramics
8.3. Analysis, Insights and Forecast - by Material Type
8.3.1. Metals
8.3.2. Ceramics and Oxides
8.3.3. DLC and Nitride Superlattices
8.3.4. Others
8.4. Analysis, Insights and Forecast - by End User
8.4.1. Tools and Components
8.4.2. Semiconductor and Electronics
8.4.3. Medical Devices
8.4.4. Automotive
8.4.5. Aerospace
8.4.6. Optics
8.4.7. Solar
9. Physical Vapor Deposition Coatings Industry Middle East & Africa Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Process Type
9.1.1. Sputter Deposition
9.1.2. Thermal/E-Beam Evaporation
9.1.3. Arc Vapor Deposition
9.1.4. HiPIMS
9.1.5. Others
9.2. Analysis, Insights and Forecast - by Substrate
9.2.1. Metals
9.2.2. Plastics
9.2.3. Glass
9.2.4. Ceramics
9.3. Analysis, Insights and Forecast - by Material Type
9.3.1. Metals
9.3.2. Ceramics and Oxides
9.3.3. DLC and Nitride Superlattices
9.3.4. Others
9.4. Analysis, Insights and Forecast - by End User
9.4.1. Tools and Components
9.4.2. Semiconductor and Electronics
9.4.3. Medical Devices
9.4.4. Automotive
9.4.5. Aerospace
9.4.6. Optics
9.4.7. Solar
10. Physical Vapor Deposition Coatings Industry South America Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Process Type
10.1.1. Sputter Deposition
10.1.2. Thermal/E-Beam Evaporation
10.1.3. Arc Vapor Deposition
10.1.4. HiPIMS
10.1.5. Others
10.2. Analysis, Insights and Forecast - by Substrate
10.2.1. Metals
10.2.2. Plastics
10.2.3. Glass
10.2.4. Ceramics
10.3. Analysis, Insights and Forecast - by Material Type
10.3.1. Metals
10.3.2. Ceramics and Oxides
10.3.3. DLC and Nitride Superlattices
10.3.4. Others
10.4. Analysis, Insights and Forecast - by End User
10.4.1. Tools and Components
10.4.2. Semiconductor and Electronics
10.4.3. Medical Devices
10.4.4. Automotive
10.4.5. Aerospace
10.4.6. Optics
10.4.7. Solar
11. Physical Vapor Deposition Coatings Industry Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Physical Vapor Deposition Coatings Industry Research Methodology
List of Figures
Figure 1: Physical Vapor Deposition Coatings Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue (Billion), by Process Type 2026 & 2034
Figure 3: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Share (%), by Process Type 2026 & 2034
Figure 4: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue (Billion), by Substrate 2026 & 2034
Figure 5: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Share (%), by Substrate 2026 & 2034
Figure 6: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue (Billion), by Material Type 2026 & 2034
Figure 7: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Share (%), by Material Type 2026 & 2034
Figure 8: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue (Billion), by End User 2026 & 2034
Figure 9: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Share (%), by End User 2026 & 2034
Figure 10: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue (Billion), by Country 2026 & 2034
Figure 11: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Share (%), by Country 2026 & 2034
Figure 12: North America Physical Vapor Deposition Coatings Industry Revenue (Billion), by Process Type 2026 & 2034
Figure 13: North America Physical Vapor Deposition Coatings Industry Revenue Share (%), by Process Type 2026 & 2034
Figure 14: North America Physical Vapor Deposition Coatings Industry Revenue (Billion), by Substrate 2026 & 2034
Figure 15: North America Physical Vapor Deposition Coatings Industry Revenue Share (%), by Substrate 2026 & 2034
List of Tables
Table 1: Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Process Type 2020 & 2034
Table 2: Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Substrate 2020 & 2034
Table 3: Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Material Type 2020 & 2034
Table 4: Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 5: Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 6: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Process Type 2020 & 2034
Table 7: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Substrate 2020 & 2034
Table 8: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Material Type 2020 & 2034
Table 9: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by End User 2020 & 2034
Table 10: Asia Pacific Physical Vapor Deposition Coatings Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 11: China Physical Vapor Deposition Coatings Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Japan Physical Vapor Deposition Coatings Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: South Korea Physical Vapor Deposition Coatings Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Taiwan Physical Vapor Deposition Coatings Industry Revenue (Billion) Forecast, by Application 2020 & 2034
India Physical Vapor Deposition Coatings Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the PVD coatings market in 2026?
The global Physical Vapor Deposition Coatings Industry market is valued at 11.71 Billion in 2026, forecast to reach 15.53 Billion by 2031 at a 5.81% CAGR. Broader definitions including all equipment reach higher figures.
2. Which PVD process type is growing fastest?
HiPIMS (High-Power Impulse Magnetron Sputtering) is the fastest-growing process at a 7.25% CAGR through 2031, while sputter deposition leads with 42.74% of 2025 revenue.
3. Which region dominates PVD coatings demand?
Asia-Pacific dominates with 47.96% of 2025 revenue, driven by semiconductor fabrication in China, Taiwan, Japan, and South Korea. Middle East & Africa is the fastest-growing region at 6.09% CAGR.
4. What is driving PVD adoption over electroplating?
Regulatory phase-outs of hexavalent chromium under EPA NESHAP and EU REACH are removing electroplating capacity, redirecting capital toward zero-effluent PVD systems, particularly in aerospace and automotive supply chains.
5. Who are the leading PVD coating vendors?
Oerlikon Balzers leads coating services and equipment, Applied Materials leads semiconductor PVD equipment, and IHI Corporation holds regional strength. The market is moderately concentrated with a fragmented service tail.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with target-material suppliers, PVD equipment manufacturers, contract coating-service providers, and global industrial distributors. Decision-maker participants included VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads, ensuring both demand-side procurement intent and supply-side capacity signals are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Quality & Regulatory Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Target Material Suppliers
40%
PVD Equipment Manufacturers
30%
Contract Coating Service Providers
20%
Global Distributors
10%
Secondary Benchmarking & Public Trade Validation
We validate findings against UN Comtrade and US ITC trade flows for sputtering targets and vacuum equipment, Eurostat industrial production data, corporate 10-K and SEC filings from publicly listed equipment vendors, patent databases tracking HiPIMS and arc-vapor innovations, and technical standards from ISO and NADCAP-recognized bodies governing coating qualification.
Demand Modeling & Market Sizing Triangulation
Simultaneous top-down macroeconomic and industry-segment allocation is reconciled with bottom-up manufacturer capacity, target-material pricing, and end-use consumption modeling. Divergences between the two approaches are resolved through segment-level reconciliation interviews.


 Physical Vapor Deposition Coatings Industry