Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Carrageenan Market by Product Type (Kappa, Iota, Lambda), by Function (Thickener, Stabilizer, Gelling Agent, Others), by Processing Technology (Semi-refined, Gel Press, Alcohol Precipitation), by Application (Food & Beverage(Dairy, Meat, Beverages, Plant-based), Pharmaceutical, Personal Care & Cosmetics), by Europe (Germany, UK, France, Italy, Spain), by North America (USA, Canada, Mexico), by Asia-Pacific (China, Japan, India, South Korea, Indonesia, Philippines), by South America (Brazil, Chile, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
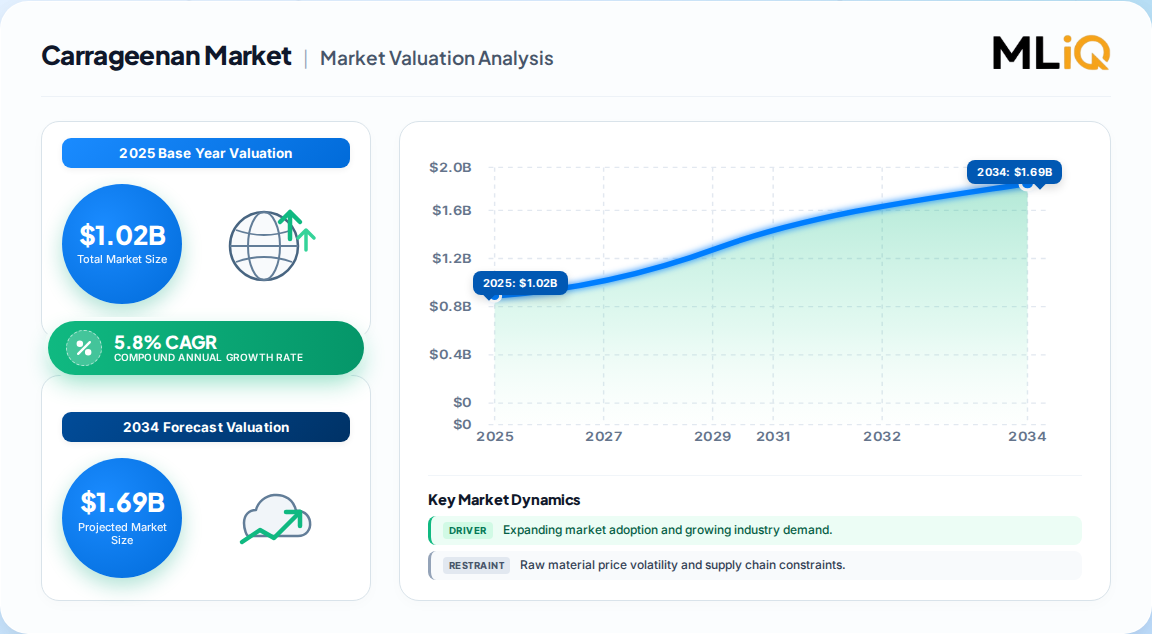
Market Size: The global carrageenan market was valued at 1.02 Billion in 2025 and is projected to reach 1.70 Billion by 2034.
Forecast: A 5.8% CAGR is expected from 2026 to 2034, driven by clean-label and plant-based food demand.
Leading Segment: Kappa carrageenan dominates with 58.4% share (2025); food & beverage applications account for ~73% of revenue.
Leading Regions: Europe leads with 35% revenue share, followed by Asia-Pacific (28%), which is the fastest-growing region.
Key Players: DuPont, Cargill, CP Kelco, Ingredion, and Gelymar lead a moderately consolidated competitive landscape.
Why this matters for decision-makers: Vendors must pivot toward pharmaceutical-grade and organic-certified carrageenan to capture high-margin growth and mitigate raw material price volatility.
Carrageenan Market Size (In Billion)
1.5B
1.0B
500.0M
0
1.020 B
2025
1.080 B
2026
1.140 B
2027
1.210 B
2028
1.280 B
2029
1.350 B
2030
1.430 B
2031
Carrageenan Market Size (In Billion)
Year
Market Size
2025
1.020 B
2026
1.080 B
2027
1.140 B
2028
1.210 B
2029
1.280 B
2030
1.350 B
2031
1.430 B
What is the Carrageenan Market?
The carrageenan market encompasses the global production, processing, and distribution of sulfated polysaccharides extracted from red seaweed. Used primarily as a gelling, thickening, and stabilizing agent, carrageenan serves food & beverage, pharmaceutical, and personal care industries. Its plant-based origin aligns with clean-label trends, while functional properties drive demand in dairy, meat, and plant-based alternatives.
Scope: what this report covers and excludes
This analysis covers the global carrageenan market, focusing on kappa, iota, and lambda product types, food & beverage, pharmaceutical, and personal care applications, and all major regions. It includes processing technologies (semi-refined, gel press, alcohol precipitation) and evaluates market dynamics, competitive landscape, and regulatory shifts. This analysis does not cover adjacent hydrocolloids such as agar, xanthan gum, or guar gum, nor does it examine seaweed farming economics in isolation.
How big is the market for Carrageenan Market?
The market size is estimated at 1.02 Billion in 2025, with competing forecasts projecting growth to between 1.5 Billion (2033) and 1.70 Billion (2034). The divergence stems from differing base years, CAGR assumptions (4.6% vs. 5.8%), and scope definitions regarding pharmaceutical applications.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
1.0 Billion
2025
2033
4.6%
Broad food & beverage focus
One published estimate
1.02 Billion
2025
2034
5.8%
Includes pharmaceutical & personal care
Another published analysis
850 Million
2022
2032
6.2%
Narrower hydrocolloid scope
A competing analysis
Our analysis suggests the 5.8% CAGR is most defensible, as it captures the post-2025 recovery in pharmaceutical demand and accounts for the full regulatory impact of EU additive re-evaluations. The lower 4.6% estimate likely underweights the rapid expansion of plant-based dairy alternatives in Asia-Pacific.
How is the market segmented?
The carrageenan market is segmented by product type (kappa, iota, lambda), function (thickener, stabilizer, gelling agent), processing technology (semi-refined, gel press, alcohol precipitation), and application (food & beverage, pharmaceutical, personal care). Kappa leads in volume due to its strong gelling properties in dairy and meat.
Parent Segment
Children
By Product Type
Kappa, Iota, Lambda
By Function
Thickener, Stabilizer, Gelling Agent, Others
By Processing Technology
Semi-refined, Gel Press, Alcohol Precipitation
By Application
Food & Beverage (Dairy, Meat, Beverages, Plant-based), Pharmaceutical, Personal Care & Cosmetics
Which region leads in Carrageenan Market?
Europe leads the global carrageenan market with approximately 35% revenue share, driven by stringent clean-label regulations and high processed meat consumption. Asia-Pacific is the fastest-growing region (CAGR ~6.5%), fueled by expanding food manufacturing in China, Indonesia, and the Philippines. North America remains a mature market with strong pharmaceutical and personal care demand.
Carrageenan Market Regional Market Share
Loading chart...
Carrageenan Market Regional Market Share
Region
Market Share (%)
Europe
0.35%
North America
0.22%
Asia-Pacific
0.28%
South America
0.08%
Middle East & Africa
0.07%
Europe (Germany, UK, France, Italy) – 35%
Germany: Largest country market, strong dairy and meat processing base.
UK: High demand for plant-based beverages and clean-label products.
Asia-Pacific (China, Japan, India, South Korea, Indonesia) – 28%
China: Rapid expansion of processed food and pharmaceutical sectors.
Indonesia/Philippines: Key seaweed cultivation and semi-refined processing hubs.
North America (USA, Canada, Mexico) – 22%
USA: Mature market, high adoption in personal care and pharmaceuticals.
South America (Brazil, Mexico, Argentina) – 8%
Middle East & Africa (Saudi Arabia, UAE, South Africa) – 7%
What is driving growth — and what is holding it back?
Growth is primarily driven by rising demand for clean-label and plant-based food ingredients, which favor carrageenan over synthetic alternatives. However, fluctuating seaweed supply and raw material price volatility represent the most significant restraint, alongside health concerns regarding carrageenan consumption.
Factor
Direction
Evidence Strength
Mechanism
Clean-label & plant-based demand
Driver
High
Carrageenan replaces animal-derived gelatin and synthetic stabilizers.
Pharmaceutical applications
Driver
Medium-High
Used in drug delivery, emulsions, and controlled-release formulations.
Seaweed supply volatility
Restraint
High
Climate change and disease outbreaks disrupt harvests, raising prices.
Health concerns (inflammation)
Restraint
Medium
Consumer advocacy groups push for reformulation, especially in food.
Organic personal care
Opportunity
Medium
Plant-derived thickening agents gain traction in cosmetics.
Our analysis suggests the driver-restraint balance favors growth, as innovation in pharmaceutical and organic personal care applications offsets food-sector regulatory pressures. However, buyers should monitor EU re-evaluations of E 407, which could impose stricter limits on processed meat and dairy applications.
Who are the leading vendors?
The carrageenan market is moderately consolidated, with DuPont, Cargill, CP Kelco, and Ingredion controlling a significant share of global capacity. These companies compete on extraction technology, product purity, and application-specific formulations.
Company
Headquarters
Key Differentiator
DuPont (IFF)
USA
Broad hydrocolloid portfolio; strong R&D in pharmaceutical grades.
Seaweed-based texturizing solutions; strong in dairy and beverages.
Ingredion
USA
Extensive distribution network; focus on clean-label formulations.
Gelymar
Chile
Regional leader in semi-refined carrageenan; cost-competitive.
Ceamsa
Spain
Specialty grades for meat and dairy; strong European presence.
The competitive moat lies in sustainable seaweed sourcing and regulatory compliance. Smaller producers in Southeast Asia compete on price but face challenges in meeting EU and US pharmacopeia standards. Strategic acquisitions and capacity expansions are likely as demand for pharmaceutical-grade carrageenan rises.
What do buyers and operators need to know?
Buyers must prioritize supplier diversification to mitigate seaweed supply shocks, particularly for kappa carrageenan sourced from Indonesia and the Philippines. Regulatory compliance is mission-critical: the EU’s 2026 amendment to E 407 regulations (Regulation 2026/196) tightens usage limits in meat preparations and dairy, requiring reformulation or alternative stabilizers. Procurement risks include price volatility (seaweed prices have fluctuated ±30% annually) and quality inconsistencies in semi-refined grades. Switching costs are moderate; however, reformulating food products to remove carrageenan can be costly due to texture and shelf-life impacts. Operators should invest in long-term supply agreements with vertically integrated producers and consider dual-sourcing from Latin America (Chile, Mexico) to reduce Asia-Pacific dependency.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors cautious optimism for the carrageenan market, with a 5.8% CAGR reflecting steady demand from food and pharmaceutical sectors. The strongest counter-argument is the health concern narrative, which could accelerate reformulation in food applications, particularly in Europe and North America. However, regulatory bodies have repeatedly affirmed carrageenan’s safety at approved levels, and its functional superiority in plant-based dairy alternatives is difficult to replicate cost-effectively.
Our analysis suggests the most significant opportunity lies in pharmaceutical-grade carrageenan, where controlled-release and tissue-engineering applications command premium pricing and face less consumer backlash. Vendors should also target organic-certified personal care products, where plant-derived texturizers are in high demand. Conversely, food manufacturers should prepare for tighter EU regulations by exploring blends with locust bean gum or xanthan gum.
Actionable Strategy:
For investors: Focus on companies with vertically integrated seaweed supply and pharmaceutical-grade certification to capture high-margin growth.
For operators: Diversify raw material sourcing across Southeast Asia and Latin America; invest in semi-refined processing technology to reduce costs.
For buyers: Lock in long-term contracts with Cargill, CP Kelco, or DuPont to hedge against price volatility; verify compliance with EU 2026/196 for meat and dairy applications.
What evidence would change our conclusion: A major regulatory ban on carrageenan in food (e.g., by the EU or FDA) or a scalable, cost-competitive synthetic alternative would significantly alter the growth trajectory. We would also revise our forecast downward if seaweed harvests decline by more than 15% for two consecutive years due to climate change.
Table 16: North America Carrageenan Market Revenue Billion Forecast, by Product Type 2020 & 2034
North America Carrageenan Market Revenue Billion Forecast, by Function 2020 & 2034
Frequently Asked Questions
1. What is the current size of the carrageenan market?
The global carrageenan market was valued at approximately 1.02 Billion in 2025, with forecasts projecting growth to 1.70 Billion by 2034.
2. Which region dominates the carrageenan market?
Europe leads with about 35% revenue share, driven by clean-label food demand and stringent regulations on additives.
3. What are the key drivers for carrageenan demand?
Rising demand for plant-based and clean-label food ingredients, plus expanding pharmaceutical applications, are the primary growth drivers.
4. What are the main challenges facing the carrageenan market?
Seaweed supply volatility, raw material price fluctuations, and health concerns about carrageenan consumption are the main restraints.
5. Who are the leading companies in the carrageenan market?
Major players include DuPont, Cargill, CP Kelco, Ingredion, and Gelymar, with a focus on sustainable sourcing and product innovation.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology is built on a 70/30 primary-to-secondary research split, ensuring that market estimates are grounded in direct industry validation. We conducted in-depth interviews with key stakeholders across the carrageenan value chain, including red seaweed cultivators and harvesters, specialized carrageenan extractors and processors, contract formulators for food and pharmaceutical applications, and global distributors of hydrocolloids. Interviewees included decision-makers such as VPs of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, providing insights into capacity, pricing, and demand trends.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VPs of Sourcing & Procurement
35%
Heads of R&D & Formulation
30%
Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Seaweed Cultivators & Harvesters
30%
Carrageenan Extractors & Processors
45%
Contract Formulators & Blenders
15%
Global Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
We cross-validated primary insights with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) and corporate filings (10-K, SEC filings, annual investor presentations). Patent databases were analyzed for innovation trends in extraction and application technologies. Recognized technical standards from the FAO/WHO Joint Expert Committee on Food Additives (JECFA) and EU food additive regulations (E 407) provided the regulatory framework for compliance assessment.
Demand Modeling & Market Sizing Triangulation
Market sizing was derived through simultaneous top-down and bottom-up modeling. The top-down approach allocated global macroeconomic food and pharmaceutical industry output to carrageenan usage based on historical penetration rates. The bottom-up approach modeled manufacturer capacity utilization, product pricing by grade, and end-use consumption across dairy, meat, plant-based beverages, and personal care. Discrepancies between the two models were reconciled through iterative validation with primary interview data.


 Carrageenan Market