Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Nanostructured Carbon Composite Market by Product Type (Carbon Nanotube Composites, Graphene Composites, Carbon Nanofiber Composites, Hybrid Nanocarbon Composites), by Application (Aerospace & Defense, Automotive, Electronics & Semiconductors, Energy Storage & Batteries, Industrial Equipment), by Primary Customer Type (OEMs, Industrial Manufacturers, Research Institutions, Defense Contractors), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Rest of Europe), by Asia Pacific (China, Japan, South Korea, India, Australia), by Latin America (Brazil, Argentina, Colombia, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 0
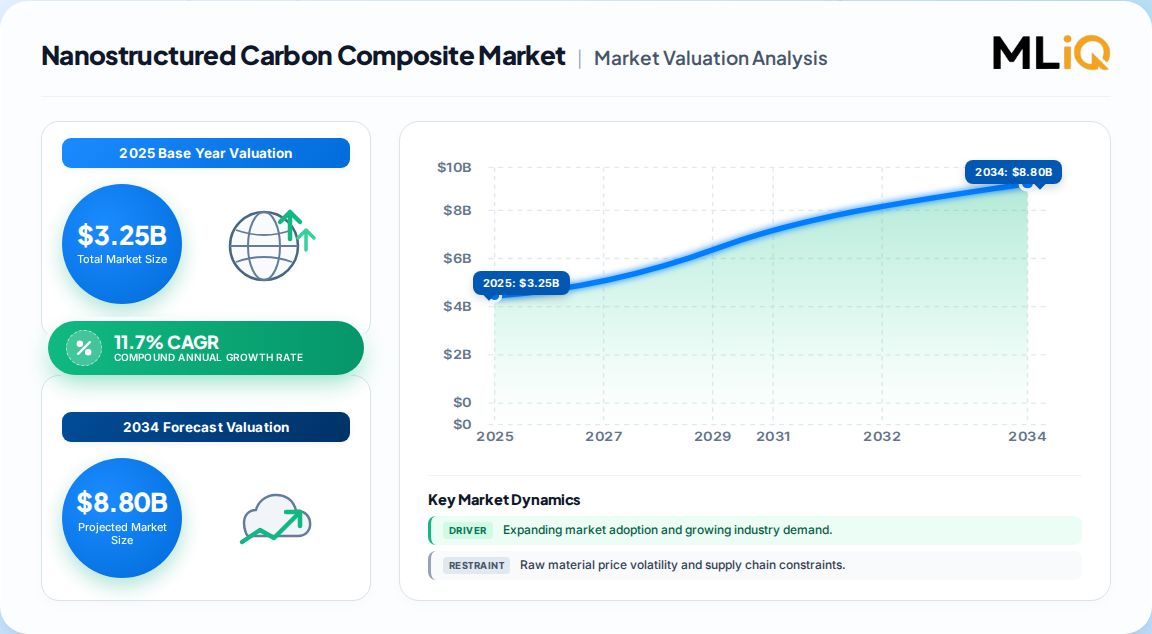
The global nanostructured carbon composite market was valued at USD 3.25 billion in 2025 and is projected to reach USD 7.05 billion by 2032, expanding at a CAGR of 11.7%.
Graphene composites are the fastest-growing product class at 12.8% CAGR, while CNT composites retain the largest revenue share at 38%.
Energy storage & batteries represent the fastest-growing application at 13.4% CAGR, followed by electronics & semiconductors at 12.7%.
North America leads with 34% of global revenue, but Asia Pacific is the fastest-growing region at 13.6% CAGR, driven by battery and electronics manufacturing concentration.
OEMs are the largest customer group (36% share), yet growth is increasingly driven by industrial manufacturers adopting pre-dispersed, process-ready formulations.
Why this matters for decision-makers: Suppliers that prioritize dispersion quality, process compatibility, and qualification support over raw nanocarbon purity will capture the highest value and avoid margin erosion as the market shifts toward formulated intermediates.
Nanostructured Carbon Composite Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.250 B
2025
3.630 B
2026
4.060 B
2027
4.530 B
2028
5.060 B
2029
5.650 B
2030
6.310 B
2031
Nanostructured Carbon Composite Market Size (In Billion)
Year
Market Size
2025
3.250 B
2026
3.630 B
2027
4.060 B
2028
4.530 B
2029
5.060 B
2030
5.650 B
2031
6.310 B
What is the Nanostructured Carbon Composite Market?
The nanostructured carbon composite market encompasses engineered materials where carbon nanotubes (CNTs), graphene, carbon nanofibers, or hybrid nanocarbon networks are incorporated into polymers, resins, elastomers, coatings, ceramics, or battery-electrode formulations. These composites deliver electrical conductivity, thermal management, EMI shielding, and mechanical reinforcement at low filler loading, making them critical for lightweight, multifunctional applications.
Scope: what this report covers and excludes
This analysis covers revenue from CNT-, graphene-, CNF-, and hybrid-nanocarbon composite materials and formulated intermediates such as masterbatches, concentrates, dispersions, engineered resins, conductive pastes, functional coatings, and component-ready compounds. Conventional carbon-fiber composites without nanoscale carbon and standalone graphene devices are excluded, as are upstream nanocarbon powders sold for non-composite uses.
How big is the market for Nanostructured Carbon Composite Market?
A leading estimate places the market at USD 3.25 billion in 2025, growing to USD 7.05 billion by 2032 at 11.7% CAGR. A competing analysis values the market at USD 5.71 billion in 2025, reaching USD 12.06 billion by 2033 at 9.8% CAGR. The difference stems from scope: the former excludes conventional carbon-fiber composites and standalone graphene devices.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 3.25 Billion
2025
2032
11.7%
CNT, graphene, CNF, hybrid nanocomposites and formulated intermediates
SMR (Strategic Market Research)
USD 5.71 Billion
2025
2033
9.8%
Broader definition including some conventional composites and fullerene
Cognitive Market Research
Our analysis suggests that the SMR figure is more defensible for strategic planning because its scope aligns with commercially traded nanocomposite products and excludes double-counting. The higher figure likely includes adjacent materials that are not nanostructured carbon composites in the strict sense, such as conventional carbon-fiber composites and fullerene-based systems.
How is the market segmented?
The market is segmented by product type, application, and primary customer type. Product type includes CNT, graphene, carbon nanofiber, and hybrid nanocarbon composites. Applications span aerospace & defense, automotive, electronics & semiconductors, energy storage & batteries, and industrial equipment. Customer types include OEMs, industrial manufacturers, research institutions, and defense contractors.
OEMs, Industrial Manufacturers, Research Institutions, Defense Contractors
Which region leads in Nanostructured Carbon Composite Market?
North America leads the global nanostructured carbon composite market with 34% revenue share in 2025, followed by Asia Pacific at 32% and Europe at 23%. Asia Pacific is the fastest-growing region, projected at 13.6% CAGR, driven by battery and electronics manufacturing concentration.
Asia Pacific: China, Japan, South Korea, India, Australia
Europe: Germany, UK, France, Italy, Rest of Europe
Latin America: Brazil, Argentina, Colombia, Chile
Middle East & Africa: Saudi Arabia, UAE, South Africa
Our analysis suggests that Asia Pacific's share will continue to expand as battery and electronics production localizes, potentially overtaking North America by the early 2030s. This shift implies that suppliers must build regional formulation and qualification capabilities to capture growth.
What is driving growth — and what is holding it back?
Growth is driven by EV battery deployment, electronics miniaturization, aerospace lightweighting, and the shift toward pre-dispersed formulations. Restraints include high production costs, lengthy qualification cycles, and competition from conventional fillers like carbon black and graphite.
Factor
Direction
Evidence Strength
Mechanism
EV battery deployment (1.2 TWh in 2025)
Driver
High
Expands demand for CNT conductive additives in electrodes
Electronics & semiconductor manufacturing growth
Driver
High
Drives EMI shielding, thermal management, and ESD applications
Aerospace backlog (Airbus 8,754 aircraft)
Driver
Medium
Creates long-term demand for lightweight multifunctional composites
High nanocarbon production costs
Restraint
Medium
Limits adoption in price-sensitive applications
Lengthy qualification cycles
Restraint
High
Delays revenue realization from trials to production
Competition from carbon black and graphite
Restraint
High
Caps premium pricing in less demanding applications
The balance of evidence favors the drivers, but the pace of growth depends on suppliers' ability to reduce cost-per-function through dispersion and formulation innovation. The main upside is wider CNT adoption in battery electrodes and graphene masterbatches in molded polymers. The main constraint is whether suppliers can deliver repeatable industrial performance at a cost that beats conventional fillers after processing and qualification costs.
Who are the leading vendors?
Leading vendors include OCSiAl, Arkema, Birla Carbon (Nanocyl), NanoXplore, Cabot Corporation, LG Chem, and Cnano. These players compete on dispersion know-how, application-ready formulations, and customer qualification support rather than raw nanocarbon purity alone.
Company
Positioning
Key Differentiator
OCSiAl
Single-wall CNT technology and pre-dispersed formulations
Battery qualification (PowerCo supplier)
Arkema
Graphistrength MWCNT masterbatches
Thermoplastic, elastomer, and thermoset formats
Birla Carbon (Nanocyl)
MWCNT masterbatches and dispersions
Industrial scale and conductive carbon platform
NanoXplore
Integrated graphene model
Powder, masterbatch, and downstream composites (Club Car agreement)
Cabot Corporation
Broad conductive-carbon platform
CNT dispersions combined with other conductive carbons
LG Chem
Battery-oriented CNT supply
Scale in Asia's battery manufacturing
Cnano
CNT powders, pastes, masterbatches
Cost-effective battery conductive additives
The competitive moat is shifting from nanocarbon synthesis to formulation and qualification support. Vendors that can help customers reduce formulation work, shorten validation cycles, and ensure consistent dispersion will build switching costs and capture recurring revenue.
What do buyers and operators need to know? (Decision Support)
Buyers should prioritize suppliers that offer pre-dispersed, process-compatible formulations, as these reduce internal formulation work and minimize production risks. The ability to run nanostructured carbon composites through existing extrusion, injection molding, or coating equipment is a key selection criterion. Procurement risks include inconsistent dispersion quality, which can lead to batch failures and costly revalidation. Regulatory compliance, such as REACH nanoform documentation and TSCA requirements, adds complexity and should be verified early. Switching costs are high once a formulation is embedded in an approved specification, making initial selection critical. Operators should demand evidence of repeatable performance at plant scale and seek suppliers that provide application engineering support. Our analysis suggests that buyers who engage suppliers with robust qualification capabilities will achieve faster time-to-market and lower total cost of ownership.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook for the nanostructured carbon composite market, with the SMR estimate of 11.7% CAGR to 2032 being the most defensible. The strongest counter-argument is that high costs and lengthy qualification cycles could slow adoption, particularly in price-sensitive industrial applications. However, the accelerating demand from EV batteries and electronics, where performance premiums are easily justified, mitigates this risk. The market is shifting from selling nanocarbon powders to delivering process-ready formulations, and suppliers that fail to adapt will face margin compression.
Actionable Strategy:
For investors: Prioritize suppliers with strong dispersion and formulation capabilities, especially those serving battery and electronics value chains in Asia Pacific.
For operators: Evaluate pre-dispersed masterbatches and concentrates to shorten qualification timelines and reduce internal formulation costs.
For suppliers: Invest in application engineering and qualification support to build switching costs and capture recurring revenue from OEMs.
Evidence that would change our conclusion: a significant drop in nanocarbon prices or a breakthrough in competing conductive fillers that erodes the cost-per-function advantage of nanostructured carbon composites.
Table 12: Europe Nanostructured Carbon Composite Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 13: Europe Nanostructured Carbon Composite Market Revenue Billion Forecast, by Application 2020 & 2034
Table 14: Europe Nanostructured Carbon Composite Market Revenue Billion Forecast, by Primary Customer Type 2020 & 2034
Table 15: Europe Nanostructured Carbon Composite Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1. What is the current size of the nanostructured carbon composite market?
The market was valued at USD 3.25 billion in 2025 and is projected to reach USD 7.05 billion by 2032, growing at 11.7% CAGR according to a leading estimate.
2. Which region leads in nanostructured carbon composite market?
North America leads with 34% revenue share, but Asia Pacific is the fastest-growing region at 13.6% CAGR, driven by battery and electronics manufacturing.
3. What are the key driving factors for the nanostructured carbon composite market?
Key drivers include EV battery deployment, electronics miniaturization, aerospace lightweighting, and the shift toward pre-dispersed, process-ready formulations.
4. What are the main challenges faced by the nanostructured carbon composite market?
Main challenges include high production costs, lengthy qualification cycles, and competition from conventional fillers like carbon black and graphite.
5. Who are the leading players in the nanostructured carbon composite market?
Leading players include OCSiAl, Arkema, Birla Carbon (Nanocyl), NanoXplore, Cabot Corporation, LG Chem, and Cnano.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology is built on a 70/30 primary-to-secondary research split, ensuring that market estimates are grounded in direct industry validation. We conducted in-depth interviews with key stakeholders across the value chain, including raw material suppliers, specialized producers of nanostructured carbon composites, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided critical insights into demand drivers, qualification cycles, and pricing dynamics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement Directors
35%
Quality & Regulatory Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
45%
Formulators & Blenders
35%
Distributors & Traders
20%
Secondary Benchmarking & Public Trade Validation
Our secondary research leveraged official multilateral trade databases such as UN Comtrade and WTO statistics, alongside corporate annual filings (10-K, SEC filings, investor presentations) and patent databases. We also referenced recognized technical standards and industry associations, including ISO/TS 80004-13:2024 for graphene terminology and IEC TS 62607-6-33:2025 for graphene defect-density measurement. These sources validated material definitions and market comparability.
Demand Modeling & Market Sizing Triangulation
We employed simultaneous top-down and bottom-up modeling to triangulate market size. Top-down analysis allocated macroeconomic and industry segment spending to nanostructured carbon composites, while bottom-up modeling utilized manufacturer capacity, product pricing, and end-use consumption patterns. This dual approach ensured consistency and identified discrepancies for further validation.


 Nanostructured Carbon Composite Market