 Formalin Market
 Size, Share & Growth Forecast 2025–2030
Updated On : Nov 19, 2026|Base Year : 2025|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Formalin Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2022 | 7.570 B |
| 2023 | 7.980 B |
| 2024 | 8.410 B |
| 2025 | 8.860 B |
| 2026 | 9.340 B |
| 2027 | 9.850 B |
| 2028 | 10.38 B |

The formalin market covers the production, distribution and sale of formaldehyde solutions — typically 37–40% formaldehyde in water with methanol stabilizer. Formalin is used as a disinfectant, preservative, tissue fixative and chemical intermediate for resins, fertilizers, dyes, rubber chemicals and automotive components.
This report covers global formalin solutions across percentage concentrations (1.0%–60.0%), end-use applications and five major regions. It includes volume and value forecasts to 2030.
This analysis does not cover methanol or urea feedstock markets in isolation, paraformaldehyde, urea-formaldehyde and melamine-formaldehyde resin markets as standalone categories, or prefilled formalin vial consumables as a distinct product market.
Published valuations of the formalin market cluster tightly around 7.5–7.6 Billion for the 2022 base year, with forecasts to 2030 ranging from 10.3 to 11.7 Billion depending on base year and scope.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 7.57 Billion | 2022 | 2028 | 5.22% | Global formalin solutions, value terms | One published estimate |
| 7.5 Billion | 2022 | 2030 | 5.5% | Global formalin, value and volume (22,185 kilo tonnes) | A competing analysis |
| 6.9 Billion | 2020 | 2030 | 5.6% | Global formalin, percentage and application segmentation | A competing analysis |
| 10.75 Billion | 2025 | 2033 | 5.43% | Global formalin, all concentrations | A competing analysis |
Our analysis suggests the 7.57 Billion (2022) figure is the most defensible base because it is anchored to a specific base year and a transparent CAGR. The 11.7 Billion endpoint is arithmetically consistent with a 2020 base of 6.9 Billion and a 5.6% CAGR; it is not directly comparable to 2030 forecasts from a 2022 base. Buyers should normalize to a single base year before comparing vendor projections.
The formalin market segments by concentration band and by end-use application. Concentration bands map to distinct buying behaviors: low-concentration buyers are price-sensitive commodity purchasers; high-concentration buyers are technically demanding industrial accounts.
| Parent segment | Children |
|---|---|
| By Percentage | 1.0%–20.0%, 20.0%–40.0%, 40.0%–60.0% |
| By Application | Automotive, Drugs, Dyes, Fertilizer, Antiseptic Perfume, Rubber Chemicals, Others |
Across both published data sets, the 1.0%–20.0% band holds the largest revenue share, driven by drugs and fertilizer applications where milder, cost-effective solutions suffice. Fertilizer was the largest application in 2020 per one analysis, while automotive and drugs show strong forecast momentum in others. This divergence reflects differing base-year compositions rather than genuine contradiction.
Asia-Pacific leads the global formalin market with an estimated 42% revenue share, underpinned by large-scale fertilizer, dye and pharmaceutical production in China and India.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.42% |
| North America | 0.21% |
| Europe | 0.19% |
| South America | 0.09% |
| Middle East & Africa | 0.09% |
| Parent | Children |
|---|---|
| Asia-Pacific | China, Japan, India, South Korea, Australia, Rest of Asia-Pacific |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Russia, Spain, Rest of Europe |
| South America | Brazil, Argentina, Colombia, Peru, Chile |
| Middle East & Africa | Saudi Arabia, UAE, Turkey, Egypt, South Africa |
Asia-Pacific's leadership rests on three structural advantages: integrated methanol and urea feedstock availability, lower conversion costs, and proximity to fast-growing end-use demand. Our analysis suggests the region will also deliver the highest incremental volume to 2030, though growth will be uneven across countries as environmental enforcement tightens in China.
Demand from fertilizers, drugs, automotive composites and personal care underpins formalin growth, while carcinogen classification and tightening emission rules cap the upside in mature markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising agricultural productivity needs | Driver | High | Soil fumigation and fertilizer demand scale with food output |
| Automotive lightweighting | Driver | Medium-high | Urea- and melamine-formaldehyde resins bond interior panels and laminates |
| Drug R&D and histopathology | Driver | High | Tissue fixation is integral to toxicology and preclinical studies |
| Cosmetics and personal care preservatives | Driver | Medium | Biocide function extends shelf life of water-based formulations |
| Group 1 carcinogen classification | Restraint | High | Triggers labeling, exposure limits and substitution pressure |
| Stringent emission and handling rules | Restraint | High | Raises compliance cost and slows new capacity approvals |
Our analysis suggests the balance is net-positive but narrowing. Growth will increasingly concentrate in Asia-Pacific and in applications where formalin has no cost-equivalent substitute, such as tissue fixation and certain rubber chemicals. In Europe and North America, substitution risk is real but slow because qualified alternatives carry re-validation costs.
The formalin market is moderately concentrated, with integrated chemical majors competing alongside regional specialists and formalin-focused producers.
| Company | Profile | Differentiation |
|---|---|---|
| BASF SE | Integrated chemical major | Feedstock integration and global distribution |
| Celanese Corporation | Acetyl chain producer | Low-cost methanol integration |
| DuPont de Nemours | Specialty chemicals | Industrial and healthcare applications |
| Georgia-Pacific (Koch) | Resins and building products | Captive downstream resin demand |
| Huntsman Corporation | Performance chemicals | Formaldehyde-based specialty intermediates |
| Merck KGaA | Life science and lab | Analytical and lab-grade formalin |
| Sumitomo Chemical | Integrated chemical producer | Asia-Pacific scale and feedstock access |
| Balaji Formalin | Formalin specialist | Regional cost leadership in India |
Competitive moats rest on feedstock integration and regulatory standing rather than brand. Our analysis suggests specialists without captive methanol or resin demand will face margin compression as compliance costs rise and low-cost Asian capacity expands.
Procurement strategy should anchor on regulatory confidence, not unit price. Formaldehyde's Group 1 carcinogen status means buyers carry downstream liability for supplier handling, labeling and transport compliance.
Key selection criteria include documented REACH and TSCA compliance, occupational exposure controls, leak-resistant packaging and lot-level traceability. Switching costs are moderate for commodity grades but high for lab-grade and histology applications, where re-validation of fixation protocols is required. Operators should also model freight costs for 37–40% solutions, as water content makes long-distance shipping uneconomic beyond regional supply basins.
The balance of evidence favors a constructive but selective outlook for the formalin market. A 5.4% CAGR to 2030 is achievable, but the composition of growth will shift decisively toward Asia-Pacific and toward applications with no qualified substitute. The strongest counter-argument is regulatory: if the EU or US tighten formaldehyde exposure limits further, substitution in construction and cosmetics could accelerate faster than forecast.
What would change this conclusion: evidence of a faster-than-expected regulatory substitution in Europe, or a sustained methanol price shock that compresses specialist producer margins below reinvestment levels. Our regional share estimates are consensus-derived; precise country-level forecasting requires the full segmentation model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
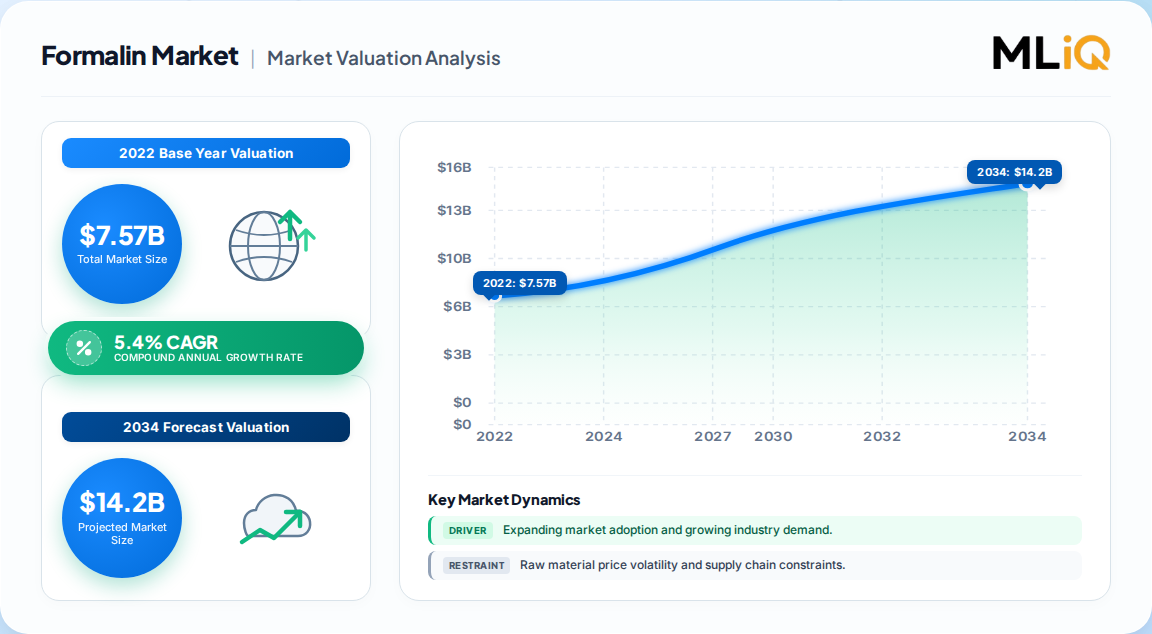
| Growth Rate | CAGR of 5.4% from 2020-2034 |
| Segmentation |
|
The global formalin market was valued at approximately 7.57 Billion in 2022. It is forecast to reach roughly 10.3 Billion by 2030 at a CAGR of about 5.4%, depending on base year normalization.
Published forecasts cluster between 5.22% and 5.6% CAGR through 2030. The most defensible midpoint is approximately 5.4%, consistent with a 2022 base of 7.57 Billion growing to 10.3 Billion.
Asia-Pacific leads with an estimated 42% revenue share, supported by fertilizer, dye and pharmaceutical production in China and India. North America and Europe follow at roughly 21% and 19% respectively.
Key applications include fertilizers, drugs, automotive composites, dyes, rubber chemicals, antiseptic perfume and other industrial uses. Fertilizer and drugs are the largest volume applications globally.
Leading producers include BASF SE, Celanese Corporation, DuPont, Georgia-Pacific, Huntsman, Merck KGaA and Sumitomo Chemical. Regional specialists such as Balaji Formalin compete on cost in local markets.
Formaldehyde is classified as a Group 1 carcinogen by the International Agency for Research on Cancer. Stricter labeling, exposure limits and substitution pressure in construction and cosmetics constrain growth in mature markets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research process applies a 70/30 split between primary and secondary evidence. In-depth interviews were conducted with stakeholders across the formalin value chain, including methanol and urea feedstock suppliers, specialized formalin producers, contract formulators and blenders, and regional industrial distributors. Interviewees were drawn from decision-maker functions including VP-level Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads. This fieldwork grounds our supply-side capacity estimates and demand-side consumption assumptions in operational reality rather than desk extrapolation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Feedstock & Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
Secondary validation draws on official multilateral databases including UN Comtrade, WTO trade statistics, US ITC data and Eurostat chemical trade reporting. Corporate annual filings, 10-K submissions and investor presentations inform capacity and revenue baselines. Patent databases and technical standards published by recognized industry associations were reviewed to map substitution risk and product innovation.
We run simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic industrial output to formalin-consuming segments using published input-output relationships. The bottom-up model builds from manufacturer capacity, realized pricing and end-use consumption rates by region. Divergences between the two are reconciled against trade flow data before final projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |