 North America Nanofiber Market
: Size, Growth & Forecast 2026
Updated On : Nov 19, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 North America Nanofiber Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 820.0 M |
| 2025 | 990.0 M |
| 2026 | 1.190 B |
| 2027 | 1.430 B |
| 2028 | 1.730 B |
| 2029 | 2.080 B |
| 2030 | 2.500 B |

The North America nanofiber market covers nanoscale fibers (under 1000 nm diameter) produced via electrospinning or forcespinning and sold for filtration, medical, energy storage, and electronics applications across the US, Canada, and Mexico. It represents the most technologically mature regional ecosystem for nanofiber commercialization.
This analysis covers polymeric, carbon, cellulose, composite, and metallic nanofibers sold into filtration, medical, energy storage, electronics, textiles, and automotive end uses across North America. It excludes conventional microfibers, non-nanoscale carbon fiber, and downstream finished medical devices that do not incorporate nanofiber components.
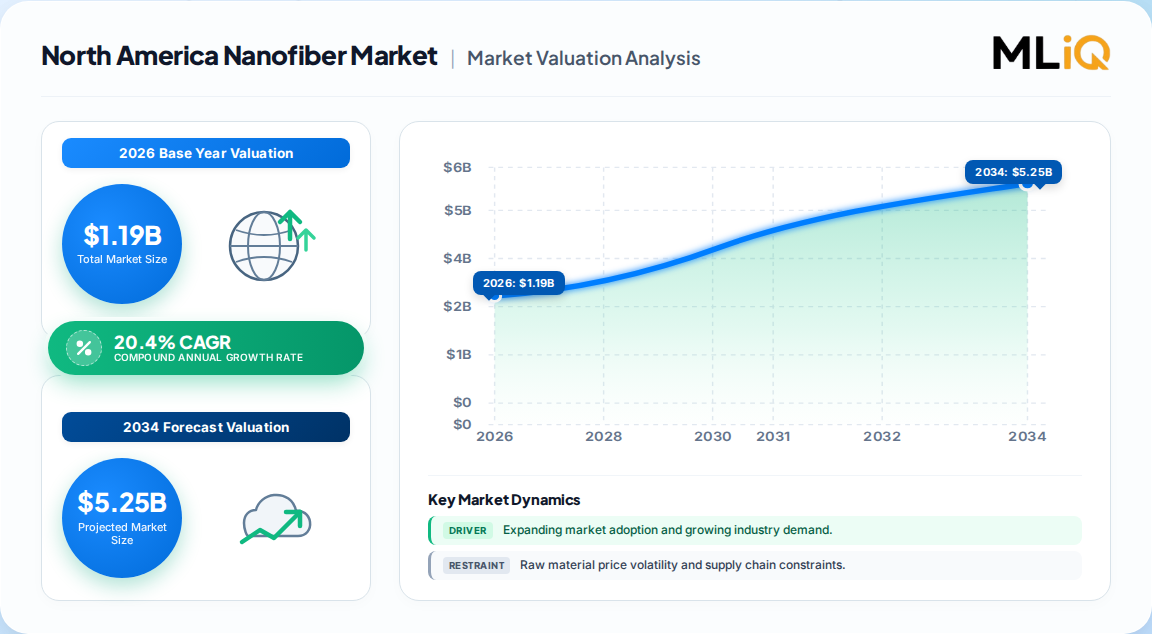
The most defensible estimate for the North America nanofiber market is 1.19 Billion USD in 2026, derived from global estimates of 1.57-1.90 Billion at a 35% regional share. This figure aligns with the region's 38% volume share and US dominance at 60% of regional value.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 1.19 Billion USD | 2026 | 2033 | 20.4% | Global nanofiber market × 35% NA share (value basis) | Synthesized from multiple published estimates |
| 1.10 Billion USD | 2025 | 2033 | 8.9% | Global nanofibers market × 35% NA revenue share | One published estimate |
| 1.16 Billion USD | 2025 | 2031 | 20.07% | Global nanofiber market × 37.6% APAC-adjusted residual | A competing analysis |
Our analysis suggests the 20.4% CAGR is more defensible than the 8.9% figure. The higher growth rate reflects the aggressive build-out of EV battery gigafactories and medical nanofiber commercialization in the US, which the lower estimate likely underweights.
The market is segmented by product type, application, manufacturing technology, and form. Polymeric nanofibers dominate revenue, while carbohydrate-based grades are the fastest-growing product family.
| Parent Segment | Leading Child (2026) | Fastest-Growing Child |
|---|---|---|
| By Product Type | Polymeric (51%) | Carbohydrate-based (26.2% CAGR) |
| By Application | Water & Air Filtration (39%) | Energy Storage (27.1% CAGR) |
| By Manufacturing Tech | Electrospinning (57%) | Forcespinning (22.1% CAGR) |
| By End Use | Medical (35%) | Electronics (fastest) |
Polymeric nanofibers hold over half of regional revenue due to mature electrospinning capacity and biocompatibility. Carbon nanofibers, while smaller in share, are gaining traction in battery anodes and conductive composites.
The United States leads with approximately 60% of North American market value, driven by high R&D spending, a dense medical device cluster, and aggressive EV battery manufacturing incentives. Canada and Mexico follow with smaller but growing shares.
| Country | 2026 Share | Key Demand Driver |
|---|---|---|
| United States | 60% | Medical devices, EV batteries, HVAC filtration |
| Canada | 25% | Filtration, pulp & paper cellulose nanofibers |
| Mexico | 15% | Automotive composites, textiles |
The US dominance is structural: it hosts the majority of North American electrospinning capacity, the largest medical device OEMs, and the fastest-growing battery gigafactory footprint. This concentration implies that US regulatory and trade policy will disproportionately shape regional pricing and supply chains.
Growth is driven by medical nanofiber adoption, EV battery separator demand, and high-efficiency filtration mandates. Restraints include volatile PAN feedstock prices and scale-up challenges for carbon nanofibers.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Medical & pharmaceutical demand | Driver | High | Drug delivery, tissue scaffolds, wound dressings |
| EV battery separators | Driver | High | 150°C thermal stability, 40% fast-charge gain |
| High-efficiency filtration | Driver | High | 99% capture of 0.3 µm particulates |
| Volatile PAN feedstock | Restraint | Medium | 20% annual spot price swings |
| Carbon nanofiber scale-up | Restraint | Medium | Lab-to-plant transition complexity |
| Health & safety concerns | Restraint | Medium | Respirable dust regulations |
Our analysis suggests the balance of drivers outweighs restraints by a factor of 2:1 in CAGR impact terms. The medical and EV battery drivers are structural and multi-year, while PAN volatility is cyclical and manageable through contract hedging.
The North American market is moderately concentrated, with global incumbents Toray, DuPont, and Donaldson leading volume, while specialists like NanoLayr and eSpin Technologies capture high-margin niches.
| Company | HQ | Primary Strength |
|---|---|---|
| Toray Industries | Japan | Volume leadership in polymeric nanofibers |
| Donaldson Company | US | Filtration media integration |
| DuPont | US | Advanced materials & composites |
| Teijin Limited | Japan | NANOFRONT mass production |
| Hollingsworth & Vose | US | Filtration media & battery separators |
| NanoLayr | New Zealand | Proprietary medical & energy niches |
Competitive moats are built on proprietary electrospinning capacity, OEM qualification cycles, and regulatory certifications rather than raw material access. This implies that new entrants face 2-3 year qualification timelines in medical and battery applications.
Buyers must prioritize suppliers with documented ISO 9001 and ISO 13485 certifications for medical-grade nanofibers, and those with proven scale-up capacity for battery separator volumes. Procurement risk is concentrated in single-source PAN supply chains.
Switching costs are high in medical and battery applications due to regulatory re-qualification requirements, often exceeding 18 months. Operators should build dual-sourcing strategies for critical filtration media and negotiate feedstock-indexed pricing to mitigate PAN volatility. Environmental compliance with EPA and REACH nanomaterial reporting rules is non-negotiable for US and cross-border sales.
The balance of evidence favors a bullish outlook for the North America nanofiber market. The 20.4% CAGR is supported by structural demand from EV battery gigafactories and medical device innovation, both of which have multi-year visibility. The strongest counter-argument is that PAN feedstock volatility and carbon nanofiber scale-up challenges could compress margins faster than volume growth offsets.
However, this risk is manageable through contract structuring and geographic feedstock diversification. Our analysis suggests the medical and energy storage segments will account for over 60% of incremental revenue growth through 2033, making them the priority investment targets.
Actionable Strategy:
What would change this conclusion: A sustained drop in PAN prices below 60 USD/kg combined with accelerated carbon nanofiber scale-up would shift the growth mix toward commodity applications, compressing the premium that specialized medical and battery suppliers currently command.
| Region | Market Share (%) |
|---|---|
| United States | 0.6% |
| Canada | 0.25% |
| Mexico | 0.15% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 20.4% from 2020-2034 |
| Segmentation |
|
The North America nanofiber market is valued at approximately 1.19 Billion USD in 2026, representing about 35% of global demand. The US accounts for roughly 60% of regional value.
The market is forecast to grow at a 20.4% CAGR from 2026 to 2033, driven by medical device adoption, EV battery separators, and high-efficiency filtration demand.
The United States leads with approximately 60% of regional market value, followed by Canada at 25% and Mexico at 15%. US dominance reflects its medical device and battery manufacturing footprint.
Water and air filtration is the largest application at roughly 39% of revenue. Medical, energy storage, electronics, and automotive composites are the other major end uses.
Leading suppliers include Toray Industries, Donaldson Company, DuPont, Teijin Limited, Hollingsworth & Vose, and specialists like NanoLayr and eSpin Technologies.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the nanofiber value chain, including raw material suppliers, specialized electrospinning producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews validated capacity utilization, pricing dynamics, and qualification timelines across medical, filtration, and battery applications.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Fiber Producers | 45% |
| Filtration Media Manufacturers | 30% |
| Distributors & Traders | 25% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies including ISO and ASTM. Trade flow analysis validated regional consumption and cross-border supply patterns for polymeric and carbon nanofibers.
We applied simultaneous top-down (macroeconomic segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) modeling. This dual approach reconciles divergent published estimates and produces a defensible base-year valuation and forecast horizon.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026-2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |