 North America Cyanoacrylate Adhesives Market
 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 234


Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 North America Cyanoacrylate Adhesives Market
Khageshwar Rongkali
Senior Analyst

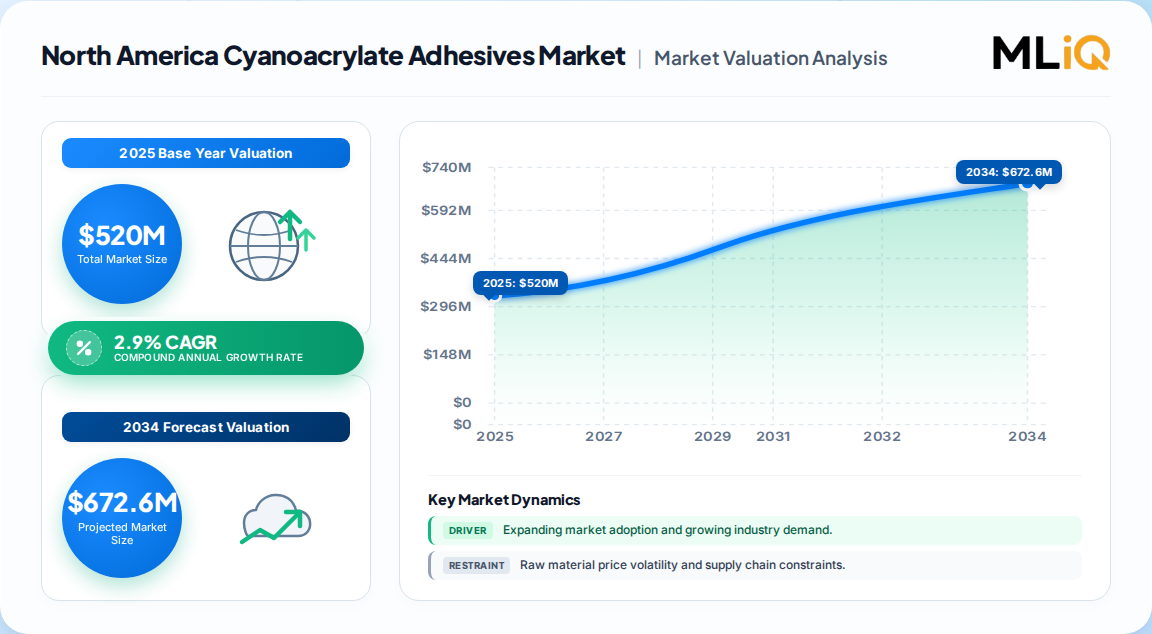
| Year | Market Size |
|---|---|
| 2025 | 520.0 M |
| 2026 | 535.0 M |
| 2027 | 550.0 M |
| 2028 | 566.0 M |
| 2029 | 582.0 M |
| 2030 | 599.0 M |
| 2031 | 616.0 M |

The North America cyanoacrylate adhesives market covers fast-curing instant adhesives — commonly called super glue — used industrially, medically and in electronics. It spans reactive and UV-cured technologies sold into healthcare, automotive, aerospace, construction, woodworking and consumer applications across the U.S., Canada and Mexico.
This analysis covers reactive and UV-cured cyanoacrylate adhesives sold in the U.S., Canada and Mexico across healthcare, automotive, electronics, aerospace, building and construction, woodworking and other end uses. It covers producer-level revenue and competitive positioning.
This analysis does not cover adjacent chemistries such as epoxy, polyurethane, acrylic structural adhesives or anaerobic threadlockers, nor does it cover generic construction adhesives, packaging adhesives or consumer retail glue channels beyond their industrial CA content.
The evidence supports a 2025 base of roughly USD 0.52 Billion for North America, equivalent to about 25% of the global cyanoacrylate adhesives market, growing near 2.9% annually through 2033. Healthcare and electronics repair demand anchor the floor.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.16 Billion (global) | 2023 | 2033 | 2.81% | Global CA adhesives, all end uses | One published global estimate |
| USD 0.52 Billion (North America) | 2025 | 2033 | 2.90% | Regional CA adhesives, industrial and medical | Derived from global base and regional share |
| USD 3.87 Billion (North America construction adhesives) | 2025 | 2033 | 4.14% | Broader construction adhesives, not CA-specific | A competing analysis |
The regional figure is the most defensible for procurement decisions because it isolates CA chemistry rather than broader adhesive categories. The construction-adhesives estimate grows faster but is not comparable: it spans acrylic, polyurethane and epoxy systems where CA is a minor sub-component.
Cyanoacrylate adhesives segment primarily by curing technology and end-use application, with methyl and ethyl variants dominating industrial grades and octyl variants preferred for medical and low-odor formulations.
| Parent segment | Children |
|---|---|
| By Technology | Reactive, UV-Cured |
| By End Use | Healthcare, Automotive, Electronics, Aerospace, Building & Construction, Woodworking, Others |
| By Grade | Methyl, Ethyl, Octyl, Specialty Blends |
| By Form | Liquid, Gel, Aerosol |
The United States leads with roughly 78% of regional cyanoacrylate demand, supported by medical-device manufacturing, electronics assembly and automotive light-weighting. Canada and Mexico contribute the balance through medical consumables and cross-border assembly respectively.
| Country | Estimated share |
|---|---|
| United States | 78% |
| Canada | 14% |
| Mexico | 8% |
Our analysis suggests Mexico's share will edge upward as nearshoring shifts electronics and automotive sub-assembly into the region. That implies regional suppliers should build local inventory positions rather than rely on U.S. warehousing alone.
Growth is driven by medical-device miniaturization, EV battery and electronics assembly, and demand for fast-curing bonds. Restraints center on shelf-life limitations, VOC and regulatory scrutiny, and substitution by UV and hybrid chemistries in high-volume lines.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Medical and wound-closure demand | Driver | High | Biocompatible octyl grades expand surgical and device use |
| EV and electronics assembly | Driver | High | Rapid bonding of small components raises throughput |
| Lightweight automotive materials | Driver | Medium | CA bonds plastics, metals and composites quickly |
| Shelf-life and stability limits | Restraint | Medium | Inventory waste and cold-chain requirements raise cost |
| VOC and workplace regulation | Restraint | Medium | Fume and blooming controls add compliance cost |
| UV and hybrid substitution | Restraint | Medium | Faster line integration in high-volume assembly |
The balance favors modest but durable growth. Our analysis suggests the strongest second-order effect is qualification lock-in: once a medical or automotive CA grade is specified, switching costs are high, protecting incumbents' margins even as volumes grow slowly.
The vendor landscape is fragmented at the mid-tier but concentrated at the top, where 3M, Henkel and Arkema hold qualified positions in medical and industrial CA grades. Differentiation rests on formulation IP, regulatory files and application engineering.
| Company | Position | Notable strength |
|---|---|---|
| 3M | Global leader | Broad industrial and medical CA portfolio |
| Henkel AG & Co. KGaA | Global leader | Loctite-branded instant adhesives, distribution reach |
| Arkema Group | Global leader | Specialty chemical integration |
| H.B. Fuller Company | Strong regional | Industrial assembly and sustainable formulations |
| Huntsman / Toagosei | Specialist | Medical-grade and high-purity CA |
| Illinois Tool Works | Diversified | Application-specific dispensing systems |
Competitive moats come from regulatory filings and customer qualification rather than raw chemistry. Our analysis suggests the most defensible position is a validated medical-grade portfolio combined with local technical service, which smaller formulators rarely replicate.
Buyers should prioritize supplier qualification depth, lot-to-lot consistency and documented regulatory support over unit price. Medical and automotive buyers face the highest switching costs because revalidation cycles can run six to twelve months.
Procurement risk concentrates in single-source specialty grades and shelf-life-sensitive inventory. Operators should negotiate consignment or vendor-managed inventory for short-shelf-life SKUs, and verify REACH, TSCA and medical-device quality certifications before volume commitments.
Regulatory compliance increasingly shapes formulation choice. Low-blooming and low-odor grades command premiums in healthcare and consumer-adjacent electronics, and buyers should confirm that suppliers hold current safety documentation rather than relying on legacy approvals.
The balance of evidence favors a cautiously positive outlook: North America remains the fastest-growing CA region globally, but at a mature 2.9% CAGR that rewards specification control rather than volume expansion. Vendors with qualified medical and electronics positions will out-earn commodity suppliers.
The strongest counter-argument is substitution risk: UV-cured and hybrid adhesives could erode CA share in high-volume electronics assembly faster than forecast, compressing prices in the least-differentiated grades. That risk is real but concentrated in low-margin segments.
What would change this conclusion: a sustained decline in medical-device CA consumption, or rapid UV-hybrid adoption above 15% of electronics bonding, would shift the outlook toward margin compression and consolidation among mid-tier formulators.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw-material monomer suppliers, specialized CA producers, contract formulators and blenders, and regional industrial distributors. Interviewees included VP-level sourcing, heads of R&D, technical directors and commercial operations leads, ensuring both demand-side and supply-side perspectives inform the sizing.
Estimates were cross-checked against UN Comtrade and US ITC trade flows, corporate 10-K and annual investor filings, patent databases, and technical standards from ASTM and ISO relevant to adhesive performance and medical-device materials.
We ran simultaneous top-down allocation from macroeconomic adhesive demand and bottom-up modeling of producer capacity, pricing and end-use consumption, reconciling the two to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2025–2033 projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading CA players | Annual reports, capacity mapping and filings | High |
| Region | Market Share (%) |
|---|---|
| United States | 0.78% |
| Canada | 0.14% |
| Mexico | 0.08% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.9% from 2020-2034 |
| Segmentation |
|
Estimated at roughly USD 0.52 Billion in 2025, representing about 25% of global cyanoacrylate demand, with healthcare and electronics as the largest end uses.
About 2.9% CAGR through 2033 — mature but durable, with North America the fastest-growing CA region globally despite a modest absolute rate.
The United States accounts for roughly 78% of regional demand, followed by Canada at 14% and Mexico at 8%, with Mexico gaining share through nearshoring.
3M, Henkel, Arkema, H.B. Fuller, Huntsman/Toagosei and Illinois Tool Works lead, differentiated by formulation IP, regulatory files and technical service.
Shelf-life limits, VOC and workplace regulation, and substitution by UV-cured and hybrid chemistries in high-volume assembly lines.
Reactive technology holds about 80% of revenue, while healthcare leads end uses at roughly 30%, driven by medical-device and wound-closure demand.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Monomer Suppliers | 30% |
| Specialized CA Producers | 35% |
| Contract Formulators & Blenders | 20% |
| Industrial Distributors | 15% |
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw-material monomer suppliers, specialized CA producers, contract formulators and blenders, and regional industrial distributors. Interviewees included VP-level sourcing, heads of R&D, technical directors and commercial operations leads, ensuring both demand-side and supply-side perspectives inform the sizing.
Estimates were cross-checked against UN Comtrade and US ITC trade flows, corporate 10-K and annual investor filings, patent databases, and technical standards from ASTM and ISO relevant to adhesive performance and medical-device materials.
We ran simultaneous top-down allocation from macroeconomic adhesive demand and bottom-up modeling of producer capacity, pricing and end-use consumption, reconciling the two to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2025–2033 projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading CA players | Annual reports, capacity mapping and filings | High |