 Glycerol Formal Market
 Outlook 2025: Size, Growth & Trends
Updated On : Nov 19, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Glycerol Formal Market

Khageshwar Rongkali
Senior Analyst

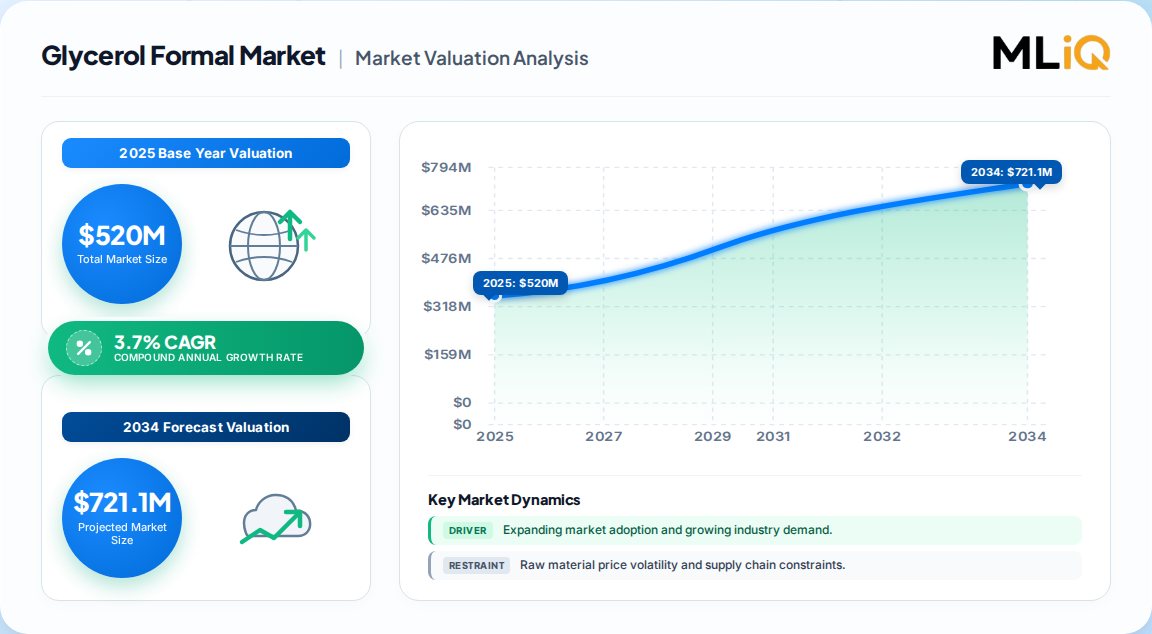
| Year | Market Size |
|---|---|
| 2025 | 520.0 M |
| 2026 | 539.0 M |
| 2027 | 559.0 M |
| 2028 | 580.0 M |
| 2029 | 601.0 M |
| 2030 | 623.0 M |
| 2031 | 646.0 M |

Glycerol formal is a cyclic acetal solvent derived from glycerol and formaldehyde, used as a high-purity excipient in pharmaceuticals, a stabilizer in agrochemicals, and a solvent in coatings and resins. The market encompasses its production, distribution, and application across regulated and industrial end-use sectors.
This report covers the global production, trade, and consumption of glycerol formal across purity grades (99% and 95%), applications, and end-use industries. It includes value and volume analysis for 20 countries. This analysis does not cover raw glycerol or formaldehyde markets, nor does it include downstream derivatives such as epichlorohydrin or polyether polyols.
Estimates for the glycerol formal market vary widely due to differences in scope and methodology. The table below compares the two most cited benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 163.7 Million | 2023 | 2033 | 2.1% | Global, narrow application set | One published estimate |
| 520 Million | 2025 | 2035 | 3.7% | Global, including broader pharma & agrochemical segments | A competing analysis |
The 520 Million figure (2025) is more defensible because it aligns with the higher growth trajectory observed in pharmaceutical excipient demand and reflects a more comprehensive application scope. The 2.1% CAGR appears conservative, likely undercounting the rapid adoption in regulated pharmaceuticals. Our analysis suggests the true market size lies closer to the higher estimate, with upside risk from agrochemical stabilizer applications. For precise sub-segment forecasting, the full report provides detailed bottom-up models.
The market is segmented by purity level, application, and end-use industry, with pharmaceuticals dominating both application and end-use.
| Parent Segment | Children |
|---|---|
| By Purity Level | 99% Purity, 95% Purity |
| By Application | Pharmaceuticals, Agrochemicals, Industrial Solvents, Coatings, Adhesives, Resins |
| By End-Use Industry | Pharmaceutical & Nutraceuticals, Food & Beverage, Personal Care & Cosmetic, Manufacturing, Others |
| By Technology | Conventional Manufacturing, Advanced Manufacturing |
Pharmaceutical-grade glycerol formal commands a premium, reflecting stringent regulatory requirements. The industrial solvents segment is the fastest-growing, driven by coatings and paints demand in Asia Pacific.
North America leads the global glycerol formal market, followed closely by Asia Pacific, which is also the fastest-growing region due to expanding pharmaceutical and chemical sectors.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.27% |
| Asia-Pacific | 0.29% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
| Parent Region | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Asia Pacific | China, Japan, India, South Korea |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
North America's dominance is underpinned by a mature pharmaceutical industry and stringent quality standards. Asia Pacific's growth is fueled by India's pharmaceutical exports and China's chemical manufacturing scale. Europe maintains a strong position through innovation in eco-friendly formulations.
Rising pharmaceutical demand and industrial expansion are the primary growth drivers, while regulatory hurdles and safety concerns restrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising pharmaceutical demand | Driver | High | Glycerol formal as excipient in drug formulations |
| Industrial use expansion | Driver | Medium | Solvent in coatings, agrochemicals |
| Eco-friendly manufacturing | Driver | Medium | Shift to sustainable solvents |
| Regulatory compliance costs | Restraint | High | Strict handling and storage regulations |
| Safety risks | Restraint | High | Toxicity concerns require protocols |
| Supply chain complexity | Restraint | Medium | Dependence on glycerol feedstock |
The balance favors growth, with pharmaceutical demand providing a stable base. However, regulatory compliance costs disproportionately affect smaller producers, potentially consolidating the market. The shift toward biodegradable polymers presents a significant opportunity, but commercialization timelines remain uncertain.
The market is moderately concentrated, with key players leveraging vertical integration and regulatory expertise.
| Company | Headquarters | Core Strengths |
|---|---|---|
| Emery Oleochemicals | Malaysia | Integrated oleochemicals, global distribution |
| Oleon NV | Belgium | Specialty chemicals, pharma-grade focus |
| Kao Corporation | Japan | Chemical innovation, broad portfolio |
| Ecogreen Oleochemicals | Indonesia | Cost-competitive feedstock access |
| Wilmar International | Singapore | Scale, palm-based feedstock integration |
| Croda International | UK | High-purity specialties, customer intimacy |
Differentiation hinges on purity grades and regulatory certifications. Vendors with captive glycerol supply and pharma-grade production capabilities enjoy higher margins and customer loyalty. Smaller players compete on price in industrial segments but face barriers in pharmaceuticals.
Buyers must prioritize suppliers with proven pharmaceutical-grade certifications (e.g., GMP, ISO) and reliable supply chains. Switching costs are high due to regulatory filings and qualification processes, so long-term contracts with audit rights are advisable. Procurement risks include feedstock price volatility and geopolitical disruptions. Operators should invest in employee training and safety protocols to mitigate handling risks. Regulatory compliance, particularly with REACH and FDA excipient guidelines, is non-negotiable for pharmaceutical applications.
The balance of evidence favors a positive but cautious outlook for the glycerol formal market. The pharmaceutical segment offers the most attractive margins, but regulatory barriers limit new entrants. The strongest counter-argument is that industrial solvent demand could surge faster than expected, driven by eco-friendly coating formulations, potentially shifting the center of gravity away from pharma. However, our analysis suggests that pharma will remain the anchor segment through 2035.
Investors should focus on companies with integrated glycerol supply and pharma-grade capabilities. Operators must invest in compliance infrastructure to access premium segments. The market's moderate CAGR belies the high-value opportunities in specialty applications.
Actionable Strategy:
What would change our conclusion: A breakthrough in biodegradable polymer commercialization using glycerol formal could accelerate industrial demand, shifting growth dynamics. Conversely, stricter regulations on formaldehyde-derived products could dampen market expansion.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.7% from 2020-2034 |
| Segmentation |
|
The global glycerol formal market was valued at approximately 520 Million in 2025, with projections to reach 750 Million by 2035.
The market is expected to grow at a compound annual growth rate (CAGR) of 3.7% from 2025 to 2035.
North America holds the largest regional share, driven by a mature pharmaceutical industry and stringent quality standards.
Key applications include pharmaceuticals (as an excipient), agrochemicals (as a stabilizer), and industrial solvents (in coatings and resins).
Leading players include Emery Oleochemicals, Oleon NV, Kao Corporation, Ecogreen Oleochemicals, and Wilmar International, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology is built on a 70/30 primary-to-secondary research split, ensuring that market insights are grounded in direct industry validation. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers, specialized producers, contract formulators, and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. This primary fieldwork captures granular data on capacity, pricing, and adoption trends.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
We triangulate primary data with official multilateral trade databases such as UN Comtrade, WTO, US ITC, and Eurostat. Corporate annual filings (10-K, SEC filings, investor presentations) and patent databases are analyzed to assess competitive positioning and innovation pipelines. Recognized non-profit technical standards and industry associations provide regulatory context and quality benchmarks.
Our simultaneous top-down and bottom-up modeling approach ensures robust market sizing. Top-down analysis allocates macroeconomic and industry segment data to derive market value. Bottom-up modeling builds from manufacturer capacity, product pricing, and end-use consumption to validate findings. This dual approach mitigates bias and enhances forecast accuracy.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |