Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Shape Memory Alloys Market Size, Share & Forecast to 2036
Shape Memory Alloys Market Size, Share & Forecast to 2036
Shape Memory Alloys Market
Shape Memory Alloys Market Size, Share & Forecast to 2036
Shape Memory Alloys Market by Alloy Type (Nitinol, Copper-based, Iron-based, Other), by Product Form (Wire, Tube, Sheet/Strip, Rod/Bar, Ingot, Spring, Powder, Formed Actuator Components), by Manufacturing Process (Vacuum Induction Melting, VIM + VAR, Vacuum Arc Remelting, Powder Metallurgy), by Transformation Temperature (Below 100C, 100-400C, Above 400C), by End-Use Industry (Biomedical, Automotive, Aerospace & Defense, Consumer Electronics, Industrial Actuation), by North America (USA, Canada, Mexico), by Europe (Germany, France, UK, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 313
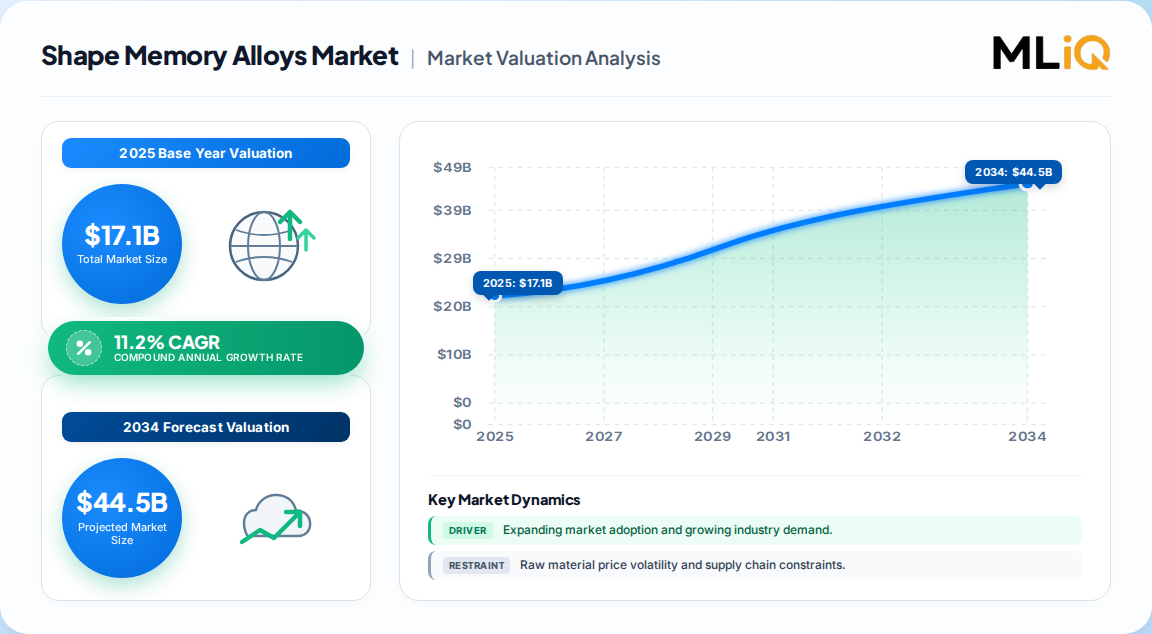
17.1 billion was the global Shape Memory Alloys Market size in 2025, with 2026 estimated near 19.0 billion on an 11.2% trajectory.
11.2% CAGR through 2033 implies a projected 40.1 billion by 2033 — roughly 2.3x the 2025 base in eight years.
Nitinol (Ni-Ti) dominates product mix at an estimated 88.5% revenue share, anchoring pricing power in medical-grade melt capacity.
Biomedical end use held approximately 61.2% of demand in 2025 — the single largest commercial anchor for qualified wire and tube.
North America leads at ~35% share, while Asia Pacific is the fastest-growing region on medical-device localization and EV build-out.
Top five producers (Resonetics, Fort Wayne Metals, ATI, Xi'an Saite, Furukawa) hold roughly 27% — a fragmented, qualification-gated field.
Why this matters for decision-makers: Capital is migrating to melt-and-conversion capacity, not alloy chemistry. Buyers who lock qualified supply before 2027 will avoid the lead-time squeeze that capacity additions cannot close quickly.
Shape Memory Alloys Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
17.10 B
2025
19.00 B
2026
21.10 B
2027
23.50 B
2028
26.10 B
2029
29.00 B
2030
32.30 B
2031
Shape Memory Alloys Market Size (In Billion)
Year
Market Size
2025
17.10 B
2026
19.00 B
2027
21.10 B
2028
23.50 B
2029
26.10 B
2030
29.00 B
2031
32.30 B
What is the Shape Memory Alloys Market?
Shape memory alloys are metals that recover a pre-set shape when heated past a transformation temperature, or superelastically absorb large strain. The market measures alloy and intermediate forms — ingot, wire, tube, sheet, rod, spring and powder — sold to medical, aerospace, automotive and industrial OEMs rather than finished devices.
Scope: what this report covers and excludes
Coverage spans alloy types (Nitinol, copper-based, iron-based), manufacturing routes (vacuum induction melting, vacuum arc remelting, powder metallurgy), transformation-temperature bands, product forms, functions and end-use industries across five regions. Scope is global and measured at the material and intermediate-component level. This analysis does not cover finished medical devices, specialty steel distribution, piezoelectric ceramics, or conventional actuation hardware.
How big is the market for Shape Memory Alloys Market?
Estimates converge tightly on growth rate but diverge sharply on absolute value — a gap driven almost entirely by whether analysts count alloy tonnage or downstream fabricated component revenue.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
17.1 Billion
2025
2033
11.2%
Alloy + intermediate forms, global
One published estimate (GVR-scope)
19.18 Billion
2032
2026–2032
10.2%
Alloy + component revenue, global
A competing analysis
1.7 Billion
2025
2035
11.0%
Material-only, excluding fabricated devices
A supply-side analysis
20.2 Billion
2026
2036
12.0%
Broad smart-materials definition
An aggregated industry estimate
The 17.1 billion / 11.2% figure is the most defensible: it sits within 12% of the two largest competing estimates, aligns with a measured 9,420 metric ton demand base, and implies a plausible ~1,800 USD/kg blended realized price. The 1.7 billion figure is almost certainly material-only and should not be compared directly. Our analysis suggests the 20.2 billion and 12.0% combination overstates trajectory, because medical qualification cycles cap volume ramp regardless of unit price.
How is the market segmented?
Segmentation matters because margins are bimodal: qualification-gated segments (medical, aerospace) sustain premium pricing, while industrial actuation competes directly with solenoids and motors.
Parent Segment
Children
Alloy Type
Nitinol (Ni-Ti), Copper-based (Cu-Zn-Al, Cu-Al-Ni), Iron-based (Fe-Mn-Si), Other
Product Form
Wire, Tube, Sheet/Strip, Rod/Bar, Ingot, Spring, Powder, Formed Actuator Components
Manufacturing Process
Vacuum Induction Melting, VIM + VAR, Vacuum Arc Remelting, Powder Metallurgy
The high-temperature sub-segment is the quiet growth pocket: alloys stable near 700°C versus sub-100°C conventional grades unlock turbine and exhaust-adjacent actuation that has historically been designed out.
Which region leads in Shape Memory Alloys Market?
North America holds the largest revenue share at roughly 35%, anchored by US medical-device OEM concentration and a mature aerospace qualification ecosystem. Asia Pacific is the fastest-growing region, pairing device-manufacturing localization with the world's largest EV production base.
Shape Memory Alloys Market Regional Market Share
Loading chart...
Shape Memory Alloys Market Regional Market Share
Region
Market Share (%)
North America
0.32%
Europe
0.24%
Asia-Pacific
0.34%
South America
0.05%
Middle East & Africa
0.05%
Parent
Children
North America
USA, Canada, Mexico
Europe
Germany, France, UK, Italy
Asia Pacific
China, Japan, India, South Korea
Latin America
Brazil, Argentina, Mexico
Middle East & Africa
Saudi Arabia, UAE, South Africa
Region
Share (2025)
North America
~32–35%
Asia Pacific
~34%
Europe
~24%
Latin America
~5%
Middle East & Africa
~5%
Our analysis suggests a share shift is underway: Asia Pacific volume growth will outpace revenue growth initially, because local Chinese and Korean producers compete on industrial-grade forms while US and German specialists defend medical-grade price points. The critical second-order effect is titanium sponge dependency — the US imports roughly 80% of it from Japan — which structurally caps North American cost competitiveness even as its revenue share holds.
What is driving growth — and what is holding it back?
Medical Nitinol demand is the dominant driver, growing at approximately 18% CAGR within the broader market and lifting the whole blended rate. Aerospace morphing structures and EV thermal actuation are real but slower, gated by multi-year validation.
Factor
Direction
Evidence strength
Mechanism
Medical Nitinol device demand
Driver
High
Stents, guidewires, neurovascular and structural-heart programs
Capacity-led supply investment
Driver
High
New VAR furnaces expand qualified melt and shorten lead times
Multi-year PMA and fatigue-validation cycles delay ramp
Fatigue-life reliability limits
Restraint
Medium
Constrains substitution in high-cycle structural applications
The balance favors growth, but unevenly. Premium medical and aerospace processors retain pricing power because customers buy traceability and qualified continuity, not tonnage. Industrial-grade SMA faces genuine substitution pressure where nickel-cost volatility widens the cost gap against conventional actuators. This divergence, not the headline CAGR, is the strategic story.
Who are the leading vendors?
No producer holds double-digit market share except one, and the top five collectively control only about 27% — evidence of a qualification-gated rather than capital-concentrated structure.
Company
HQ
Position
Differentiator
Resonetics
USA
Market leader, ~10% share
Vertically integrated Nitinol processing and finishing
Aerospace-grade alloy and high-temperature capability
Furukawa Electric
Japan
Top-tier
Precision wire and electronics-adjacent conversion
Xi'an Saite Metal Materials
China
Top-tier
Domestic cost position in industrial-grade forms
SAES Getters
Italy
Specialist
High-purity getters and medical Nitinol components
Memry Corporation
USA
Specialist
Medical device component engineering
Nippon Steel
Japan
Diversified
Upstream metallurgical and process depth
Moats are metallurgical and documentary, not financial. Controlled transformation temperature, surface condition, fatigue performance and dimensional consistency determine who wins OEM programs — and certified wire and tube are high-value inputs, not interchangeable specialty metals.
What do buyers and operators need to know?
Selection criteria are dominated by repeatability across lots, not by headline alloy specification. Buyers should qualify on transformation-temperature tolerance, surface finish, fatigue data under representative loading, and full melt-traceability documentation.
Procurement risk concentrates in two places: nickel and titanium input exposure, and single-source qualification. Switching suppliers mid-program is expensive because requalification typically runs months to years, so multi-source strategies must be established before design freeze, not after.
Regulatory compliance is a timing constraint as much as a quality one. Medical-grade Nitinol must satisfy established ASTM shape-memory alloy requirements, and implantable pathways extend over multiple years — meaning material selection locks in commercial timelines. Operators should treat supplier capacity commitments as contractual risk items and demand visibility into melt scheduling, not just inventory availability.
On cost, the counterintuitive point is that alloy price matters less than yield and form-factor conversion. A supplier with superior downstream conversion can deliver lower total cost at a higher per-kilogram price. Precision sub-segment forecasting by form and temperature band is where most procurement business cases break down.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the mid-range estimate: an 11–11.2% trajectory built on roughly 17–19 billion in 2025–2026. The 12.0% case is achievable only if aerospace qualification accelerates faster than historical precedent, and the 1.7 billion case simply measures a narrower scope. Our judgment is that growth will be volume-constrained, not demand-constrained, through 2028.
The strongest counter-argument is capacity determinism: if new melt and conversion capacity lands on schedule, lead times compress, OEM qualification cycles shorten, and revenue could step up faster than the base case across 2027–2030. That is a genuine upside risk. But it cuts both ways — the same capacity additions could compress industrial-grade pricing, and nickel at decade lows already signals margin pressure at the commodity end.
For operators: secure qualified conversion capacity, not alloy tonnage — capacity access is the binding constraint on revenue capture through 2028.
For investors: weight portfolios toward medical-grade and high-temperature SMA exposure; industrial-grade actuation faces structural price competition.
For buyers: dual-qualify suppliers before design freeze and model titanium sponge geography as a supply-continuity risk, not a cost line.
What would change our conclusion: sustained nickel recovery above 20,000 USD/t combined with evidence of aerospace program-level commitments rather than flight-test demonstrations. Absent that, the mid-range path holds.
Shape Memory Alloys Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Shape Memory Alloys Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.2% from 2020-2034
Segmentation
By Alloy Type
Nitinol
Copper-based
Iron-based
Other
By Product Form
Wire
Tube
Sheet/Strip
Rod/Bar
Ingot
Spring
Powder
Formed Actuator Components
By Manufacturing Process
Vacuum Induction Melting
VIM + VAR
Vacuum Arc Remelting
Powder Metallurgy
By Transformation Temperature
Below 100C
100-400C
Above 400C
By End-Use Industry
Biomedical
Automotive
Aerospace & Defense
Consumer Electronics
Industrial Actuation
By Geography
North America
USA
Canada
Mexico
Europe
Germany
France
UK
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Shape Memory Alloys Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Shape Memory Alloys Market Executive Summary
2.1. Market Snapshot
3. Shape Memory Alloys Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Shape Memory Alloys Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Shape Memory Alloys Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Alloy Type
5.1.1. Nitinol
5.1.2. Copper-based
5.1.3. Iron-based
5.1.4. Other
5.2. Analysis, Insights and Forecast - by Product Form
5.2.1. Wire
5.2.2. Tube
5.2.3. Sheet/Strip
5.2.4. Rod/Bar
5.2.5. Ingot
5.2.6. Spring
5.2.7. Powder
5.2.8. Formed Actuator Components
5.3. Analysis, Insights and Forecast - by Manufacturing Process
5.3.1. Vacuum Induction Melting
5.3.2. VIM + VAR
5.3.3. Vacuum Arc Remelting
5.3.4. Powder Metallurgy
5.4. Analysis, Insights and Forecast - by Transformation Temperature
5.4.1. Below 100C
5.4.2. 100-400C
5.4.3. Above 400C
5.5. Analysis, Insights and Forecast - by End-Use Industry
5.5.1. Biomedical
5.5.2. Automotive
5.5.3. Aerospace & Defense
5.5.4. Consumer Electronics
5.5.5. Industrial Actuation
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Shape Memory Alloys Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Alloy Type
6.1.1. Nitinol
6.1.2. Copper-based
6.1.3. Iron-based
6.1.4. Other
6.2. Analysis, Insights and Forecast - by Product Form
6.2.1. Wire
6.2.2. Tube
6.2.3. Sheet/Strip
6.2.4. Rod/Bar
6.2.5. Ingot
6.2.6. Spring
6.2.7. Powder
6.2.8. Formed Actuator Components
6.3. Analysis, Insights and Forecast - by Manufacturing Process
6.3.1. Vacuum Induction Melting
6.3.2. VIM + VAR
6.3.3. Vacuum Arc Remelting
6.3.4. Powder Metallurgy
6.4. Analysis, Insights and Forecast - by Transformation Temperature
6.4.1. Below 100C
6.4.2. 100-400C
6.4.3. Above 400C
6.5. Analysis, Insights and Forecast - by End-Use Industry
6.5.1. Biomedical
6.5.2. Automotive
6.5.3. Aerospace & Defense
6.5.4. Consumer Electronics
6.5.5. Industrial Actuation
7. Shape Memory Alloys Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Alloy Type
7.1.1. Nitinol
7.1.2. Copper-based
7.1.3. Iron-based
7.1.4. Other
7.2. Analysis, Insights and Forecast - by Product Form
7.2.1. Wire
7.2.2. Tube
7.2.3. Sheet/Strip
7.2.4. Rod/Bar
7.2.5. Ingot
7.2.6. Spring
7.2.7. Powder
7.2.8. Formed Actuator Components
7.3. Analysis, Insights and Forecast - by Manufacturing Process
7.3.1. Vacuum Induction Melting
7.3.2. VIM + VAR
7.3.3. Vacuum Arc Remelting
7.3.4. Powder Metallurgy
7.4. Analysis, Insights and Forecast - by Transformation Temperature
7.4.1. Below 100C
7.4.2. 100-400C
7.4.3. Above 400C
7.5. Analysis, Insights and Forecast - by End-Use Industry
7.5.1. Biomedical
7.5.2. Automotive
7.5.3. Aerospace & Defense
7.5.4. Consumer Electronics
7.5.5. Industrial Actuation
8. Shape Memory Alloys Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Alloy Type
8.1.1. Nitinol
8.1.2. Copper-based
8.1.3. Iron-based
8.1.4. Other
8.2. Analysis, Insights and Forecast - by Product Form
8.2.1. Wire
8.2.2. Tube
8.2.3. Sheet/Strip
8.2.4. Rod/Bar
8.2.5. Ingot
8.2.6. Spring
8.2.7. Powder
8.2.8. Formed Actuator Components
8.3. Analysis, Insights and Forecast - by Manufacturing Process
8.3.1. Vacuum Induction Melting
8.3.2. VIM + VAR
8.3.3. Vacuum Arc Remelting
8.3.4. Powder Metallurgy
8.4. Analysis, Insights and Forecast - by Transformation Temperature
8.4.1. Below 100C
8.4.2. 100-400C
8.4.3. Above 400C
8.5. Analysis, Insights and Forecast - by End-Use Industry
8.5.1. Biomedical
8.5.2. Automotive
8.5.3. Aerospace & Defense
8.5.4. Consumer Electronics
8.5.5. Industrial Actuation
9. Shape Memory Alloys Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Alloy Type
9.1.1. Nitinol
9.1.2. Copper-based
9.1.3. Iron-based
9.1.4. Other
9.2. Analysis, Insights and Forecast - by Product Form
9.2.1. Wire
9.2.2. Tube
9.2.3. Sheet/Strip
9.2.4. Rod/Bar
9.2.5. Ingot
9.2.6. Spring
9.2.7. Powder
9.2.8. Formed Actuator Components
9.3. Analysis, Insights and Forecast - by Manufacturing Process
9.3.1. Vacuum Induction Melting
9.3.2. VIM + VAR
9.3.3. Vacuum Arc Remelting
9.3.4. Powder Metallurgy
9.4. Analysis, Insights and Forecast - by Transformation Temperature
9.4.1. Below 100C
9.4.2. 100-400C
9.4.3. Above 400C
9.5. Analysis, Insights and Forecast - by End-Use Industry
9.5.1. Biomedical
9.5.2. Automotive
9.5.3. Aerospace & Defense
9.5.4. Consumer Electronics
9.5.5. Industrial Actuation
10. Shape Memory Alloys Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Alloy Type
10.1.1. Nitinol
10.1.2. Copper-based
10.1.3. Iron-based
10.1.4. Other
10.2. Analysis, Insights and Forecast - by Product Form
10.2.1. Wire
10.2.2. Tube
10.2.3. Sheet/Strip
10.2.4. Rod/Bar
10.2.5. Ingot
10.2.6. Spring
10.2.7. Powder
10.2.8. Formed Actuator Components
10.3. Analysis, Insights and Forecast - by Manufacturing Process
10.3.1. Vacuum Induction Melting
10.3.2. VIM + VAR
10.3.3. Vacuum Arc Remelting
10.3.4. Powder Metallurgy
10.4. Analysis, Insights and Forecast - by Transformation Temperature
10.4.1. Below 100C
10.4.2. 100-400C
10.4.3. Above 400C
10.5. Analysis, Insights and Forecast - by End-Use Industry
12. Shape Memory Alloys Market Research Methodology
List of Figures
Figure 1: Shape Memory Alloys Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Shape Memory Alloys Market Volume Breakdown (Metric Tons, %) by Region 2026 & 2034
Figure 3: North America Shape Memory Alloys Market Revenue (Billion), by Alloy Type 2026 & 2034
Figure 4: North America Shape Memory Alloys Market Volume (Metric Tons), by Alloy Type 2026 & 2034
Figure 5: North America Shape Memory Alloys Market Revenue Share (%), by Alloy Type 2026 & 2034
Figure 6: North America Shape Memory Alloys Market Volume Share (%), by Alloy Type 2026 & 2034
Figure 7: North America Shape Memory Alloys Market Revenue (Billion), by Product Form 2026 & 2034
Figure 8: North America Shape Memory Alloys Market Volume (Metric Tons), by Product Form 2026 & 2034
Figure 9: North America Shape Memory Alloys Market Revenue Share (%), by Product Form 2026 & 2034
Figure 10: North America Shape Memory Alloys Market Volume Share (%), by Product Form 2026 & 2034
Figure 11: North America Shape Memory Alloys Market Revenue (Billion), by Manufacturing Process 2026 & 2034
Figure 12: North America Shape Memory Alloys Market Volume (Metric Tons), by Manufacturing Process 2026 & 2034
Figure 13: North America Shape Memory Alloys Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 14: North America Shape Memory Alloys Market Volume Share (%), by Manufacturing Process 2026 & 2034
Figure 15: North America Shape Memory Alloys Market Revenue (Billion), by Transformation Temperature 2026 & 2034
North America Shape Memory Alloys Market Volume (Metric Tons), by Transformation Temperature 2026 & 2034
List of Tables
Table 1: Shape Memory Alloys Market Revenue Billion Forecast, by Alloy Type 2020 & 2034
Table 2: Shape Memory Alloys Market Volume Metric Tons Forecast, by Alloy Type 2020 & 2034
Table 3: Shape Memory Alloys Market Revenue Billion Forecast, by Product Form 2020 & 2034
Table 4: Shape Memory Alloys Market Volume Metric Tons Forecast, by Product Form 2020 & 2034
Table 5: Shape Memory Alloys Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 6: Shape Memory Alloys Market Volume Metric Tons Forecast, by Manufacturing Process 2020 & 2034
Table 7: Shape Memory Alloys Market Revenue Billion Forecast, by Transformation Temperature 2020 & 2034
Table 8: Shape Memory Alloys Market Volume Metric Tons Forecast, by Transformation Temperature 2020 & 2034
Table 9: Shape Memory Alloys Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 10: Shape Memory Alloys Market Volume Metric Tons Forecast, by End-Use Industry 2020 & 2034
Table 11: Shape Memory Alloys Market Revenue Billion Forecast, by Region 2020 & 2034
Table 12: Shape Memory Alloys Market Volume Metric Tons Forecast, by Region 2020 & 2034
Table 13: North America Shape Memory Alloys Market Revenue Billion Forecast, by Alloy Type 2020 & 2034
Table 14: North America Shape Memory Alloys Market Volume Metric Tons Forecast, by Alloy Type 2020 & 2034
Table 15: North America Shape Memory Alloys Market Revenue Billion Forecast, by Product Form 2020 & 2034
Table 16: North America Shape Memory Alloys Market Volume Metric Tons Forecast, by Product Form 2020 & 2034
Frequently Asked Questions
1. How big is the shape memory alloys market?
The global shape memory alloys market was valued at approximately 17.1 billion in 2025 and is estimated near 19.0 billion in 2026. Scope differences explain most variance between published estimates, which range from material-only to full fabricated-component definitions.
2. What is the shape memory alloys market growth rate?
Consensus points to roughly 11% compound annual growth through the early 2030s, with the most defensible figure at 11.2% from 2026 to 2033. Medical Nitinol demand growing near 18% underpins that blended rate.
3. Which alloy type dominates the shape memory alloys market?
Nickel-titanium, or Nitinol, holds an estimated 88.5% revenue share. Its corrosion resistance, biocompatibility, superelastic behavior and fatigue life make it the default choice for medical and high-specification aerospace programs.
4. Which region leads the shape memory alloys market?
North America leads with roughly 32–35% revenue share, driven by US medical-device OEM concentration and aerospace qualification depth. Asia Pacific is the fastest-growing region on device localization and EV production scale.
5. What are the biggest challenges facing shape memory alloy suppliers?
High production costs, complex vacuum melting and thermomechanical processing, volatile nickel and titanium input costs, and multi-year regulatory certification cycles all constrain how quickly capacity and new programs can commercialize.
6. Who are the leading shape memory alloy companies?
Resonetics leads with roughly 10% share, followed by Fort Wayne Metals, ATI Inc., Xi'an Saite and Furukawa Electric. Together the top five hold about 27%, reflecting a fragmented, qualification-gated competitive structure.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the shape memory alloy value chain with raw material and melt suppliers, specialized alloy producers, downstream conversion and finishing specialists, and global distributors of wire, tube and sheet forms. Respondents were designated decision-makers, principally VP-level sourcing executives, heads of metallurgical R&D, technical directors responsible for transformation-temperature control, and commercial operations leads managing OEM qualification programs.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
38%
Metallurgical R&D Directors
32%
Quality & Regulatory Leads
18%
Commercial Operations Leads
12%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Alloy Producers & Melters
40%
Conversion & Finishing Specialists
32%
Distributors & Traders
18%
OEM Procurement Groups
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on official multilateral trade statistics (UN Comtrade, US ITC, Eurostat), corporate annual filings and investor presentations from listed alloy producers, patent databases covering Nitinol processing and high-temperature alloy compositions, and recognized technical standards bodies governing medical-grade shape memory alloy specification.
Demand Modeling & Market Sizing Triangulation
Sizing runs two parallel tracks. Top-down allocation maps macroeconomic output and end-use industry spending to alloy intensity per segment. Bottom-up modeling aggregates producer melt capacity, form-factor conversion yields, realized pricing per kilogram, and measured end-use consumption tonnage. Divergence between tracks above 8% triggers re-interrogation of the underlying inputs.


 Shape Memory Alloys Market