 Soy-Based Chemical Market
 Outlook & Size Forecast 2025
Updated On : Nov 19, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Soy-Based Chemical Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 32.40 B |
| 2026 | 34.80 B |
| 2027 | 37.40 B |
| 2028 | 40.10 B |
| 2029 | 43.10 B |
| 2030 | 46.30 B |
| 2031 | 49.70 B |

The soy-based chemical market covers industrial and consumer chemicals derived from soybean oil, meal and protein — including soy methyl esters, fatty acids, polyols, waxes, lecithin and isoflavones — used as renewable, biodegradable substitutes for petroleum-derived solvents, lubricants, polymers and fuels.
This report covers global soy-derived chemical products across biodiesel, paper, cosmetics, food and beverage, plastics and polymer end-uses, with value sizing from 2025 to 2035. This analysis does not cover edible soybean oil sold as food, raw soybean commodity trading, or non-soy bio-based chemicals such as corn or canola derivatives.
Published estimates cluster tightly around a base value of roughly USD 29–34 billion, with 7.4–7.6% CAGRs; the divergence is driven mainly by scope differences in biodiesel inclusion and soy meal accounting.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 32.4 Bn → USD 66.1 Bn | 2025 | 2035 | 7.4% | Soy oil, fatty acids, polyols, waxes, methyl-soyate, isoflavones; biodiesel included | One published industry estimate |
| USD 29.0 Bn → USD 52.1 Bn | 2024 | 2032 | 7.59% | Soy oil, wax, polymers, fatty acids, methyl esters; broad application set | A competing analysis |
| USD 34.4 Bn → USD 61.1 Bn | 2025 | 2033 | 7.5% | Soy methyl esters, fatty acids, protein & isoflavones, polyols, lecithin | Another published forecast |
Our analysis suggests the USD 32.4 billion base is the most defensible for industrial buyers, because it captures biodiesel without conflating edible soy oil volumes. The lower USD 29 billion figure implies a narrower chemical-only lens, which understates solvent and polyol demand now scaling in coatings and foams.
Segmentation splits along product type, end-use industry and application, with soy oil and biodiesel dominating value while polyols and binders grow fastest.
| Parent segment | Children |
|---|---|
| Product Type | Soy Oil, Fatty Acids, Polyols, Soy Waxes, Methyl-Soyate, Isoflavones, Lecithin, Others |
| End-Use Industry | Biodiesel, Paper, Cosmetics, Food & Beverages, Plastics & Polymer, Pharmaceuticals, Agriculture, Others |
| Application | Solvents, Lubricants, Emulsifiers, Binders & Adhesives, Coatings, Others |
Soy polyols are the standout growth pocket, expanding near 8% annually on bio-polyurethane demand in construction and automotive. Conversely, soy methyl esters remain the volume anchor in solvents, where low-VOC regulation creates structural replacement demand for petroleum naphtha.
North America leads with roughly 34% of global value, anchored by U.S. soybean processing infrastructure and biodiesel blending mandates, while Asia-Pacific is the fastest-growing region.
| Region | Market Share (%) |
|---|---|
| North America | 0.34% |
| Europe | 0.23% |
| Asia-Pacific | 0.31% |
| South America | 0.08% |
| Middle East & Africa | 0.04% |
The U.S. alone contributes close to 80% of North American revenue, reflecting integrated crush capacity and Renewable Fuel Standard-driven biodiesel offtake. Germany's market, estimated near USD 1.8 billion in 2023, illustrates how EU bioeconomy policy converts into chemical demand. China's scale-up in fermentation and enzymatic processing is the key swing factor for Asia-Pacific pricing through 2035.
Sustainability mandates and low-VOC regulation are the dominant demand pull, while soybean price volatility and food-versus-fuel feedstock competition cap the pace of margin expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Bio-based and low-VOC regulation | Driver | High | Mandates and tax credits shift formulators from petroleum solvents to soy methyl esters |
| Corporate decarbonization targets | Driver | High | Scope 3 reduction goals drive procurement of renewable polyols and lubricants |
| Processing technology advances | Driver | Medium | Enzymatic and catalytic routes improve yield, purity and cost parity |
| Soybean price volatility | Restraint | High | Weather and trade shocks transmit directly to producer margins |
| Feedstock competition from food and feed | Restraint | Medium | Crush allocation constrains chemical-grade oil availability |
Our analysis suggests the driver-restraint balance favors growth, but with a cyclical skew. When soybean prices spike, biodiesel economics compress first, while specialty polyols and solvents hold pricing power because of qualification lock-in. This implies buyers should hedge feedstock exposure and prioritize specialty applications where switching costs protect value.
The competitive field is moderately concentrated, pairing integrated agribusiness majors with specialty chemical and bio-solvent specialists.
| Company | Primary positioning | Strategic moat |
|---|---|---|
| Cargill | Integrated soy crush and oleochemicals | Feedstock control and global logistics |
| Archer Daniels Midland | Soy processing, biodiesel, polyols | Scale, crush integration, policy access |
| Bunge | Soy origination and processing | Supply chain and origination depth |
| Dow | Specialty soy-derived intermediates | Formulation IP and customer qualification |
| Elevance Renewable Sciences | Bio-based specialty chemicals | Metathesis technology platform |
| Renewable Lubricants / Vertec BioSolvents | Niche bio-lubricants and solvents | Application specialization and brand |
Differentiation hinges on feedstock integration versus formulation IP. Integrated players win on cost through crush-to-chemical chains, while specialists win on performance specifications and regulatory documentation. Our analysis suggests the middle ground — non-integrated commodity producers — faces the sharpest margin compression.
Buyers should prioritize suppliers who can document consistent bio-based content, low-VOC compliance and full traceability from crush to finished chemical. Qualification cycles in coatings, automotive foams and food-contact packaging run six to eighteen months, creating meaningful switching costs that favor early supplier lock-in. Procurement risk concentrates in feedstock pass-through clauses: contracts should cap soybean-linked index exposure and specify alternative sourcing. Operators should also monitor GMO versus non-GMO sourcing, as EU and Japanese buyers increasingly require non-GMO certification, and confirm REACH, TSCA and EPA registration status before scaling.
The balance of evidence favors a constructive outlook: 7.4–7.6% CAGR across independent estimates signals genuine structural demand rather than a policy bubble. The strongest counter-argument is that biodiesel dominates value and remains policy-dependent; if blending mandates soften, headline growth could undershoot. Yet specialty polyols, solvents and binders are less policy-levered and are compounding faster, which partially decouples the market from fuel mandate cycles.
Our analysis suggests the most defensible strategic posture is integration-plus-specialization: secure feedstock via partnerships or crush access, then compete on qualified specialty formulations where switching costs protect pricing. Single-segment commodity players are the most exposed to soybean price cycles and food-versus-fuel feedstock allocation. Buyers should treat 2027–2030 as the window for supplier qualification, before tighter bio-content rules raise barriers.
Actionable strategy:
What would change this conclusion: a sustained decline in blending mandates, a multi-year soybean price shock above historic bands, or accelerated commercialization of competing non-soy bio-feedstocks would materially compress the forecast. Precise sub-segment forecasting and vendor-level share analysis require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.4% from 2020-2034 |
| Segmentation |
|
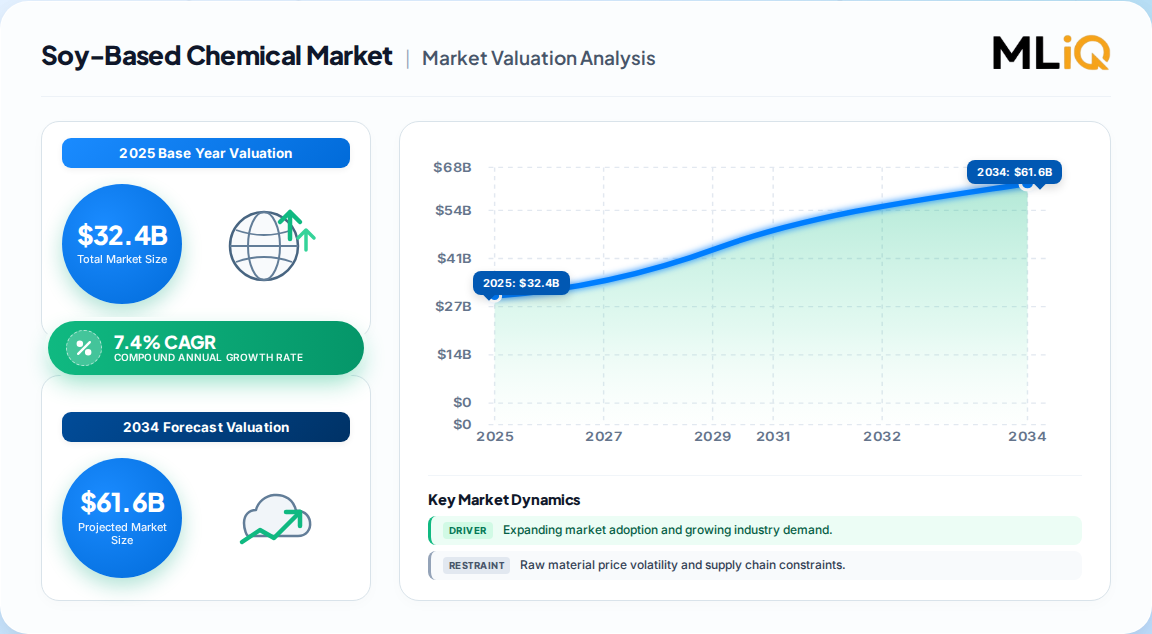
The global soy-based chemical market is estimated at USD 32.4 billion in 2025, with published estimates ranging from roughly USD 29 billion to USD 34 billion depending on whether biodiesel and soy meal are included.
The market is forecast to grow at a 7.4% CAGR from 2025 to 2035, reaching approximately USD 66.1 billion. Competing forecasts cluster between 7.5% and 7.6%, confirming consistent structural demand.
Soy oil leads product type with about 31.5% revenue share, while biodiesel is the largest end-use at roughly 35.2%. Soy polyols and binders and adhesives are the fastest-growing sub-segments.
North America holds the largest share at approximately 34%, driven by U.S. crush capacity and biodiesel mandates. Asia-Pacific is the fastest-growing region, led by China's processing scale-up.
Leading vendors include Cargill, Archer Daniels Midland, Bunge, Dow and Elevance Renewable Sciences, alongside specialists such as Renewable Lubricants and Vertec BioSolvents serving niche applications.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the soy-based chemical value chain, including soybean processors and oleochemical producers, specialty formulators and blenders, contract manufacturers, and global industrial distributors. Decision-maker designations interviewed included VP-level sourcing executives, Heads of R&D and formulation, Technical Directors, and Commercial Operations Leads, ensuring both demand-side and supply-side validation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial & Regulatory Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Soybean Processors & Oleochemical Producers | 45% |
| Specialty Formulators & Blenders | 35% |
| Industrial Distributors & Traders | 20% |
Findings were cross-checked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent databases, and recognized industry standards bodies. No third-party market research publisher data is used as a validation source.
We simultaneously run a Top-Down model allocating macroeconomic and industry-segment output to soy-based chemical consumption, and a Bottom-Up model built on manufacturer capacity, product pricing and end-use consumption. Triangulation reconciles divergence between the two to a single defensible base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |