 APAC Polyurethane Hot-Melt Adhesives Industry
APAC Polyurethane Hot-Melt Adhesives Market 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 234

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 APAC Polyurethane Hot-Melt Adhesives Industry

Khageshwar Rongkali
Senior Analyst

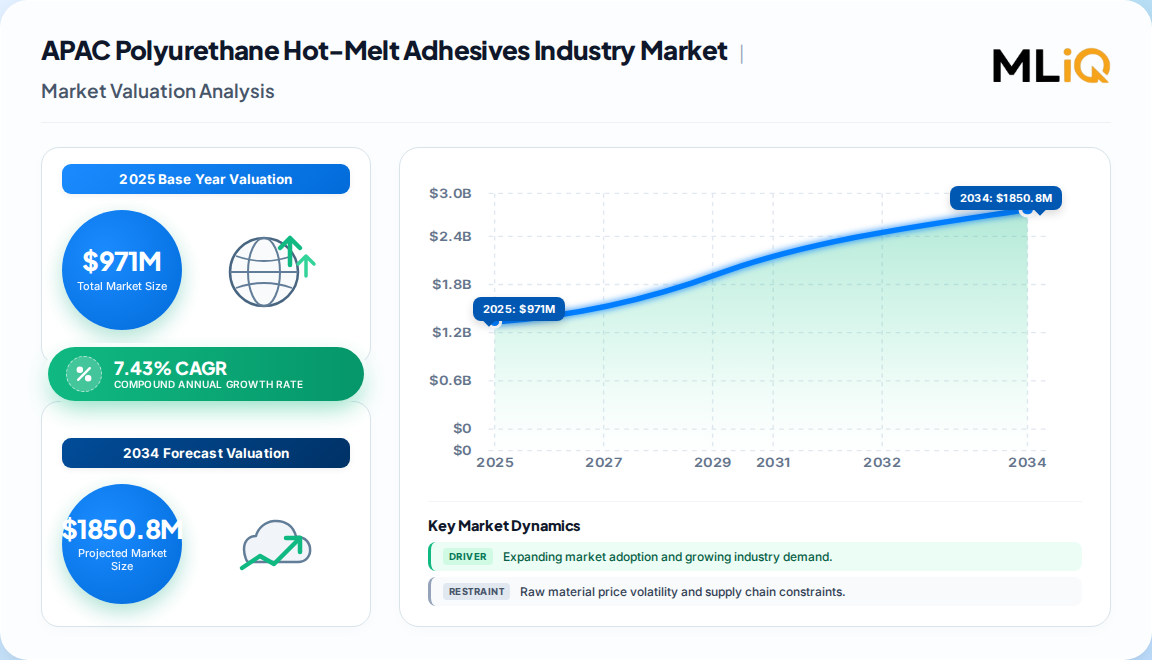
| Year | Market Size |
|---|---|
| 2025 | 971.0 M |
| 2026 | 1.040 B |
| 2027 | 1.120 B |
| 2028 | 1.200 B |
| 2029 | 1.290 B |
| 2030 | 1.390 B |
| 2031 | 1.490 B |

The APAC polyurethane hot-melt adhesives market covers solvent-free, 100% solids adhesives based on isocyanate-terminated polyurethane prepolymers, supplied as reactive or non-reactive grades for packaging, electronics, automotive, furniture, footwear, and healthcare bonding across Asia-Pacific. Curing occurs through moisture crosslinking or cooling, delivering structural strength without volatile organic compound emissions.
This analysis covers reactive and non-reactive polyurethane hot-melt adhesives consumed in Asia-Pacific across nine application verticals, with value forecasts to 2031 and vendor share assessment. It excludes solvent-borne polyurethane adhesives, waterborne polyurethane dispersions, EVA and polyolefin hot melts, and polyurethane sealants or foams. This analysis does not cover adjacent markets such as hot-melt pressure-sensitive adhesives or isocyanate feedstock trading.
The APAC PU hot-melt market is most defensibly sized at USD 971 million in 2025, derived from the 45.78% regional share of a USD 2.12 billion global base, growing at 7.43% CAGR to USD 1.49 billion by 2031. This triangulation aligns with a separate estimate of a USD 722.5 million global reactive-only segment in 2021 and a broader USD 9 billion hot-melt category, confirming PU hot melts sit at roughly 10–11% of total hot-melt value.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.12B global; APAC ~USD 971M | 2026 | 2031 | 7.43% | All PU hot melts, all regions | One published estimate |
| USD 722.5M global reactive-only | 2021 | 2030 | 7.64% | Reactive PUR only, global | A competing analysis |
| USD 9.0B total hot melts | 2025 | 2035 | 3.4% | All hot-melt chemistries | Another published estimate |
Our analysis suggests the 7.43% figure is most defensible for APAC because it captures both reactive and non-reactive grades and reflects the region's packaging and electronics intensity. The narrower reactive-only series implies APAC reactive value near USD 500–550 million in 2025, consistent with a 55–60% reactive mix within the broader regional total.
Segmentation follows two axes: chemistry type (reactive versus non-reactive) and end-use application, with reactive grades dominating value and packaging dominating volume. Healthcare and electronics are the fastest-growing application pockets, reflecting sterilization resistance and low-temperature dispensing requirements respectively.
| Parent Segment | Children |
|---|---|
| By Type | Reactive, Non-Reactive |
| By Application | Paper Board & Packaging, Electronics & Electrical, Automotive, Furniture & Woodworking, Footwear, Healthcare, Textiles, Bookbinding, Other |
| By Substrate | Plastics, Fiberglass, Nylon, Metal, Wood, Composite |
China leads the APAC PU hot-melt adhesives market with an estimated 44% regional share, underpinned by packaging conversion capacity, electronics assembly, and footwear clusters. India and Southeast Asia follow as the fastest-growing sub-regions, while Japan and South Korea anchor high-spec electronics and automotive demand.
| Region | Market Share (%) |
|---|---|
| China | 0.44% |
| India | 0.16% |
| Japan | 0.12% |
| South Korea | 0.1% |
| Southeast Asia | 0.1% |
| Australia | 0.05% |
| Rest of APAC | 0.03% |
| Sub-region | Est. share of APAC | Primary demand driver |
|---|---|---|
| China | 44% | Packaging, electronics, footwear |
| India | 16% | E-commerce packaging, automotive |
| Japan | 12% | Electronics, automotive |
| South Korea | 10% | Electronics, displays |
| Southeast Asia | 10% | Packaging, footwear |
| Australia | 5% | Construction, packaging |
| Rest of APAC | 3% | Mixed industrial |
Growth is driven by e-commerce automation, electronics miniaturization, VOC regulation, and automotive lightweighting, which together add roughly 4.4 percentage points to baseline CAGR. Restraining factors include MDI and TDI price volatility, EVA substitution in price-sensitive packaging, and lengthy OEM qualification cycles, each shaving 0.5–1.5 points.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| E-commerce automation | Driver (+2.0%) | High | Instant green strength for high-speed case sealing |
| Electronics miniaturization | Driver (+1.2%) | High | Low-temperature dispensing protects fine-pitch parts |
| VOC regulation | Driver (+0.8%) | Medium | Shift from solvent-borne to 100% solids PUR |
| Automotive lightweighting | Driver (+0.6%) | Medium | Structural bonding of mixed substrates |
| MDI/TDI volatility | Restraint (−1.2%) | High | Input cost pass-through compresses formulator margins |
| EVA substitution | Restraint (−0.5%) | Medium | Cheaper thermoplastic grades in basic carton sealing |
| Qualification cycles | Restraint (−0.6%) | Medium | 6–18 month OEM validation slows adoption |
Henkel leads the broader hot-melt category with over 14% global share in 2025, while H.B. Fuller, Bostik (Arkema), 3M, Sika, and Jowat hold strong positions in reactive polyurethane. Differentiation rests on low-temperature rheology control, micro-emission formulations, and application engineering support rather than raw chemistry alone.
| Company | HQ | PU hot-melt positioning | Notable strength |
|---|---|---|---|
| Henkel AG & Co. KGaA | Germany | Full-line leader, reactive and non-reactive | Packaging automation integration |
| H.B. Fuller Company | USA | Reactive PUR, EV battery bonding | EV Bond™ 775 platform |
| Arkema (Bostik) | France | Reactive PUR, hygiene and packaging | Global distribution reach |
| 3M Company | USA | Specialty reactive and low-temperature grades | Electronics and medical |
| Jowat SE | Germany | Reactive PUR for furniture and woodworking | European specification base |
| Sika AG | Switzerland | Automotive and construction PUR | OEM qualification depth |
Our analysis suggests competitive moats in APAC are increasingly built on local formulation and dispensing support, not just global brand equity. Chinese and Indian formulators are narrowing the performance gap in packaging-grade reactive systems, which pressures incumbents' pricing in commodity segments.
Buyers should prioritize suppliers that guarantee predictable rheology for robotic dispensing, provide low-temperature (100–120°C) grades for heat-sensitive components, and document free isocyanate content below 0.1% to satisfy evolving occupational health rules. Switching costs are material: requalification typically takes 6–18 months and may require line revalidation.
Procurement risk concentrates in MDI and TDI price swings, so dual-sourcing and index-linked contracts are prudent. Regulatory compliance spans REACH di-isocyanate labeling, local VOC limits, and food-contact migration standards for packaging. Operators must also confirm melter compatibility and melt-on-demand support to avoid tank charring and downtime.
The balance of evidence favors a structural upgrade cycle in APAC rather than pure volume growth. Reactive grades will outgrow non-reactive, packaging remains the anchor, and electronics and healthcare offer the steepest margin pools. Vendors that invest in low-temperature dispensing and micro-emission formulations will capture disproportionate share as regulations tighten.
The strongest counter-argument is that EVA and metallocene hot melts could blunt reactive PUR penetration in price-sensitive packaging, particularly in India and Southeast Asia. However, the e-commerce durability requirement and VOC rules make substitution less likely in high-speed, high-temperature logistics environments.
Evidence that would change our conclusion: a sustained EVA price collapse below USD 1,200 per metric ton, or a regulatory rollback on di-isocyanate labeling in major APAC markets, would weaken the reactive PUR upgrade thesis. This overview establishes the strategic frame; precise sub-segment forecasting and vendor share modeling require the full report.
The following methodology underpins the APAC PU hot-melt adhesives analysis, combining primary fieldwork with secondary trade validation and triangulated demand modeling.
We apply a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material suppliers (isocyanate and polyol producers), specialized PU hot-melt formulators, contract blenders, and regional industrial distributors across China, India, Japan, South Korea, and Southeast Asia. Interviewees included VP-level sourcing leads, heads of R&D, technical directors, and commercial operations managers, ensuring coverage of procurement, formulation, and go-to-market perspectives.
We triangulate against UN Comtrade and WTO trade flows for isocyanates and adhesive preparations, US ITC and Eurostat trade data, corporate 10-K and annual investor filings, patent databases, and recognized technical standards including ISO 9001 and ASTM adhesive test methods. Industry association publications and regulatory registers inform compliance and specification analysis.
We run simultaneous top-down allocation from macroeconomic and end-use industry output and bottom-up modeling from manufacturer capacity, product pricing, and end-use consumption. Divergences above 8% trigger re-interrogation of regional demand assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression, and demand elasticity | High |
| Regional Distribution | APAC sub-region share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading vendor positions | Annual reports, capacity mapping, commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.43% from 2020-2034 |
| Segmentation |
|
The APAC PU hot-melt adhesives market was estimated at USD 971 million in 2025, representing 45.78% of the global USD 2.12 billion market. It is forecast to reach USD 1.49 billion by 2031 at a 7.43% CAGR.
China leads with roughly 44% of APAC demand, driven by packaging conversion, electronics assembly, and footwear manufacturing. India and Southeast Asia are the fastest-growing sub-regions as e-commerce and automotive production expand.
Reactive PU hot melts moisture-cure after application to form thermoset bonds with high heat and solvent resistance, holding 62.12% of global share. Non-reactive grades simply cool and re-melt, offering lower cost and faster set but weaker temperature performance.
Buyers face MDI and TDI feedstock price volatility, 6–18 month requalification cycles when switching suppliers, and tightening di-isocyanate labeling rules. Dual-sourcing and index-linked contracts are the primary mitigants.
Healthcare is the fastest-growing application at an 8.08% CAGR, driven by sterilization-resistant medical device assemblies. Packaging remains the largest at 31.96% revenue share, while electronics benefits from low-temperature dispensing needs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
The following methodology underpins the APAC PU hot-melt adhesives analysis, combining primary fieldwork with secondary trade validation and triangulated demand modeling.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Managers | 20% |
| Regulatory & Quality Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Isocyanate & Polyol Suppliers | 35% |
| PU Hot-Melt Formulators | 40% |
| Contract Blenders | 15% |
| Industrial Distributors | 10% |
We apply a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material suppliers (isocyanate and polyol producers), specialized PU hot-melt formulators, contract blenders, and regional industrial distributors across China, India, Japan, South Korea, and Southeast Asia. Interviewees included VP-level sourcing leads, heads of R&D, technical directors, and commercial operations managers, ensuring coverage of procurement, formulation, and go-to-market perspectives.
We triangulate against UN Comtrade and WTO trade flows for isocyanates and adhesive preparations, US ITC and Eurostat trade data, corporate 10-K and annual investor filings, patent databases, and recognized technical standards including ISO 9001 and ASTM adhesive test methods. Industry association publications and regulatory registers inform compliance and specification analysis.
We run simultaneous top-down allocation from macroeconomic and end-use industry output and bottom-up modeling from manufacturer capacity, product pricing, and end-use consumption. Divergences above 8% trigger re-interrogation of regional demand assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression, and demand elasticity | High |
| Regional Distribution | APAC sub-region share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading vendor positions | Annual reports, capacity mapping, commercial filings | High |