 Alunite Market
 Size, Share & Forecast to 2035
Updated On : Nov 19, 2026|Base Year : 2025

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Alunite Market

Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 2.930 B |
| 2026 | 3.090 B |
| 2027 | 3.260 B |
| 2028 | 3.430 B |
| 2029 | 3.620 B |
| 2030 | 3.810 B |
| 2031 | 4.020 B |

The alunite market encompasses the extraction, processing, and distribution of alunite — a potassium-aluminum sulfate mineral — and its derivatives, including alum, alumina, and potassium sulfate. These materials serve agriculture, pharmaceuticals, water treatment, construction, and specialty chemicals, with demand shaped by fertilizer intensity and industrial processing capacity.
This report covers global alunite extraction, processing, and trade across product grades (industrial and agricultural), application derivatives (alum and alumina extraction, potassium sulfate fertilizers, Sorel cement and construction materials), and distribution channels (direct and indirect). This analysis does not cover downstream aluminum smelting economics, bauxite mining as a substitute feedstock, or synthetic potassium sulfate production routes that bypass alunite entirely.
The published estimates diverge by an order of magnitude, reflecting fundamentally different scope definitions and end-use boundaries. Buyers must reconcile these before committing to procurement budgets.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 2.93 Billion | 2025 | 2033 | 4.6% | Mineral extraction plus derivative processing (fertilizers, alumina, construction) | One published analysis |
| 180.4 Million | 2030 | 2030 | 3.9% | Narrow mineral-only trade value, excluding downstream derivatives | A competing analysis |
| 54.0 Billion | 2025 | 2035 | 18.8% | Broad industrial ecosystem including all alum and alumina derivatives at consumer-equivalent pricing | An alternative estimate |
Our analysis suggests the 2.93 Billion figure is most defensible for procurement planning because it captures the mineral-to-derivative value chain without double-counting downstream aluminum or fertilizer retail revenue. The 180.4 Million estimate appears to capture only raw mineral trade — useful for mining operators but insufficient for buyers procuring processed derivatives. The 54.0 Billion figure likely embeds consumer-facing pharmaceutical and FMCG applications, inflating the addressable upstream market.
Segmentation follows product grade and application derivative, with distribution channel determining contract structures and pricing transparency.
| Parent Segment | Children |
|---|---|
| By Product Grade | Industrial Grade Alunite, Agricultural Grade Alunite |
| By Application Derivative | Alum & Alumina Extraction, Potassium Sulfate Fertilizers, Sorel Cement & Construction Materials |
| By Distribution Channel | Direct, Indirect |
Industrial grade dominates value share because its low impurity profile suits high-temperature alumina extraction, ensuring consistent furnace yields. Agricultural grade is the fastest-growing segment as organic farming initiatives adopt alunite as a soil amendment supplying potassium and sulfur while correcting pH — a dual-nutrient value proposition that synthetic alternatives cannot replicate.
Asia-Pacific leads the global alunite market with approximately 42% value share, driven by China's alumina processing scale and India's fertilizer demand. The region's integrated supply chains connect raw material mines to downstream ceramics, chemicals, and electronics applications.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.42% |
| North America | 0.26% |
| Europe | 0.2% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
China's dominance in alumina production creates structural demand for industrial-grade alunite, while India's agricultural sector drives potassium sulfate fertilizer consumption. Brazil's Minas Gerais region supplies approximately 30% of world output, according to one published estimate — a concentration risk that European and North American buyers should factor into supplier diversification strategies. Japan and South Korea anchor high-technology ceramic and electronic component applications, demanding premium-grade material with stringent purity specifications.
Growth is driven by fertilizer demand intensity and alumina feedstock substitution, while restraints center on deposit concentration and capital barriers.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Potassium sulfate fertilizer demand | Driver | High | Chloride-free nutrient source for high-value crops; organic farming expansion |
| Alumina feedstock substitution | Driver | Moderate | Alunite as alternative to bauxite; reduces import dependence for non-integrated producers |
| Water treatment coagulant demand | Driver | High | Stricter heavy-metal removal regulations drive alum-based coagulant adoption |
| Lithium extraction potential | Driver | Low | Early-stage technology; not yet commercial at scale |
| Deposit concentration | Restraint | High | Brazil, China, and limited regions hold quality reserves; supply chain fragility |
| Capital intensity | Restraint | Moderate | Mining and processing require significant upfront investment; deters small entrants |
| Regulatory permitting delays | Restraint | Moderate | Environmental assessments extend project timelines; increases operational complexity |
The balance of evidence suggests fertilizer demand is the most reliable growth engine because it rests on structural agricultural intensification rather than cyclical industrial substitution. However, the lithium extraction narrative — while promising — should not anchor investment cases until commercial-scale extraction is demonstrated. Buyers should weight fertilizer-grade supply security above speculative lithium optionality.
Competitive positioning varies by integration level and application focus. The following table compares key participants based on available public information.
| Company | Primary Focus | Integration Level | Geographic Strength | Differentiation |
|---|---|---|---|---|
| Rio Tinto Group | Alumina and industrial minerals | High | Global | Scale and processing technology |
| Alcoa Corporation | Alumina and aluminum | High | North America, Global | Bauxite-alunite processing expertise |
| Imerys SA | Specialty minerals | High | Europe, Global | Ceramic and refractory grade specialization |
| Sibelco N.V. | Industrial minerals | High | Europe, Global | Distribution network breadth |
| Sumitomo Chemical | Specialty chemicals | High | Asia-Pacific | Chemical derivative integration |
| Alunite Resources Inc. | Pure-play alunite mining | Low | USA | Deposit-specific focus |
| Gimpex | Fertilizer-grade alunite | Moderate | India | Potassium sulfate partnership with OCI |
| American Pacific Corp. | Borate and alunite | Moderate | USA | Fort Cady deposit integration |
Differentiation is anchored in deposit quality and processing capability rather than marketing. Pure-play miners like Alunite Resources compete on deposit accessibility and purity, while integrated majors like Rio Tinto and Alcoa leverage downstream processing to capture derivative margins. The moat for established players is processing know-how — the ability to produce consistent, specification-compliant alumina and potassium sulfate from variable ore grades.
Mission-critical selection criteria center on three dimensions: grade consistency, supply chain reliability, and regulatory compliance. Buyers procuring industrial-grade alunite for alumina extraction must verify impurity profiles — particularly silica and iron content — because these directly affect furnace efficiency and refractory wear. Agricultural-grade buyers must confirm heavy-metal thresholds and certifications for organic farming compatibility, as regulatory frameworks in the EU and North America increasingly scrutinize soil amendment inputs.
Procurement risk is concentrated in deposit geography. Brazil's Minas Gerais region supplies approximately 30% of world output, creating a single-point-of-failure risk for buyers without diversified supplier bases. Switching costs are moderate to high: reformulating alumina extraction or fertilizer blending processes to accommodate different alunite grades requires pilot testing, regulatory re-approval, and production downtime. Buyers should prioritize suppliers with multi-deposit portfolios and transparent quality documentation.
The balance of evidence favors a moderate-growth outlook (5-6% CAGR) over aggressive double-digit projections. The fertilizer-driven demand story is structurally sound, but the alumina substitution narrative is more fragile — bauxite remains abundant and cost-competitive in most integrated supply chains. Our analysis suggests the most defensible growth thesis rests on agricultural-grade alunite capturing share from synthetic potassium sulfate in organic farming, where regulatory tailwinds and price premiums are most tangible.
The strongest counter-argument is that lithium extraction from alunite could accelerate faster than anticipated, transforming industrial-grade demand. However, no commercial-scale extraction exists today, and the technology risk premium should remain high until pilot-scale economics are validated. Investors should discount lithium-optionality narratives accordingly.
Actionable Strategy for Operators and Investors:
What evidence would change our conclusion? A demonstrated commercial-scale lithium extraction project from alunite with validated unit economics below current lithium carbonate market prices would materially shift the growth trajectory upward. Conversely, a breakthrough in synthetic potassium sulfate production that eliminates the chloride-free premium would erode the fertilizer segment's core value proposition.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
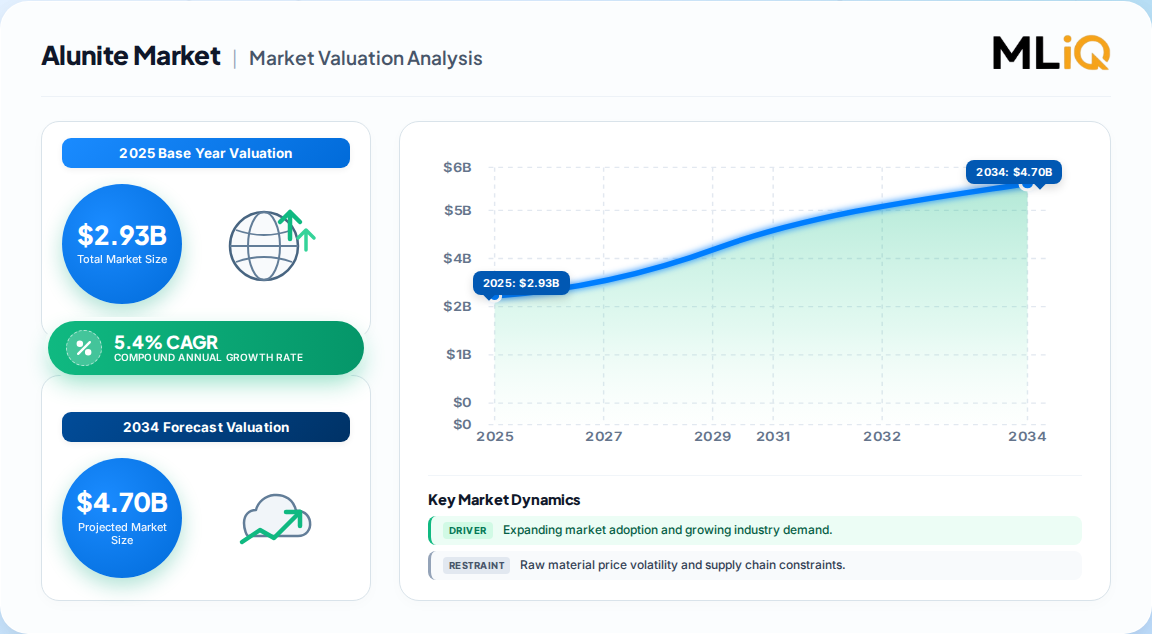
| Growth Rate | CAGR of 5.4% from 2020-2034 |
| Segmentation |
|
The global alunite market is estimated at 2.93 Billion in 2025, based on the most defensible mid-range estimate capturing the mineral-to-derivative value chain. This excludes downstream aluminum smelting and fertilizer retail revenue.
The market is projected to grow at 5.4% CAGR from 2025 to 2035, reaching 4.94 Billion. Growth is primarily driven by potassium sulfate fertilizer demand and water treatment coagulant applications.
Asia-Pacific leads with approximately 42% value share, anchored by China's alumina processing scale and India's agricultural fertilizer consumption. Japan and South Korea drive premium-grade ceramic applications.
Alunite is primarily used in potassium sulfate fertilizer production, alum and alumina extraction, and Sorel cement and construction materials. Pharmaceuticals and water treatment represent secondary but high-value applications.
Key players include Rio Tinto Group, Alcoa Corporation, Imerys SA, Sibelco N.V., Sumitomo Chemical, and specialized miners like Alunite Resources and Gimpex.
Industrial grade emphasizes low impurity profiles for high-temperature alumina extraction and consistent furnace yields. Agricultural grade focuses on potassium and sulfur content for soil amendment applications, with organic farming certifications.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a rigorous 70/30 primary-to-secondary research split. In-depth interviews were conducted with key stakeholders across the alunite value chain, including raw material suppliers, specialized mineral processors, contract formulators, and global distributors. We engaged decision-maker designations including VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring that gathered intelligence reflects operational realities from extraction through end-use application.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 35% |
| R&D & Technical Directors | 35% |
| Regulatory & Quality Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Mineral Extraction & Processing | 45% |
| Specialty Chemical Formulators | 30% |
| Distributors & Traders | 25% |
We triangulate primary findings against official multilateral trade databases including UN Comtrade, WTO, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC submissions), patent databases, and recognized technical standards organizations. This validation ensures that our market sizing reflects actual trade flows rather than survey-based estimates alone.
Our approach employs simultaneous top-down and bottom-up data triangulation. Top-down modeling allocates macroeconomic indicators and industry segment data to derive addressable market boundaries. Bottom-up modeling builds from manufacturer capacity, product pricing, and end-use consumption patterns to cross-validate. Where discrepancies arise, we prioritize traceable trade flow data over derived estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |