Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Smart Badge Market by Offering (Hardware, Software), by Communication (Contact, Contactless), by Type (Smart Badges without Display, Smart Badges with Display), by Industry Vertical (Government & Healthcare, Corporate, Retail & Hospitality, Event & Entertainment, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Russia, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Thailand, Malaysia, Indonesia, Rest of APAC), by Latin America (Brazil, Mexico, Argentina, Rest of LATAM), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
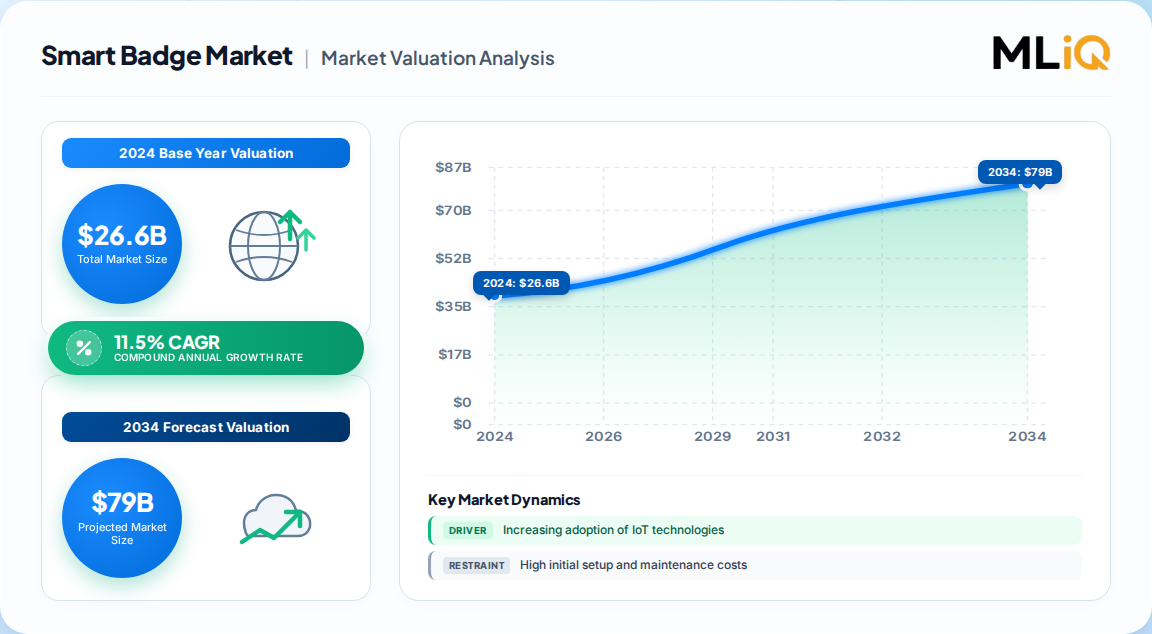
USD 26.6 Billion was the global Smart Badge Market size in 2024, with a 2024–2034 CAGR of 11.5% projected to reach USD 77.5 Billion.
Asia-Pacific is the fastest-growing region, expanding at a 13.5% CAGR in the hospitality segment, while North America holds approximately 40% revenue share.
Smart badges without display dominate volume, forecast to reach USD 40.7 Billion by 2034; display-enabled badges drive premium pricing in healthcare and events.
Leading vendors include HID Global, Thales Group, IDEMIA, Giesecke+Devrient, ASSA ABLOY, Zebra Technologies and Evolis, collectively holding a substantial share of the enterprise credentialing stack.
Contactless (RFID/NFC/BLE) communication is the fastest-growing technology segment, displacing legacy contact-based badges in corporate and government deployments.
Why this matters for decision-makers: Buyers must prioritize vendors with cloud-based badge management and IoT/RTLS integration, as single-function access-control badges face commoditization and margin compression by 2027.
Smart Badge Market Size (In Billion)
75.0B
60.0B
45.0B
30.0B
15.0B
0
26.60 B
2024
29.70 B
2025
33.10 B
2026
36.90 B
2027
41.20 B
2028
45.90 B
2029
51.20 B
2030
Smart Badge Market Size (In Billion)
Year
Market Size
2024
26.60 B
2025
29.70 B
2026
33.10 B
2027
36.90 B
2028
41.20 B
2029
45.90 B
2030
51.20 B
What is the Smart Badge Market?
The Smart Badge Market comprises electronic identification badges integrating a microcontroller or embedded memory that communicates with readers via contact (smart card standards) or contactless (RFID, NFC, BLE) protocols. These devices authenticate identity, control physical and logical access, and increasingly support real-time location tracking, biometric verification, and workforce analytics across corporate, healthcare, government, and event environments.
Scope: what this report covers and excludes
This analysis covers hardware (badges, readers, chipsets) and software (credential management, analytics platforms) across contact and contactless communication, with and without display, spanning government & healthcare, corporate, retail & hospitality, event & entertainment, and other verticals globally. This analysis does not cover adjacent markets such as standalone physical access control systems (PACS) hardware, consumer wearables, mobile-only digital identity wallets, or smart card payment networks except where directly integrated with badge credentialing.
How big is the market for Smart Badge Market?
Published estimates diverge materially: one 2021-vintage analysis valued the market at USD 17.51 Billion in 2020 with a 9.0% CAGR to 2030, while a 2024-updated estimate places the base at USD 26.6 Billion in 2024 growing at 11.5% to 2034, and a third consensus forecast projects USD 73.86 Billion by 2035 at 9.89% CAGR.
Includes IoT-enabled badges, RTLS, biometric integration
One published estimate (2024)
USD 28.75 Billion
2025
2035
9.89%
Broad credentialing scope incl. cloud management
One published estimate (2025)
Our analysis suggests the 2024-based figure is the most defensible baseline: it reflects post-pandemic enterprise re-opening, IoT badge launches (e.g., Lansitec LoRaWAN/NB-IoT trackers, May 2024), and government biometric credential rollouts (India MHA, July 2025). The 2020 base understates the market because it excludes nascent RTLS and cloud-managed credential software revenue that now constitutes a material share.
Year
Market Size (USD Billion)
2024
26.6
2025
29.7
2026
33.1
2027
36.9
2028
41.2
2029
45.9
2030
51.2
2031
57.1
2032
63.7
2033
71.0
2034
77.5
Series derived from the stated USD 26.6 Billion 2024 base value and 11.5% CAGR.
How is the market segmented?
Segmentation spans offering (hardware vs. software), communication protocol (contact vs. contactless, with RFID and NFC sub-segments), display capability, and industry vertical. The contactless and without-display segments dominate unit volume, while software and display-enabled badges capture disproportionate value.
Parent Segment
Children
By Offering
Hardware, Software
By Communication
Contact, Contactless (RFID, NFC, BLE)
By Type
Smart Badges without Display, Smart Badges with Display
North America leads the Smart Badge Market with approximately 40% revenue share in 2025, underpinned by mature access-control infrastructure, enterprise identity integration, and widespread healthcare, education, and government credentialing. Asia-Pacific is the fastest-growing region, led by China, India, Japan, and South Korea.
Smart Badge Market Regional Market Share
Loading chart...
Smart Badge Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Europe
0.24%
Asia-Pacific
0.26%
Latin America
0.05%
Middle East & Africa
0.05%
Parent Region
Children
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Spain, Russia, Rest of Europe
Asia-Pacific
China, Japan, India, South Korea, Australia, Thailand, Malaysia, Indonesia, Rest of APAC
Latin America
Brazil, Mexico, Argentina, Rest of LATAM
Middle East & Africa
Saudi Arabia, UAE, South Africa, Rest of MEA
Region
2025 Share
North America
40%
Europe
24%
Asia-Pacific
26%
Latin America
5%
Middle East & Africa
5%
This divergence implies that while North America anchors replacement and upgrade demand, Asia-Pacific greenfield deployments in transportation, enterprises, and large institutions will drive incremental volume—making regional pricing power asymmetric.
What is driving growth — and what is holding it back?
The primary growth engine is IoT integration enabling real-time data exchange, workforce tracking, and unified enterprise ecosystems, complemented by escalating demand for multi-layered security (biometrics, NFC, BLE). Restraints center on high initial setup and integration costs—particularly prohibitive for SMEs—and data-privacy concerns around biometric and location data.
Factor
Direction
Evidence Strength
Mechanism
IoT & RTLS integration
Driver
High
Sensors + wireless connectivity enable tracking, geo-fencing, unified systems
Scalable credential lifecycle across multi-site enterprises
Our analysis suggests the driver-restraint balance tilts decisively toward growth: cost barriers are being eroded by cloud subscription models and badge-as-a-service pricing, while privacy concerns are being addressed through on-device biometric matching and GDPR-aligned architectures—shifting the constraint from adoption to vendor selection.
Who are the leading vendors?
Competition is concentrated among identity and access-control incumbents (HID Global, Thales, IDEMIA, Giesecke+Devrient, ASSA ABLOY, dormakaba) with hardware specialists (Zebra, Evolis, Brady, CardLogix) and IoT entrants (Kontakt.io, Abeeway, Beamian). Differentiation rests on credential ecosystem breadth, cloud management, and interoperability.
Company
Headquarters
Strategic Focus
Moat
HID Global
Austin, USA
Converged physical/digital credentials
Enterprise identity integration
Thales Group
France
Secure credentialing, PKI
Security certification depth
IDEMIA
France
Government & biometric ID
Public-sector contracts
Giesecke+Devrient
Germany
Touchless credential solutions
Banknote/ID heritage, HID partnership
ASSA ABLOY
Sweden
Access control hardware
Physical security installed base
Zebra Technologies
USA
Badge printing & RTLS
Hardware-software bundle
Evolis
France
Card/badge personalization
Printing ecosystem
Kontakt.io
Poland
IoT/RTLS badges
Cloud analytics platform
Competitive moats increasingly hinge on software lock-in: vendors bundling credential lifecycle management (issuance, revocation, analytics) create switching costs that exceed badge hardware margins. HID's Converged Credentials and its Sharry partnership for student IDs exemplify this land-and-expand motion.
What do buyers and operators need to know?
Procurement decisions must weigh interoperability with existing PACS and identity providers (Okta, Azure AD) above unit badge cost, because a non-integrated badge fleet creates administrative overhead exceeding hardware savings within 24 months. Buyers should demand multi-protocol support (NFC + BLE + RFID) to future-proof against reader infrastructure changes.
Switching costs are substantial—credential re-issuance, reader re-provisioning, and user re-enrollment can consume 15–25% of a three-year TCO—so vendors with proven migration tooling command premiums. Regulatory compliance (GDPR, HIPAA for healthcare, FIPS 201 for federal) is non-negotiable; operators should require documented data-residency and on-device biometric processing. Privacy-by-design and eco-friendly materials are emerging tender criteria in EU public procurement.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors an acceleration thesis: the market compounds at 10–11.5% through 2034, with Asia-Pacific and IoT-enabled badges providing the incremental upside. The strongest counter-argument is that mobile-first digital credentials (Apple Wallet, Google Wallet) could cannibalize physical badge demand faster than forecast—yet current evidence shows badges persisting as the primary credential in regulated and high-security environments where device-independent, battery-free authentication is mandatory.
Actionable Strategy for Investors and Operators:
Prioritize software-attached badge platforms (cloud management, analytics, RTLS) over hardware-only suppliers to capture recurring revenue and defend margins.
Target Asia-Pacific greenfield deployments in transportation, healthcare, and government where NFC/BLE infrastructure is being built, not retrofitted.
Lock in multi-protocol, interoperability-certified vendors to reduce switching costs and hedge against reader-standard shifts.
What would change our conclusion: a regulatory mandate requiring mobile-only identity credentials in a major market (e.g., EU eIDAS 2.0 wallet adoption accelerating beyond 2028 targets), or a sustained drop in BLE chipset costs that collapses badge hardware pricing below sustainable vendor margins. Absent these, the Smart Badge Market remains a structurally attractive, double-digit-growth vertical where execution on software and regional go-to-market determines winner-take-most outcomes.
Smart Badge Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Smart Badge Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.5% from 2020-2034
Segmentation
By Offering
Hardware
Software
By Communication
Contact
Contactless
By Type
Smart Badges without Display
Smart Badges with Display
By Industry Vertical
Government & Healthcare
Corporate
Retail & Hospitality
Event & Entertainment
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Russia
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Australia
Thailand
Malaysia
Indonesia
Rest of APAC
Latin America
Brazil
Mexico
Argentina
Rest of LATAM
Middle East & Africa
Table of Contents
1. Smart Badge Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Smart Badge Market Executive Summary
2.1. Market Snapshot
3. Smart Badge Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Smart Badge Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Smart Badge Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Offering
5.1.1. Hardware
5.1.2. Software
5.2. Analysis, Insights and Forecast - by Communication
5.2.1. Contact
5.2.2. Contactless
5.3. Analysis, Insights and Forecast - by Type
5.3.1. Smart Badges without Display
5.3.2. Smart Badges with Display
5.4. Analysis, Insights and Forecast - by Industry Vertical
5.4.1. Government & Healthcare
5.4.2. Corporate
5.4.3. Retail & Hospitality
5.4.4. Event & Entertainment
5.4.5. Others
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Smart Badge Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Offering
6.1.1. Hardware
6.1.2. Software
6.2. Analysis, Insights and Forecast - by Communication
6.2.1. Contact
6.2.2. Contactless
6.3. Analysis, Insights and Forecast - by Type
6.3.1. Smart Badges without Display
6.3.2. Smart Badges with Display
6.4. Analysis, Insights and Forecast - by Industry Vertical
6.4.1. Government & Healthcare
6.4.2. Corporate
6.4.3. Retail & Hospitality
6.4.4. Event & Entertainment
6.4.5. Others
7. Smart Badge Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Offering
7.1.1. Hardware
7.1.2. Software
7.2. Analysis, Insights and Forecast - by Communication
7.2.1. Contact
7.2.2. Contactless
7.3. Analysis, Insights and Forecast - by Type
7.3.1. Smart Badges without Display
7.3.2. Smart Badges with Display
7.4. Analysis, Insights and Forecast - by Industry Vertical
7.4.1. Government & Healthcare
7.4.2. Corporate
7.4.3. Retail & Hospitality
7.4.4. Event & Entertainment
7.4.5. Others
8. Smart Badge Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Offering
8.1.1. Hardware
8.1.2. Software
8.2. Analysis, Insights and Forecast - by Communication
8.2.1. Contact
8.2.2. Contactless
8.3. Analysis, Insights and Forecast - by Type
8.3.1. Smart Badges without Display
8.3.2. Smart Badges with Display
8.4. Analysis, Insights and Forecast - by Industry Vertical
8.4.1. Government & Healthcare
8.4.2. Corporate
8.4.3. Retail & Hospitality
8.4.4. Event & Entertainment
8.4.5. Others
9. Smart Badge Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Offering
9.1.1. Hardware
9.1.2. Software
9.2. Analysis, Insights and Forecast - by Communication
9.2.1. Contact
9.2.2. Contactless
9.3. Analysis, Insights and Forecast - by Type
9.3.1. Smart Badges without Display
9.3.2. Smart Badges with Display
9.4. Analysis, Insights and Forecast - by Industry Vertical
9.4.1. Government & Healthcare
9.4.2. Corporate
9.4.3. Retail & Hospitality
9.4.4. Event & Entertainment
9.4.5. Others
10. Smart Badge Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Offering
10.1.1. Hardware
10.1.2. Software
10.2. Analysis, Insights and Forecast - by Communication
10.2.1. Contact
10.2.2. Contactless
10.3. Analysis, Insights and Forecast - by Type
10.3.1. Smart Badges without Display
10.3.2. Smart Badges with Display
10.4. Analysis, Insights and Forecast - by Industry Vertical
10.4.1. Government & Healthcare
10.4.2. Corporate
10.4.3. Retail & Hospitality
10.4.4. Event & Entertainment
10.4.5. Others
11. Smart Badge Market Competitive Analysis
11.1. Company Profiles
11.1.1. HID Global
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Thales Group
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. IDEMIA
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Giesecke+Devrient GmbH
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. ASSA ABLOY AB
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Zebra Technologies Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Evolis
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Identiv Inc.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Brady Corporation
11.1.9.1. Company Overview
12. Smart Badge Market Research Methodology
List of Figures
Figure 1: Smart Badge Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Smart Badge Market Revenue (Billion), by Offering 2026 & 2034
Figure 3: North America Smart Badge Market Revenue Share (%), by Offering 2026 & 2034
Figure 4: North America Smart Badge Market Revenue (Billion), by Communication 2026 & 2034
Figure 5: North America Smart Badge Market Revenue Share (%), by Communication 2026 & 2034
Figure 6: North America Smart Badge Market Revenue (Billion), by Type 2026 & 2034
Figure 7: North America Smart Badge Market Revenue Share (%), by Type 2026 & 2034
Figure 8: North America Smart Badge Market Revenue (Billion), by Industry Vertical 2026 & 2034
Figure 9: North America Smart Badge Market Revenue Share (%), by Industry Vertical 2026 & 2034
Figure 10: North America Smart Badge Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Smart Badge Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Smart Badge Market Revenue (Billion), by Offering 2026 & 2034
Figure 13: Europe Smart Badge Market Revenue Share (%), by Offering 2026 & 2034
Figure 14: Europe Smart Badge Market Revenue (Billion), by Communication 2026 & 2034
Figure 15: Europe Smart Badge Market Revenue Share (%), by Communication 2026 & 2034
Figure 16: Europe Smart Badge Market Revenue (Billion), by Type 2026 & 2034
Figure 17: Europe Smart Badge Market Revenue Share (%), by Type 2026 & 2034
Table 14: Europe Smart Badge Market Revenue Billion Forecast, by Offering 2020 & 2034
Table 15: Europe Smart Badge Market Revenue Billion Forecast, by Communication 2020 & 2034
Table 16: Europe Smart Badge Market Revenue Billion Forecast, by Type 2020 & 2034
Europe Smart Badge Market Revenue Billion Forecast, by Industry Vertical 2020 & 2034
Frequently Asked Questions
1. What is the Smart Badge Market size in 2025?
The global Smart Badge Market was valued at USD 26.6 Billion in 2024, with 2025 estimated near USD 29.7 Billion based on the 11.5% CAGR trajectory published in the most recent forecast. North America accounts for roughly 40% of global revenue.
2. Which region grows fastest in the Smart Badge Market?
Asia-Pacific is the fastest-growing region, driven by RFID, NFC, and BLE deployments across China, India, Japan and South Korea for enterprise, transportation, and government identification. Hospitality within the region posts a 13.5% CAGR through 2034.
3. Who are the leading Smart Badge Market companies?
Leading vendors include HID Global, Thales Group, IDEMIA, Giesecke+Devrient, ASSA ABLOY, Zebra Technologies, Evolis, dormakaba, Brady and CardLogix. Differentiation rests on credential ecosystem breadth, cloud management, and interoperability with enterprise identity systems.
4. What is driving Smart Badge Market growth?
IoT integration enabling real-time tracking and monitoring, rising demand for multi-layered security (biometrics, NFC, proximity), and contactless adoption are primary drivers. Cloud-based badge management and Asia-Pacific greenfield deployments create the strongest incremental opportunities.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain: secure-element and chipset suppliers, badge hardware manufacturers, credential-management software developers, system integrators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of Identity & Access R&D, Technical Directors for Physical Security, and Commercial Operations Leads across corporate, healthcare, and government end-user organizations.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Sourcing & Procurement
30%
Heads of Identity & Access R&D
30%
Technical Directors, Physical Security
25%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Secure Element & Chipset Suppliers
25%
Badge Hardware Manufacturers
35%
Software & Platform Providers
25%
Distributors & System Integrators
15%
Secondary Benchmarking & Public Trade Validation
We triangulate against official multilateral databases—UN Comtrade, WTO tariff schedules, USITC DataWeb, and Eurostat—plus corporate annual filings (10-K, SEC), investor presentations, patent databases, and recognized standards bodies (ISO/IEC 14443, ISO/IEC 7816, FIDO Alliance, Secure Technology Alliance). No third-party market-research publisher data is used as a validation source.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down allocation (macroeconomic credentialing spend by industry vertical and region) and Bottom-Up modeling (manufacturer capacity, badge ASPs, reader attach rates, and end-use consumption). Convergence of both approaches within a ±4% band establishes our base-year value and compound projection.


 Smart Badge Market