Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Borescope Market Size, Share & Forecast to 2035
Borescope Market
Borescope Market Size, Share & Forecast to 2035
Borescope Market by Technology (Videoscope, Fiberscope, Semi-Rigid Borescope, Rigid Borescope, Optical, Ultrasound), by Diameter (0-3 mm, 3-6 mm, 6-10 mm, Above 10 mm), by Viewing Angle (0-90 degrees, 90-180 degrees, 180-360 degrees), by End-User Vertical (Aerospace, Automotive, Oil & Gas, Energy & Power, Chemicals, Metallurgical, Manufacturing), by Function (Maintenance, Inspection, Quality Control), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
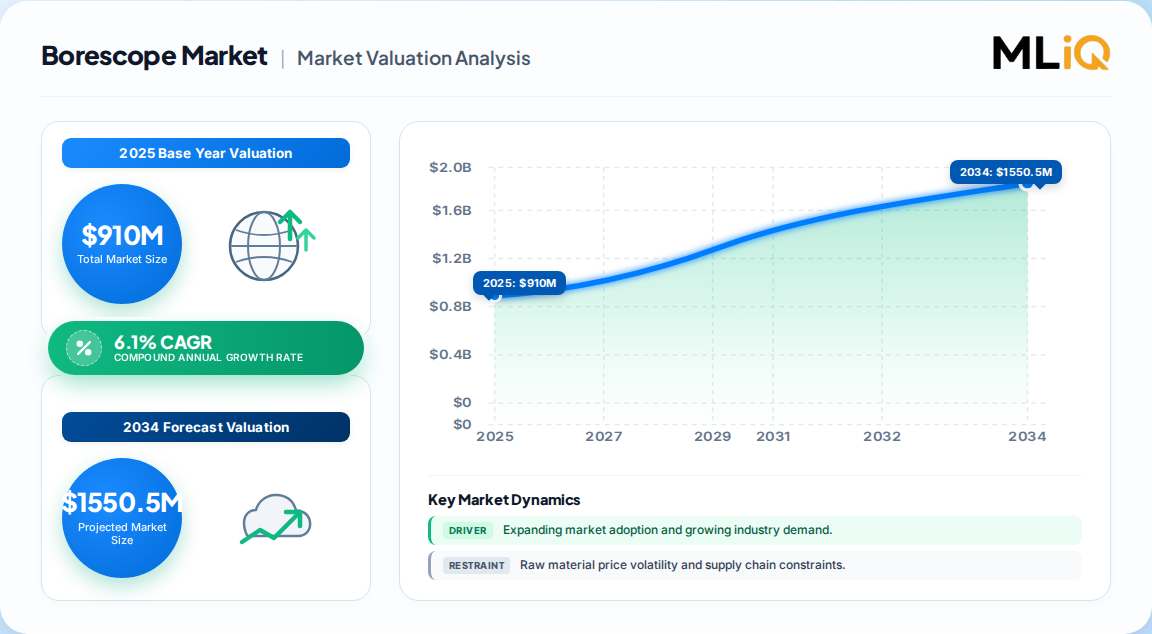
910 Million in 2025 revenue, rising to 1,616 Million by 2035 at a consensus 6.1% CAGR — roughly a 1.8x expansion in a decade.
Videoscopes lead technology, at 44.5% to 60% share depending on definition, as articulating CMOS systems displace rigid fiberscopes.
Aviation accounts for ~29.5% of demand; oil and gas is the fastest vertical at 7.7% CAGR, tied to midstream pipeline build-out.
North America holds ~35% of global revenue; Asia-Pacific is the fastest region at 7.1% CAGR, led by India's industrialization.
Olympus/Evident, Baker Hughes, Karl Storz, SKF, Fluke and Vizaar anchor a moderately concentrated vendor field.
Aging power assets and AI defect detection are structural, multi-year tailwinds; upfront cost and technician scarcity are the binding constraints.
Why this matters for decision-makers: The revenue pool is shifting from hardware sales toward inspection-as-a-service and compliance documentation — vendors that cannot bundle software, traceability and AI diagnostics will face steady margin compression even as unit volumes grow.
Borescope Market Size (In Million)
1.5B
1.0B
500.0M
0
910.0 M
2025
966.0 M
2026
1.020 B
2027
1.090 B
2028
1.150 B
2029
1.220 B
2030
1.300 B
2031
Borescope Market Size (In Million)
Year
Market Size
2025
910.0 M
2026
966.0 M
2027
1.020 B
2028
1.090 B
2029
1.150 B
2030
1.220 B
2031
1.300 B
What is the Borescope Market?
The borescope market covers the manufacture and supply of optical and video inspection instruments — rigid, flexible, fiberscope and videoscope — used to visually examine internal cavities, chambers and pipelines without disassembly, plus the associated software, probes, repair services and calibration contracts sold into industrial and medical inspection workflows.
Scope: what this report covers and excludes
Scope level is global, and this analysis segments demand by technology, probe diameter, viewing angle, end-user vertical and region, tracking equipment revenue, service revenue and aftermarket consumables through 2035. Sub-segment pricing within individual OEM channels is treated qualitatively rather than forecast. This analysis does not cover medical endoscopes used in therapeutic or diagnostic clinical procedures, consumer-grade inspection cameras sold through retail channels, or adjacent drone-based and robotic crawler inspection platforms except as competitive context.
How big is the market for Borescope Market?
Published valuations for 2025 cluster between 819 Million and 910 Million, with 2035 forecasts between 1.45 Billion and 1.62 Billion, a spread wide enough that buyers should anchor on the growth rate rather than the absolute base.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
910 Million
2025
2035
5.9%
Video/optical/ultrasound borescopes, industrial end use
One published vendor-side analysis
883.73 Million
2025
2035
5.1%
By technology, diameter, end user; excludes services
Our analysis favours the mid-to-upper band at roughly 910 Million base and 6.1% CAGR, because the lower estimates visibly exclude borescope repair, calibration and probe replacement revenue, which grows faster than hardware as installed bases age. The implied 2035 value of about 1.62 Billion therefore sits at the higher end of the published range but remains defensible when service attach rates are included.
How is the market segmented?
Segmentation matters because the fastest-growing slices — oil and gas, sub-3mm probes and articulating videoscopes — are precisely where premium pricing is still intact.
Videoscopes hold 44.5% to 47.6% of technology revenue; the 0–3 mm diameter band contributes about 42.9% and the 0°–90° angle band about 55.2%. Our analysis suggests the 0–3 mm band is the single most strategically contested slice: it is the entry point for turbine-blade and EV battery-pack work, where probe fragility drives recurring replacement revenue.
Which region leads in Borescope Market?
North America leads with roughly 35% of global revenue, underpinned by an aerospace MRO base and strict pipeline safety enforcement; Asia-Pacific is the fastest-growing region at about 7.1% CAGR.
Borescope Market Regional Market Share
Loading chart...
Borescope Market Regional Market Share
Region
Market Share (%)
North America
0.35%
Europe
0.27%
Asia-Pacific
0.29%
South America
0.05%
Middle East & Africa
0.04%
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy
Asia Pacific — China, Japan, India, South Korea, ASEAN
Latin America — Brazil, Argentina, Mexico
Middle East & Africa — Saudi Arabia, UAE, South Africa
Region
Share of global revenue
North America
35%
Asia-Pacific
29%
Europe
27%
South America
5%
Middle East & Africa
4%
Europe's ~27% share is concentrated in German and French automotive hubs, where EN 13018 documentation duties push buyers toward cloud-connected systems at higher average selling prices. The divergence implies that volume growth is shifting east while price realisation stays west — a margin-relevant split for any vendor building a channel strategy.
What is driving growth — and what is holding it back?
Aging critical infrastructure and tightening aviation directives are the strongest forces adding to growth, while high upfront cost and technician scarcity are the clearest drags.
Factor
Direction
Evidence strength
Mechanism
Aging critical infrastructure
+1.3% CAGR
High (utility capex data)
Mandated turbine and boiler inspection
AI-based defect detection
+1.1% CAGR
Medium-high (OEM deployments)
Cuts outage hours, justifies premium systems
Aviation airworthiness directives
+0.9% CAGR
High (FAA/EASA rule counts)
Mandates documented internal engine inspection
Midstream pipeline expansion
+0.8% CAGR
Medium (28 Billion 2024 spend)
Corrosion monitoring at commissioning
CMOS and articulation miniaturization
+0.7% CAGR
Medium
Enables access to smaller cavities
High upfront system cost
−0.6% CAGR
High
25,000–65,000 price points block SMEs
Drone and robotic inspection competition
−0.5% CAGR
Medium
Substitutes for external surface work
Certified technician shortage
−0.4% CAGR
Medium
Caps utilisation of installed base
The net balance is decisively positive. Our analysis suggests the restraints are cyclical and price-driven rather than structural: cost barriers erode with each CMOS generation, whereas regulatory inspection duties are ratchets that almost never reverse. That asymmetry is the core reason the forecast band skews upward.
Who are the leading vendors?
Olympus/Evident, Baker Hughes, Karl Storz, SKF, Fluke and Vizaar are the most frequently cited leaders, with competition centred on imaging resolution, probe articulation and software ecosystems rather than on price alone.
Vendor
Primary strength
Typical moat
Olympus / Evident
Aerospace and industrial videoscopes
Installed base, service network, brand trust
Baker Hughes
Oil and gas pipeline inspection
Bundled NDT service contracts
Karl Storz
Precision optics
Optical engineering depth
SKF
Reliability engineering integration
Maintenance data adjacency
Fluke
Portable diagnostics
Distribution reach, price-tier coverage
Vizaar
Industrial imaging systems
Niche customisation
Gradient Lens, Lenox, Moritex, RF System Lab
Rigid and specialty borescopes
Low-cost rigid optics, niche probes
Differentiation is converging on software. Hardware resolution is approaching commoditisation at the mid-tier, so defensible moats now sit in image analytics, report generation and audit trail integrity — the features procurement teams cite when justifying premium pricing to finance.
What do buyers and operators need to know? (Decision Support)
Selection criteria should be weighted by consequence of failure, not by list price. In aviation and power generation, probe diameter and articulation range determine whether an inspection is physically possible; in pipeline and chemical work, illumination durability and insertion length dominate.
Procurement risk concentrates in three areas: counterfeit and grey-market probes that fail certification, software lock-in where image archives cannot migrate between platforms, and calibration lapses that invalidate inspection reports. Buyers should contract explicitly for data portability and for service-level turnaround on probe repair, since downtime cost typically exceeds instrument cost within a single outage window.
Switching costs rise sharply once a fleet standardises on one articulation system and one reporting platform, because technician retraining and archive migration both carry real cost. Regulatory compliance is the non-negotiable layer — documentation must be time-stamped and auditable to satisfy FAA, EASA and EN 13018 expectations, which effectively rules out consumer-grade substitutes in safety-critical use.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours the upper half of the published forecast range, with the strongest counter-argument being that drone and robotic inspection platforms could absorb a meaningful share of external and large-cavity work by the early 2030s. We regard that risk as real but bounded: drones cannot satisfy internal turbine-blade documentation duties, which remain the single largest revenue pool.
The more underappreciated risk is the technician gap. Instruments are becoming easier to operate, but certified interpretation remains scarce, which caps how quickly installed bases are utilised and explains why AI-assisted defect detection is being adopted faster than general hardware upgrades.
Operators: Bundle calibration, repair and archive management into multi-year contracts rather than buying instruments transactionally, and lock data portability into the agreement.
Vendors: Prioritise AI overlay and audit-ready reporting to defend pricing, and target sub-3mm articulating probes for aviation and EV battery inspection.
Investors: Weight exposure toward service and software attach rates rather than unit shipments, since hardware margins face downward pressure from low-cost imports.
The evidence that would change our conclusion is a sustained fall in premium videoscope average selling prices below 20,000 with no loss of resolution — that would signal genuine commoditisation and collapse the service-premium thesis.
Borescope Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Borescope Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.1% from 2020-2034
Segmentation
By Technology
Videoscope
Fiberscope
Semi-Rigid Borescope
Rigid Borescope
Optical
Ultrasound
By Diameter
0-3 mm
3-6 mm
6-10 mm
Above 10 mm
By Viewing Angle
0-90 degrees
90-180 degrees
180-360 degrees
By End-User Vertical
Aerospace
Automotive
Oil & Gas
Energy & Power
Chemicals
Metallurgical
Manufacturing
By Function
Maintenance
Inspection
Quality Control
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Borescope Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Borescope Market Executive Summary
2.1. Market Snapshot
3. Borescope Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Borescope Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Borescope Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Technology
5.1.1. Videoscope
5.1.2. Fiberscope
5.1.3. Semi-Rigid Borescope
5.1.4. Rigid Borescope
5.1.5. Optical
5.1.6. Ultrasound
5.2. Analysis, Insights and Forecast - by Diameter
5.2.1. 0-3 mm
5.2.2. 3-6 mm
5.2.3. 6-10 mm
5.2.4. Above 10 mm
5.3. Analysis, Insights and Forecast - by Viewing Angle
5.3.1. 0-90 degrees
5.3.2. 90-180 degrees
5.3.3. 180-360 degrees
5.4. Analysis, Insights and Forecast - by End-User Vertical
5.4.1. Aerospace
5.4.2. Automotive
5.4.3. Oil & Gas
5.4.4. Energy & Power
5.4.5. Chemicals
5.4.6. Metallurgical
5.4.7. Manufacturing
5.5. Analysis, Insights and Forecast - by Function
5.5.1. Maintenance
5.5.2. Inspection
5.5.3. Quality Control
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Borescope Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Technology
6.1.1. Videoscope
6.1.2. Fiberscope
6.1.3. Semi-Rigid Borescope
6.1.4. Rigid Borescope
6.1.5. Optical
6.1.6. Ultrasound
6.2. Analysis, Insights and Forecast - by Diameter
6.2.1. 0-3 mm
6.2.2. 3-6 mm
6.2.3. 6-10 mm
6.2.4. Above 10 mm
6.3. Analysis, Insights and Forecast - by Viewing Angle
6.3.1. 0-90 degrees
6.3.2. 90-180 degrees
6.3.3. 180-360 degrees
6.4. Analysis, Insights and Forecast - by End-User Vertical
6.4.1. Aerospace
6.4.2. Automotive
6.4.3. Oil & Gas
6.4.4. Energy & Power
6.4.5. Chemicals
6.4.6. Metallurgical
6.4.7. Manufacturing
6.5. Analysis, Insights and Forecast - by Function
6.5.1. Maintenance
6.5.2. Inspection
6.5.3. Quality Control
7. Borescope Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Technology
7.1.1. Videoscope
7.1.2. Fiberscope
7.1.3. Semi-Rigid Borescope
7.1.4. Rigid Borescope
7.1.5. Optical
7.1.6. Ultrasound
7.2. Analysis, Insights and Forecast - by Diameter
7.2.1. 0-3 mm
7.2.2. 3-6 mm
7.2.3. 6-10 mm
7.2.4. Above 10 mm
7.3. Analysis, Insights and Forecast - by Viewing Angle
7.3.1. 0-90 degrees
7.3.2. 90-180 degrees
7.3.3. 180-360 degrees
7.4. Analysis, Insights and Forecast - by End-User Vertical
7.4.1. Aerospace
7.4.2. Automotive
7.4.3. Oil & Gas
7.4.4. Energy & Power
7.4.5. Chemicals
7.4.6. Metallurgical
7.4.7. Manufacturing
7.5. Analysis, Insights and Forecast - by Function
7.5.1. Maintenance
7.5.2. Inspection
7.5.3. Quality Control
8. Borescope Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Technology
8.1.1. Videoscope
8.1.2. Fiberscope
8.1.3. Semi-Rigid Borescope
8.1.4. Rigid Borescope
8.1.5. Optical
8.1.6. Ultrasound
8.2. Analysis, Insights and Forecast - by Diameter
8.2.1. 0-3 mm
8.2.2. 3-6 mm
8.2.3. 6-10 mm
8.2.4. Above 10 mm
8.3. Analysis, Insights and Forecast - by Viewing Angle
8.3.1. 0-90 degrees
8.3.2. 90-180 degrees
8.3.3. 180-360 degrees
8.4. Analysis, Insights and Forecast - by End-User Vertical
8.4.1. Aerospace
8.4.2. Automotive
8.4.3. Oil & Gas
8.4.4. Energy & Power
8.4.5. Chemicals
8.4.6. Metallurgical
8.4.7. Manufacturing
8.5. Analysis, Insights and Forecast - by Function
8.5.1. Maintenance
8.5.2. Inspection
8.5.3. Quality Control
9. Borescope Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Technology
9.1.1. Videoscope
9.1.2. Fiberscope
9.1.3. Semi-Rigid Borescope
9.1.4. Rigid Borescope
9.1.5. Optical
9.1.6. Ultrasound
9.2. Analysis, Insights and Forecast - by Diameter
9.2.1. 0-3 mm
9.2.2. 3-6 mm
9.2.3. 6-10 mm
9.2.4. Above 10 mm
9.3. Analysis, Insights and Forecast - by Viewing Angle
9.3.1. 0-90 degrees
9.3.2. 90-180 degrees
9.3.3. 180-360 degrees
9.4. Analysis, Insights and Forecast - by End-User Vertical
9.4.1. Aerospace
9.4.2. Automotive
9.4.3. Oil & Gas
9.4.4. Energy & Power
9.4.5. Chemicals
9.4.6. Metallurgical
9.4.7. Manufacturing
9.5. Analysis, Insights and Forecast - by Function
9.5.1. Maintenance
9.5.2. Inspection
9.5.3. Quality Control
10. Borescope Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Technology
10.1.1. Videoscope
10.1.2. Fiberscope
10.1.3. Semi-Rigid Borescope
10.1.4. Rigid Borescope
10.1.5. Optical
10.1.6. Ultrasound
10.2. Analysis, Insights and Forecast - by Diameter
10.2.1. 0-3 mm
10.2.2. 3-6 mm
10.2.3. 6-10 mm
10.2.4. Above 10 mm
10.3. Analysis, Insights and Forecast - by Viewing Angle
10.3.1. 0-90 degrees
10.3.2. 90-180 degrees
10.3.3. 180-360 degrees
10.4. Analysis, Insights and Forecast - by End-User Vertical
10.4.1. Aerospace
10.4.2. Automotive
10.4.3. Oil & Gas
10.4.4. Energy & Power
10.4.5. Chemicals
10.4.6. Metallurgical
10.4.7. Manufacturing
10.5. Analysis, Insights and Forecast - by Function
10.5.1. Maintenance
10.5.2. Inspection
10.5.3. Quality Control
11. Borescope Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Borescope Market Research Methodology
List of Figures
Figure 1: Borescope Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Borescope Market Revenue (Million), by Technology 2026 & 2034
Figure 3: North America Borescope Market Revenue Share (%), by Technology 2026 & 2034
Figure 4: North America Borescope Market Revenue (Million), by Diameter 2026 & 2034
Figure 5: North America Borescope Market Revenue Share (%), by Diameter 2026 & 2034
Figure 6: North America Borescope Market Revenue (Million), by Viewing Angle 2026 & 2034
Figure 7: North America Borescope Market Revenue Share (%), by Viewing Angle 2026 & 2034
Figure 8: North America Borescope Market Revenue (Million), by End-User Vertical 2026 & 2034
Figure 9: North America Borescope Market Revenue Share (%), by End-User Vertical 2026 & 2034
Figure 10: North America Borescope Market Revenue (Million), by Function 2026 & 2034
Figure 11: North America Borescope Market Revenue Share (%), by Function 2026 & 2034
Figure 12: North America Borescope Market Revenue (Million), by Country 2026 & 2034
Figure 13: North America Borescope Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Borescope Market Revenue (Million), by Technology 2026 & 2034
Figure 15: Europe Borescope Market Revenue Share (%), by Technology 2026 & 2034
Figure 16: Europe Borescope Market Revenue (Million), by Diameter 2026 & 2034
Figure 17: Europe Borescope Market Revenue Share (%), by Diameter 2026 & 2034
List of Tables
Table 1: Borescope Market Revenue Million Forecast, by Technology 2020 & 2034
Table 2: Borescope Market Revenue Million Forecast, by Diameter 2020 & 2034
Table 3: Borescope Market Revenue Million Forecast, by Viewing Angle 2020 & 2034
Table 4: Borescope Market Revenue Million Forecast, by End-User Vertical 2020 & 2034
Table 5: Borescope Market Revenue Million Forecast, by Function 2020 & 2034
Table 6: Borescope Market Revenue Million Forecast, by Region 2020 & 2034
Table 7: North America Borescope Market Revenue Million Forecast, by Technology 2020 & 2034
Table 8: North America Borescope Market Revenue Million Forecast, by Diameter 2020 & 2034
Table 9: North America Borescope Market Revenue Million Forecast, by Viewing Angle 2020 & 2034
Table 10: North America Borescope Market Revenue Million Forecast, by End-User Vertical 2020 & 2034
Table 11: North America Borescope Market Revenue Million Forecast, by Function 2020 & 2034
Table 12: North America Borescope Market Revenue Million Forecast, by Country 2020 & 2034
Table 13: USA Borescope Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Europe Borescope Market Revenue Million Forecast, by Technology 2020 & 2034
Europe Borescope Market Revenue Million Forecast, by Diameter 2020 & 2034
Frequently Asked Questions
1. How fast is the borescope market growing?
Published estimates cluster around a 5.1% to 6.4% CAGR through 2035, with a mid-point of roughly 6.1%. Growth is anchored by regulatory inspection duties in aviation and power generation rather than by discretionary capital spending.
2. Which borescope technology holds the largest share?
Videoscopes lead, accounting for roughly 44.5% to 60% of technology revenue depending on how rigid video systems are classified. Articulating CMOS videoscopes are displacing legacy rigid fiberscopes across aviation, power and automotive inspection.
3. Which region dominates borescope demand?
North America leads with about 35% of global revenue, driven by aerospace MRO and pipeline safety rules. Asia-Pacific is the fastest-growing region at roughly 7.1% CAGR, led by Indian and Southeast Asian industrialization.
4. What is the biggest barrier to borescope adoption?
Upfront cost is the primary barrier, with premium articulating video systems priced between roughly 25,000 and 65,000. This excludes many small and mid-sized maintenance contractors and sustains a secondary market in refurbished rigid endoscopes.
5. Who are the leading borescope manufacturers?
Olympus/Evident, Baker Hughes, Karl Storz, SKF, Fluke and Vizaar are most frequently cited, alongside specialty players such as Gradient Lens, Lenox, Moritex and RF System Lab. Competition is shifting toward software and service ecosystems.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Fieldwork comprised structured depth interviews across the value chain: optical component and CMOS sensor suppliers, specialized borescope producers, contract assembly and probe-manufacturing partners, and global industrial distributors serving MRO channels. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D and optical engineering, Technical Directors responsible for inspection standards, and Commercial Operations Leads managing rental and service fleets.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Technical & R&D Directors
38%
Procurement & Sourcing Leads
34%
Quality & Regulatory Managers
28%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Borescope & Optical Instrument Producers
42%
Component & Sensor Suppliers
26%
Industrial Distributors & Rental Fleets
20%
Inspection Service Providers
12%
Secondary Benchmarking & Public Trade Validation
Findings were benchmarked against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings and investor presentations, patent filings covering articulation and CMOS miniaturization, and recognized technical standards bodies including ISO and national aviation and pipeline safety regulators. No third-party market research publications are used as validation inputs.
Demand Modeling & Market Sizing Triangulation
Market sizing runs a simultaneous top-down and bottom-up triangulation. The top-down model allocates macroeconomic industrial production and MRO spending across vertical segments and regions. The bottom-up model aggregates manufacturer capacity, product-level pricing and end-use consumption by diameter and technology band. Divergence between the two is reconciled at segment level.


 Borescope Market