Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
IPS Display Market by Product Type (Standard IPS, Advanced IPS), by Application (Consumer Electronics, Automotive, Healthcare, Industrial & Commercial), by End User (OEMs, Automotive Manufacturers, Healthcare Providers), by Size (Below 20 inches, 20 to 30 inches, 31 to 40 inches, 41 to 50 inches, Above 50 inches), by Technology Variant (Fast IPS, IPS Black, AH-IPS, E-IPS), by Asia Pacific (China, Japan, South Korea, India, Singapore), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Netherlands), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
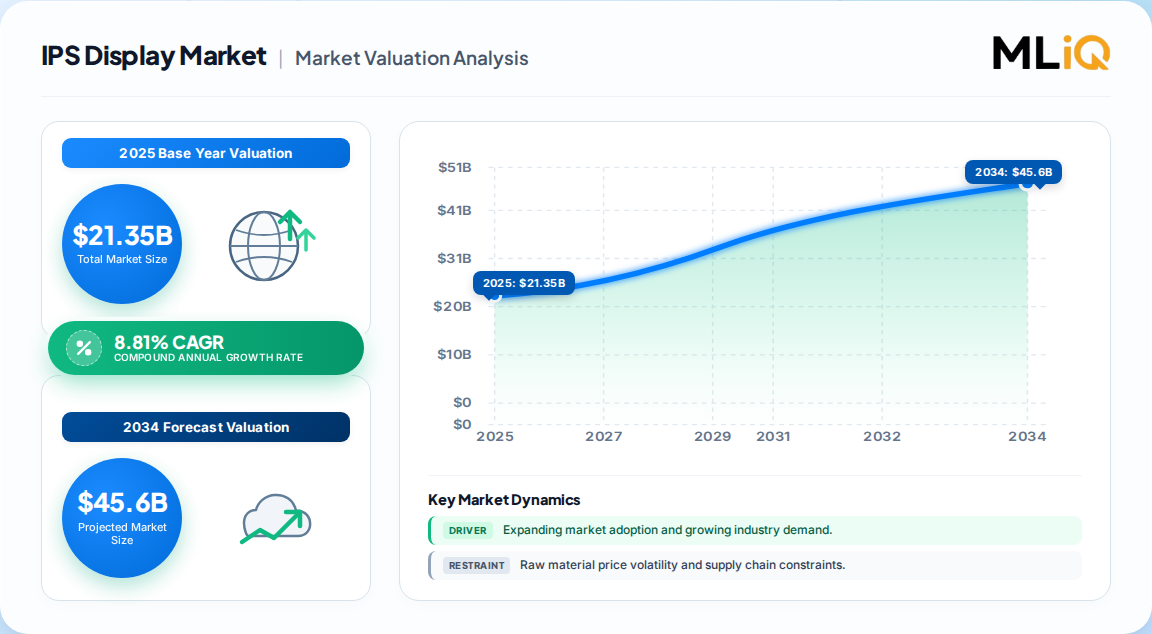
The global IPS Display Market was valued at USD 21.35 Billion in 2025 and is projected to reach USD 45.66 Billion by 2034, a CAGR of 8.81%.
Consumer electronics remains the largest application at roughly 52% share, anchored by tablets, laptops, and monitors.
Automotive is the fastest-growing application (about 22% share, 11.0% CAGR), driven by digital cockpits and multi-screen interiors.
Asia-Pacific leads regionally with roughly 49% of global value, followed by North America (~23%) and Europe (~20%).
Leading vendors include BOE, LG Display, AUO, TCL CSOT, Samsung Display, Innolux, Sharp, and Japan Display.
Standard IPS holds ~62% of value; Advanced IPS (Fast IPS, IPS Black) is growing at ~10.7% and is where premium margin is concentrated.
Why this matters for decision-makers: Panel buyers should lock multi-year Advanced IPS supply for automotive and professional lines now, because capacity is being reallocated toward premium and automotive grades faster than mainstream standard IPS demand is declining.
IPS Display Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
21.35 B
2025
23.23 B
2026
25.28 B
2027
27.51 B
2028
29.93 B
2029
32.57 B
2030
35.44 B
2031
IPS Display Market Size (In Billion)
Year
Market Size
2025
21.35 B
2026
23.23 B
2027
25.28 B
2028
27.51 B
2029
29.93 B
2030
32.57 B
2031
35.44 B
What is the IPS Display Market?
The IPS Display Market covers liquid-crystal panels using In-Plane Switching, a technology that keeps color and contrast stable across wide viewing angles. It spans monitors, laptops, tablets, televisions, smartphones, automotive clusters, medical imaging screens, and industrial interfaces sold as panels or finished displays.
Scope: what this report covers and excludes
This analysis sizes and segments IPS LCD panels and finished IPS display products across consumer electronics, automotive, healthcare, and industrial/commercial applications, globally. It covers both standard and advanced IPS variants and the OEM, automotive-manufacturer, and healthcare-provider end-user channels. This analysis does not cover OLED, Micro-LED, VA, TN, or e-paper as primary markets, nor does it size upstream glass, driver IC, or backlight component supply chains independently.
How big is the IPS Display Market?
Published estimates diverge materially because of differing base years, horizons, and definitions of what counts as an "IPS display". The table below sets out the principal competing estimates side by side.
Broader "IPS displays" definition incl. full device-level value
Older press-release estimate
Our analysis: the ~USD 21 Billion cluster for 2025 is the most defensible base, because three independent estimates converge within 3% of each other and share a similar panel-plus-module definition. The USD 60.72 Billion 2022 figure almost certainly reflects a device-level or broader LCD-inclusive definition and should not be used for panel-level procurement planning. For buyers, the practical implication is that the addressable panel market is roughly USD 21–22 Billion today, with a realistic 2032–2034 terminal value in the USD 38–46 Billion band.
How is the market segmented?
The market segments cleanly along product type, application, end user, and panel size, with advanced variants cutting across every application.
Two structural facts stand out. First, consumer electronics (52%) and OEMs (55%) dominate volume, but both grow below market average (~7.5% and ~7.7%). Second, automotive (22%, 11.0% CAGR) and healthcare (10%, 10.0% CAGR) are the growth engines. Our analysis suggests the automotive application alone will add roughly USD 5 Billion of incremental value by 2032.
Which region leads in IPS Display Market?
Asia-Pacific leads with approximately 49% of global IPS display value in 2025 (about USD 10.34 Billion), reflecting its concentration of panel fabrication, consumer-electronics assembly, and expanding automotive display production. The regional hierarchy is as follows.
IPS Display Market Regional Market Share
Loading chart...
IPS Display Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.49%
North America
0.23%
Europe
0.2%
South America
0.05%
Middle East & Africa
0.04%
Asia-Pacific — China, Japan, South Korea, India, Singapore
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Netherlands
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
Asia-Pacific is also the fastest-growing major region at ~9.5% CAGR, with North America at ~7.8% and Europe at ~8.0%. The implication for buyers is straightforward: panel pricing and allocation decisions are effectively made in Asia-Pacific, even when the end demand sits in North America or Europe. Localization incentives in the US and EU are unlikely to displace Asian fabs as the primary IPS source before the early 2030s.
What is driving growth — and what is holding it back?
Growth is being pulled by four reinforcing demand vectors, while three constraints cap the pace of expansion.
Factor
Direction
Evidence strength
Mechanism
Automotive digital cockpits
Driver
High
Multi-screen interiors raise display content per vehicle; ~11.0% CAGR
Gaming & professional monitors
Driver
High
Fast IPS and IPS Black demand; advanced IPS ~10.7% CAGR
Advanced IPS capacity additions are slow and expensive
The balance: demand-side drivers are structural and multi-year, while restraints are largely price- and mix-related rather than volume-related. Our analysis suggests the net effect is value growth outpacing unit growth, meaning vendors who stay in standard IPS only will see revenue growth but margin compression. The strategic response is a deliberate mix shift toward advanced IPS and automotive-grade qualification.
Who are the leading vendors?
Competition splits between panel manufacturers with broad portfolios and finished-product brands that compete on specification and integration.
Auto IPS for vehicles; strong monitor/laptop IPS base
AUO
Panel manufacturer
Automotive cockpit, mirror, and industrial display depth
TCL CSOT
Panel manufacturer
t9 platform targeting higher-end IT and specialized LCD
Samsung Display
Panel manufacturer
Scale and premium display positioning
Innolux / Sharp / JDI
Panel manufacturers
Regional capacity and specialized segments
Dell (UltraSharp)
Finished monitors
IPS Black professional positioning and channel strength
Differentiation and moats: panel makers compete on contrast improvement, refresh rate, touch integration, and application-specific qualification. The deepest moats sit in automotive and medical qualification, where multi-year design-in cycles and reliability testing create high switching costs. Finished-product brands such as Dell compete on image quality, connectivity, and enterprise channel relationships rather than panel economics.
What do buyers and operators need to know?
Procurement decisions in this market hinge on four criteria that are frequently underweighted. First, application qualification — automotive and medical panels require reliability, luminance-uniformity, and color-accuracy validation that mainstream IT panels do not. Buyers specifying automotive-grade IPS should verify supplier qualification records, not just datasheets. Second, panel-grade clarity — standard IPS and advanced IPS (Fast IPS, IPS Black) differ materially in refresh rate, contrast, and price; conflating them is the most common sourcing error. Third, supply concentration risk — with roughly half of global value produced in Asia-Pacific, buyers should model single-region exposure and consider dual-sourcing for long-life industrial programs. Fourth, regulatory and energy compliance — European ecodesign requirements and safety certifications increasingly shape which panels can be sold into EU and North American channels, adding compliance cost to low-efficiency designs. Switching costs are highest in automotive and medical, moderate in professional monitors, and low in mainstream consumer devices. Operators should also track OLED substitution risk in premium tiers, which affects residual value of long-life display assets.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mix-shift thesis. The market grows at roughly 8.8% CAGR, but that headline hides a two-speed structure: standard IPS grows around 7.5% with eroding margins, while advanced IPS grows around 10.7% and automotive around 11.0% with structurally better pricing. Our judgment is that the winners through 2034 will be vendors and buyers who deliberately overweight advanced IPS and automotive/medical qualification rather than defending volume in commodity standard panels.
The strongest counter-argument is that OLED will collapse the premium tier faster than expected, particularly in tablets, smartphones, and high-end monitors, stranding advanced IPS capacity. That risk is real but bounded: IPS retains durable advantages in cost, lifetime, burn-in resistance, and large-format availability, which is why automotive and industrial buyers continue to specify IPS even as consumer premium migrates to OLED. The more probable outcome is coexistence, with IPS owning the mid-to-upper volume tier.
Actionable strategy:
Buyers/operators: lock multi-year Advanced IPS supply agreements for automotive and professional programs now, before premium capacity tightens.
Investors: favor panel makers with explicit automotive and medical qualification depth over those concentrated in standard IT panels.
Vendors: prioritize fast-response and high-contrast IPS variants to defend against OLED and capture gaming/professional margin.
What would change our conclusion: evidence of accelerated OLED price parity in mid-tier monitors, or a sustained decline in automotive display content per vehicle, would materially weaken the mix-shift thesis and favor a defensive, standard-IPS volume strategy instead.
IPS Display Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
IPS Display Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.81% from 2020-2034
Segmentation
By Product Type
Standard IPS
Advanced IPS
By Application
Consumer Electronics
Automotive
Healthcare
Industrial & Commercial
By End User
OEMs
Automotive Manufacturers
Healthcare Providers
By Size
Below 20 inches
20 to 30 inches
31 to 40 inches
41 to 50 inches
Above 50 inches
By Technology Variant
Fast IPS
IPS Black
AH-IPS
E-IPS
By Geography
Asia Pacific
China
Japan
South Korea
India
Singapore
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Netherlands
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. IPS Display Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. IPS Display Market Executive Summary
2.1. Market Snapshot
3. IPS Display Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. IPS Display Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. IPS Display Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Standard IPS
5.1.2. Advanced IPS
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Consumer Electronics
5.2.2. Automotive
5.2.3. Healthcare
5.2.4. Industrial & Commercial
5.3. Analysis, Insights and Forecast - by End User
5.3.1. OEMs
5.3.2. Automotive Manufacturers
5.3.3. Healthcare Providers
5.4. Analysis, Insights and Forecast - by Size
5.4.1. Below 20 inches
5.4.2. 20 to 30 inches
5.4.3. 31 to 40 inches
5.4.4. 41 to 50 inches
5.4.5. Above 50 inches
5.5. Analysis, Insights and Forecast - by Technology Variant
5.5.1. Fast IPS
5.5.2. IPS Black
5.5.3. AH-IPS
5.5.4. E-IPS
5.6. Analysis, Insights and Forecast - by Region
5.6.1. Asia Pacific
5.6.2. North America
5.6.3. Europe
5.6.4. Latin America
5.6.5. Middle East & Africa
6. IPS Display Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Product Type
6.1.1. Standard IPS
6.1.2. Advanced IPS
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Consumer Electronics
6.2.2. Automotive
6.2.3. Healthcare
6.2.4. Industrial & Commercial
6.3. Analysis, Insights and Forecast - by End User
6.3.1. OEMs
6.3.2. Automotive Manufacturers
6.3.3. Healthcare Providers
6.4. Analysis, Insights and Forecast - by Size
6.4.1. Below 20 inches
6.4.2. 20 to 30 inches
6.4.3. 31 to 40 inches
6.4.4. 41 to 50 inches
6.4.5. Above 50 inches
6.5. Analysis, Insights and Forecast - by Technology Variant
6.5.1. Fast IPS
6.5.2. IPS Black
6.5.3. AH-IPS
6.5.4. E-IPS
7. IPS Display Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Product Type
7.1.1. Standard IPS
7.1.2. Advanced IPS
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Consumer Electronics
7.2.2. Automotive
7.2.3. Healthcare
7.2.4. Industrial & Commercial
7.3. Analysis, Insights and Forecast - by End User
7.3.1. OEMs
7.3.2. Automotive Manufacturers
7.3.3. Healthcare Providers
7.4. Analysis, Insights and Forecast - by Size
7.4.1. Below 20 inches
7.4.2. 20 to 30 inches
7.4.3. 31 to 40 inches
7.4.4. 41 to 50 inches
7.4.5. Above 50 inches
7.5. Analysis, Insights and Forecast - by Technology Variant
7.5.1. Fast IPS
7.5.2. IPS Black
7.5.3. AH-IPS
7.5.4. E-IPS
8. IPS Display Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Product Type
8.1.1. Standard IPS
8.1.2. Advanced IPS
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Consumer Electronics
8.2.2. Automotive
8.2.3. Healthcare
8.2.4. Industrial & Commercial
8.3. Analysis, Insights and Forecast - by End User
8.3.1. OEMs
8.3.2. Automotive Manufacturers
8.3.3. Healthcare Providers
8.4. Analysis, Insights and Forecast - by Size
8.4.1. Below 20 inches
8.4.2. 20 to 30 inches
8.4.3. 31 to 40 inches
8.4.4. 41 to 50 inches
8.4.5. Above 50 inches
8.5. Analysis, Insights and Forecast - by Technology Variant
8.5.1. Fast IPS
8.5.2. IPS Black
8.5.3. AH-IPS
8.5.4. E-IPS
9. IPS Display Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Product Type
9.1.1. Standard IPS
9.1.2. Advanced IPS
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Consumer Electronics
9.2.2. Automotive
9.2.3. Healthcare
9.2.4. Industrial & Commercial
9.3. Analysis, Insights and Forecast - by End User
9.3.1. OEMs
9.3.2. Automotive Manufacturers
9.3.3. Healthcare Providers
9.4. Analysis, Insights and Forecast - by Size
9.4.1. Below 20 inches
9.4.2. 20 to 30 inches
9.4.3. 31 to 40 inches
9.4.4. 41 to 50 inches
9.4.5. Above 50 inches
9.5. Analysis, Insights and Forecast - by Technology Variant
9.5.1. Fast IPS
9.5.2. IPS Black
9.5.3. AH-IPS
9.5.4. E-IPS
10. IPS Display Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Product Type
10.1.1. Standard IPS
10.1.2. Advanced IPS
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Consumer Electronics
10.2.2. Automotive
10.2.3. Healthcare
10.2.4. Industrial & Commercial
10.3. Analysis, Insights and Forecast - by End User
10.3.1. OEMs
10.3.2. Automotive Manufacturers
10.3.3. Healthcare Providers
10.4. Analysis, Insights and Forecast - by Size
10.4.1. Below 20 inches
10.4.2. 20 to 30 inches
10.4.3. 31 to 40 inches
10.4.4. 41 to 50 inches
10.4.5. Above 50 inches
10.5. Analysis, Insights and Forecast - by Technology Variant
10.5.1. Fast IPS
10.5.2. IPS Black
10.5.3. AH-IPS
10.5.4. E-IPS
11. IPS Display Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. IPS Display Market Research Methodology
List of Figures
Figure 1: IPS Display Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia Pacific IPS Display Market Revenue (Billion), by Product Type 2026 & 2034
Figure 3: Asia Pacific IPS Display Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: Asia Pacific IPS Display Market Revenue (Billion), by Application 2026 & 2034
Figure 5: Asia Pacific IPS Display Market Revenue Share (%), by Application 2026 & 2034
Figure 6: Asia Pacific IPS Display Market Revenue (Billion), by End User 2026 & 2034
Figure 7: Asia Pacific IPS Display Market Revenue Share (%), by End User 2026 & 2034
Figure 8: Asia Pacific IPS Display Market Revenue (Billion), by Size 2026 & 2034
Figure 9: Asia Pacific IPS Display Market Revenue Share (%), by Size 2026 & 2034
Figure 10: Asia Pacific IPS Display Market Revenue (Billion), by Technology Variant 2026 & 2034
Figure 11: Asia Pacific IPS Display Market Revenue Share (%), by Technology Variant 2026 & 2034
Figure 12: Asia Pacific IPS Display Market Revenue (Billion), by Country 2026 & 2034
Figure 13: Asia Pacific IPS Display Market Revenue Share (%), by Country 2026 & 2034
Figure 14: North America IPS Display Market Revenue (Billion), by Product Type 2026 & 2034
Figure 15: North America IPS Display Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: North America IPS Display Market Revenue (Billion), by Application 2026 & 2034
North America IPS Display Market Revenue Share (%), by Application 2026 & 2034
List of Tables
Table 1: IPS Display Market Revenue Billion Forecast, by Product Type 2020 & 2034
The global IPS Display Market was valued at approximately USD 21.35 Billion in 2025, based on the most widely converging published estimates for IPS panels and finished IPS displays.
2. What is the IPS Display Market growth rate?
The market is projected to grow at a CAGR of roughly 8.81% from 2026 to 2034, reaching about USD 45.66 Billion by 2034, with automotive and advanced IPS growing fastest.
3. Which region leads the IPS Display Market?
Asia-Pacific leads with roughly 49% of global IPS display value in 2025, driven by panel fabrication and consumer-electronics manufacturing concentration in China, South Korea, Japan, and Taiwan.
4. What is the difference between standard and advanced IPS displays?
Standard IPS delivers wide viewing angles and color consistency for mainstream devices, while advanced IPS variants such as Fast IPS and IPS Black add higher refresh rates, faster response, and better contrast for gaming and professional use.
5. Who are the leading companies in the IPS Display Market?
Leading companies include BOE Technology Group, LG Display, AUO, TCL CSOT, Samsung Display, Innolux, Sharp, Japan Display, and finished-product brands such as Dell with its UltraSharp IPS Black monitors.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement over desk synthesis. We conducted in-depth interviews with stakeholders across the value chain, including raw material and glass substrate suppliers, specialized panel producers, module and touch-integration formulators, and global display distributors. On the demand side, we interviewed decision-makers at OEM device brands, automotive Tier-1 integrators, and healthcare imaging equipment providers. Interviewee designations included VP of Sourcing, Heads of Display R&D, Technical Directors for panel qualification, and Commercial Operations Leads responsible for regional allocation.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement VPs
35%
Display R&D Heads
30%
Technical Qualification Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Panel Manufacturers & Fabs
45%
Module & Touch Integrators
25%
OEM Device Brands
20%
Distributors & Traders
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, USITC DataWeb, Eurostat), corporate annual filings and investor presentations from listed panel manufacturers, patent databases covering IPS and fast-response LCD innovations, and recognized technical standards bodies including ISO and IEC display-ergonomics and safety standards. These sources anchor volume and pricing assumptions to auditable public records rather than unverified commentary.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up models. The top-down approach allocates macroeconomic electronics output and end-use segment spend to IPS share by application. The bottom-up approach models manufacturer capacity, panel pricing by size and grade, and end-use consumption per device category. Divergences between the two are reconciled through expert interview validation.


 IPS Display Market