 Europe and Latin America Alarm monitoring Market
Europe and Latin America Alarm Monitoring Market 2025
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Europe and Latin America Alarm monitoring Market

Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2021 | 8.200 B |
| 2022 | 9.100 B |
| 2023 | 10.20 B |
| 2024 | 11.30 B |
| 2025 | 12.40 B |
| 2026 | 13.90 B |
| 2027 | 15.50 B |

The Europe and Latin America alarm monitoring market covers solutions that connect intruder, fire, environmental and vehicle alarm panels to a 24/7 alarm receiving centre or cloud platform, generating a response from owners, patrols or emergency services. It spans hardware, software, connectivity and recurring monitoring services across residential, commercial and industrial sites.
This analysis covers alarm monitoring offerings (system & hardware; software, services & solutions), communication technologies (wired telecommunication networks, IP networks, cellular and others), input signals (analog, discrete, protocol), components (remote terminal units, motion detection sensors and others) and applications (building, vehicle and others) across Europe and Latin America.
This analysis does not cover standalone video surveillance hardware, cyber-network intrusion detection software, physical guarding, or fire-suppression equipment except where bundled into a monitored alarm contract.
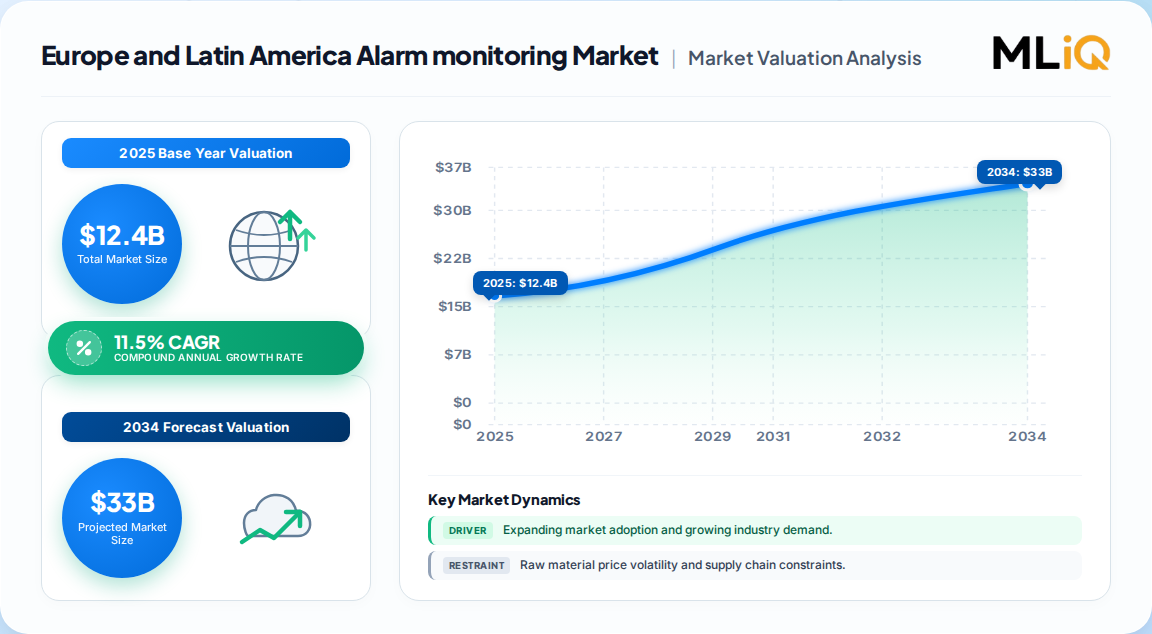
The most defensible anchor is $7.34 billion for 2020 growing to $21.66 billion by 2030 at 11.5% CAGR. Our own triangulation implies roughly $12.4 billion in 2025, but published estimates differ materially because each defines the market boundary differently.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| $7.34B → $21.66B | 2020 | 2030 | 11.5% | Europe + LatAm alarm monitoring (offering, tech, signal, component, application) | One published industry estimate |
| ~$12.4B implied | 2025 | 2030 | 11.5% | Same boundary, compounded forward | Derived from stated base and CAGR |
| 58M monitored systems (37.8M NA, 20.2M EU27+3) | 2025 | 2030 | 2.4–3.7% | Installed base of professionally monitored systems, Europe & North America only | Independent IoT analyst firm |
| $69.05B → $92.96B (global) | 2026 | 2031 | 6.13% | Global alarm monitoring, broader end-user and industrial scope | A competing analysis |
The divergence is scope, not contradiction. The 11.5% figure reflects a low starting base, rapid smart-home adoption and Latin American crime-driven demand. Our analysis suggests the true Europe and Latin America service-revenue CAGR sits closer to 9–11%, because installed-base growth (3.7% in Europe) constrains subscriber expansion while ARPU rises.
Segmentation follows five axes: offering, technology, input signal, component and application. Hardware still anchors revenue, but software and services are where the margin pool is migrating.
| Parent | Children |
|---|---|
| By Offering | System & Hardware; Software, Services & Solutions |
| By Technology | Wired Telecommunication Network; IP Network; Cellular/Others |
| By Input Signal | Analog Signal; Discrete Signal; Protocol Signal |
| By Component | Remote Terminal Unit; Motion Detection Sensor; Others |
| By Application | Building Alarm Monitoring; Vehicle Alarm Monitoring; Others |
Analog and protocol signals together held roughly 72.1% of 2020 revenue, a reminder that legacy estates still dominate installed bases even as IP migrates in at 13.9% CAGR.
Europe leads the combined market with about two-thirds of revenue, and Brazil is the largest single country at more than 14.3% share. Germany anchors European hardware demand, while Spain, France and Italy are Verisure's strongest monitored-subscription territories.
| Region | Market Share (%) |
|---|---|
| Europe | 0.66% |
| Brazil | 0.14% |
| Mexico | 0.08% |
| Argentina | 0.05% |
| Colombia | 0.04% |
| Chile & Rest of Latin America | 0.03% |
| Sub-region | Share |
|---|---|
| Europe | 66% |
| Brazil | 14% |
| Mexico | 8% |
| Argentina | 5% |
| Colombia | 4% |
| Chile & Rest of LatAm | 3% |
The primary growth engine is the shift from unmonitored hardware to recurring monitored subscriptions, amplified by insurance discounts of 5–20% and telecom bundling. False alarms, churn and IoT cyber-risk are the binding constraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Smart home & automation adoption | Driver | Strong | Pulls monitored panels into new residential builds |
| Insurance premium discounts (5–20%) | Driver | Strong | Reframes monitoring as cost offset, not discretionary spend |
| IP/cellular migration | Driver | Strong | Cuts truck rolls, enables video verification |
| Higher crime rates in Latin America | Driver | Moderate | Directly lifts residential and small-business uptake |
| DIY self-monitoring | Opportunity | Moderate | Expands funnel; upsell path to professional ARC |
| False alarm incidence | Restraint | Strong | Drives fines, attrition and police non-response |
| Residential churn | Restraint | Strong | Erodes lifetime value in saturated European markets |
| IoT cybersecurity & GDPR exposure | Restraint | Moderate | Raises compliance cost for endpoints and cloud |
The balance favours growth, but the quality of that growth is uneven. Our analysis suggests European expansion will be ARPU-led and slower in volume, whereas Latin American growth is volume-led and more price-sensitive — two different operating models under one headline CAGR.
Competition is medium-concentrated and split between subscription-led specialists (ADT, Verisure, Sector Alarm), diversified industrial conglomerates (Honeywell, Siemens, ABB, Schneider, Bosch, Johnson Controls) and DIY/tech challengers (Vivint, Ring, SimpliSafe).
| Company | Primary strength | Monitoring model | Regional bias |
|---|---|---|---|
| ADT | Brand, US scale | Professional ARC | North America-focused |
| Verisure | 6.17M subscribers, 13 EU + 5 LatAm markets | Professional, direct sales | Spain, France, Italy, Nordics, Brazil |
| Honeywell | Building & industrial integration | Hybrid | Global/Europe |
| Siemens / ABB / Schneider | Automation and BMS bundling | System-integrated | Europe |
| Bosch | Sensor and panel portfolio | Hybrid | Europe, LatAm |
| Johnson Controls | Commercial and lone-worker safety | Professional | Global |
| Vivint | Smart-home bundles | Professional | North America |
The durable moat is not the panel — it is the ARC network, installer density and insurer certification. Verisure's direct-sales footprint across Spain, France, Italy and five South American countries is the clearest example of a defensible regional position.
Procurement should treat monitoring as a multi-year service contract, not an equipment purchase. The decisive criteria are ARC certification (UL 827, TMA Five Diamond equivalents), dual-path signalling redundancy, video verification capability and GDPR-compliant data handling.
Switching costs are embedded in installation, panel lock-in and contract terms rather than in the monthly fee. Buyers should insist on open protocol support and documented cellular failover, because a phone-line-only system can be defeated by cutting the line. In Latin America, patrol response SLAs matter more than analytics; in Europe, cyber-resilience and carbon-monoxide mandate compliance (EU 2026) are becoming table stakes. Underwrite churn explicitly — residential attrition is the single largest value destroyer in this category.
The balance of evidence favours a disciplined service-revenue strategy over hardware-led expansion. The 11.5% headline CAGR is credible at the portfolio level, but it conceals a 3.7% installed-base growth in Europe against far faster, lower-ARPU subscriber growth in Latin America. Operators that apply one go-to-market model to both regions will misprice risk.
The strongest counter-argument is that DIY and self-monitoring could cap professional monitoring penetration in Europe, compressing the very subscription economics we expect to drive margin. That risk is real but partial: DIY behaves as a funnel, with professional monitoring commonly offered as a paid upgrade, and insurers increasingly reward verified, professionally monitored systems.
Actionable strategy:
Evidence that would change this conclusion: sustained residential churn above 15% annually, or EU regulation restricting video analytics in residential settings, would materially reduce the service-revenue ceiling.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.5% from 2020-2034 |
| Segmentation |
|
The market was valued at $7.34 billion in 2020 and is projected to reach $21.66 billion by 2030 at an 11.5% CAGR. Our triangulation implies roughly $12.4 billion in 2025, split about two-thirds Europe and one-third Latin America.
Europe leads regionally with about two-thirds of combined revenue. At country level, Brazil is the largest single market, accounting for more than 14.3% of total revenue in 2020, supported by strong alarm-subscription demand.
IP-network signalling is the fastest-growing technology segment at 13.9% CAGR, while vehicle alarm monitoring is the fastest-growing application. System and hardware remains the largest offering segment at roughly 10.3% CAGR.
False alarm incidence, residential subscription churn, IoT cybersecurity vulnerabilities and GDPR compliance costs are the principal restraints. Skilled-installer shortages in rural Europe and low retrofit budgets in multi-family dwellings also slow adoption.
Key players include ADT, Verisure, Honeywell, Siemens, ABB, Schneider Electric, Bosch, Johnson Controls and Vivint. Verisure leads by subscriber count in Europe and South America, while ADT anchors North American professional monitoring.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the alarm monitoring value chain with security-system equipment and panel manufacturers, alarm receiving centre (ARC) operators, communication-module and sensor suppliers, security distributors and integrators, and insurance and telecom channel partners. Interviews targeted decision-makers including Heads of Security Operations, VP-level Product and Portfolio Leads, Commercial and Channel Directors, and Regulatory & Compliance Managers, capturing installation economics, churn behaviour and certification requirements.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Security Operations & Monitoring Heads | 35% |
| Product & Portfolio Directors | 30% |
| Commercial & Channel Leads | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Alarm Panel & Equipment Manufacturers | 40% |
| ARC Operators & Security Service Providers | 30% |
| Distributors & Systems Integrators | 20% |
| Insurer & Telecom Channel Partners | 10% |
We validated findings against Eurostat and UN Comtrade trade flows for alarm and signalling equipment, corporate annual filings and investor presentations from listed security and automation companies, patent databases covering video analytics and ambient sensing, and technical standards frameworks including UL 827, TMA Five Diamond and EN 50131. European regulatory sources, including GDPR guidance and the EU cyber-resilience framework, informed our compliance assessment.
We ran simultaneous top-down and bottom-up models. Top-down, we allocated macroeconomic security spending across residential, commercial and vehicle applications by country. Bottom-up, we modelled monitored-subscriber bases, installation volumes, panel and module pricing, and recurring monitoring fees to reconstruct revenue. The two models were reconciled at country level before aggregation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up subscriber and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, subscriber mapping & commercial filings | High |