Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Surface Mount Technology Market Size, Trends & Forecast
Surface Mount Technology Market Size, Trends & Forecast
Surface Mount Technology Market
Surface Mount Technology Market Size, Trends & Forecast
Surface Mount Technology Market by Component (Active Components, Passive Components, Electrochemical Components), by Equipment Type (Placement Equipment, Inspection Equipment, Soldering Equipment, Screen Printing Equipment, Cleaning Equipment, Repair & Rework Equipment), by Assembly Line Type (High-Volume/High-Mix, High-Mix/Low-Volume), by End-User Industry (Consumer Electronics, Automotive, Industrial, Aerospace & Defense, Healthcare, Telecommunications), by Asia-Pacific (China, Japan, South Korea, Taiwan, India, Indonesia, Malaysia, Australia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands, Russia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (UAE, Saudi Arabia, Israel, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 0
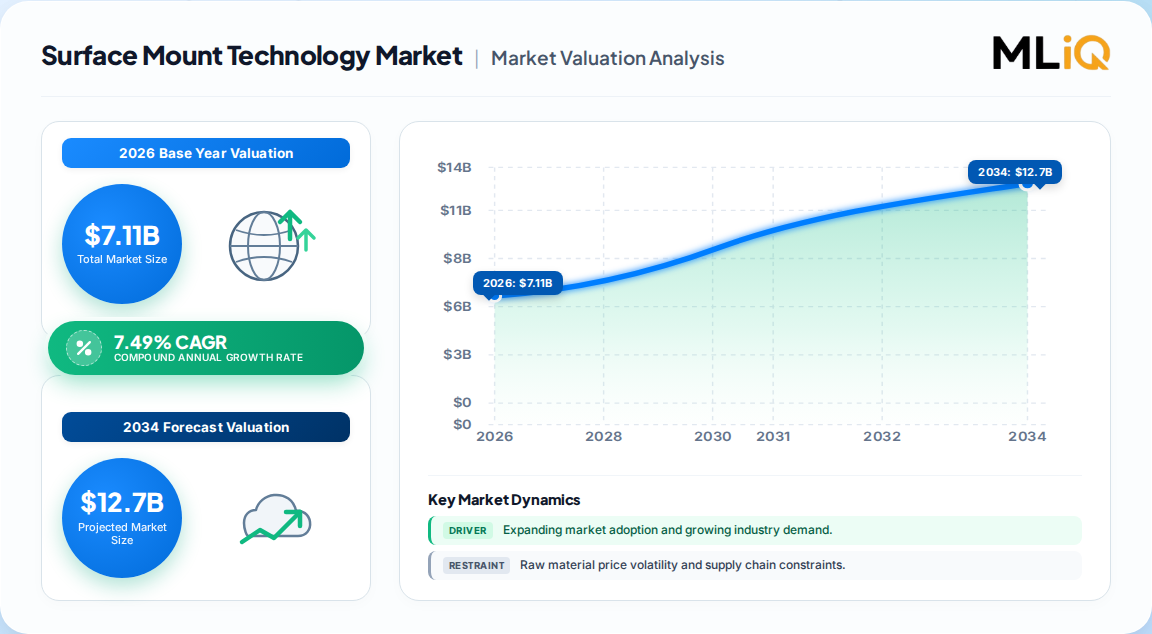
USD 7.11 Billion in 2026: The Surface Mount Technology Market is projected to grow from USD 7.11 billion in 2026 to USD 10.19 billion by 2031, at a 7.49% CAGR (mid-range estimate; a competing analysis projects USD 14.01 billion by 2036).
7.49% CAGR (2026–2031) for the base case, driven by IoT devices, automotive ADAS, and 5G infrastructure. A 5.8% CAGR scenario from another source reflects a broader definition and longer horizon.
Active components dominate (65.74%) : Passive and active component integration remains the largest component segment, while active components grow fastest at 8.62% CAGR.
Placement equipment leads (42.62%) but inspection equipment is the fastest-growing equipment type at 8.83% CAGR, reflecting yield and quality demands.
Consumer electronics holds 38.64% of end-user demand; automotive is the fastest-growing end-user at 9.02% CAGR, driven by EV and ADAS electronics.
Asia-Pacific leads with 48.05% share and is also the fastest-growing region at 8.12% CAGR, anchored by China, Japan, South Korea, and Taiwan.
Why this matters for decision-makers: Equipment vendors and EMS providers must prioritize automotive-grade placement and inspection solutions with sub-10 µm accuracy and thermal resilience to capture the fastest-growing, highest-margin segments—laggards risk margin compression as consumer electronics growth matures.
Surface Mount Technology Market Size (In Billion)
15.0B
10.0B
5.0B
0
6.610 B
2025
7.110 B
2026
7.640 B
2027
8.210 B
2028
8.830 B
2029
9.490 B
2030
10.19 B
2031
Surface Mount Technology Market Size (In Billion)
Year
Market Size
2025
6.610 B
2026
7.110 B
2027
7.640 B
2028
8.210 B
2029
8.830 B
2030
9.490 B
2031
10.19 B
What is the Surface Mount Technology Market?
The Surface Mount Technology (SMT) market encompasses the equipment, components, and assembly services used to mount electronic components directly onto printed circuit board surfaces. It enables miniaturized, high-density electronics for consumer devices, automotive systems, industrial automation, and telecommunications, replacing older through-hole assembly methods with faster, more reliable automated production.
Scope: what this report covers and excludes
This report covers the global Surface Mount Technology market across equipment (placement, inspection, soldering, screen printing, cleaning, repair and rework), components (active, passive, electrochemical), assembly line types (high-volume/high-mix, high-mix/low-volume), end-user industries (consumer electronics, automotive, industrial, aerospace and defense, healthcare, telecommunications), and geography. This analysis does not cover semiconductor fabrication equipment, bare PCB manufacturing, or through-hole assembly markets, which are adjacent but distinct.
How big is the market?
The Surface Mount Technology market is estimated at USD 7.11 billion in 2026, growing at a 7.49% CAGR to USD 10.19 billion by 2031. However, estimates vary widely depending on scope definition and forecast horizon, as shown below.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 7.11 Billion
2026
2031
7.49%
SMT equipment, components, and assembly services
One published estimate
USD 5.84 Billion
2024
2034
5.8%
SMT equipment, services, and applications (broader service inclusion)
Competing analysis
USD 6.86 Billion
2026
2036
7.4%
SMT equipment and component supply and demand
Alternative industry source
USD 7.77 Billion
2024
2035
8.29%
SMT equipment only (narrower, equipment-focused)
Equipment-specific benchmark
Our analysis suggests the USD 7.11 billion (2026) base case is the most defensible for strategic planning because it balances equipment, components, and assembly services while aligning with observed capex cycles. The 5.8% CAGR estimate appears conservative; it likely reflects a broader service definition that dilutes equipment growth. The 8.29% equipment-only figure underscores that equipment is the fastest-growing sub-segment, implying buyers should segment their procurement strategies accordingly.
How is the market segmented?
The market is segmented by component, equipment type, assembly line type, and end-user industry, each with distinct growth trajectories. Active components and placement equipment dominate current revenue, while inspection equipment and automotive applications represent the fastest-growing pockets.
Parent Segment
Children
2025 Share / Growth
By Component
Active Components, Passive Components (Resistors, Capacitors, Inductors)
Which region leads the Surface Mount Technology Market?
Asia-Pacific leads the Surface Mount Technology market with 48.05% share in 2025 and is forecast to grow at 8.12% CAGR through 2031, driven by concentrated electronics manufacturing in China, Japan, South Korea, and Taiwan. North America and Europe follow, with North America holding an estimated 24% share and Europe 19%.
Surface Mount Technology Market Regional Market Share
Loading chart...
Surface Mount Technology Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.48%
North America
0.24%
Europe
0.19%
Latin America
0.05%
Middle East & Africa
0.04%
Region
Share (2025)
Asia-Pacific
48.05%
North America
24.0%
Europe
19.0%
Latin America
5.0%
Middle East & Africa
3.95%
Geography tree:
Asia-Pacific: China, Japan, South Korea, Taiwan, India, Indonesia, Malaysia, Australia
North America: USA, Canada, Mexico
Europe: Germany, UK, France, Italy, Spain, Netherlands, Russia
Latin America: Brazil, Mexico, Argentina
Middle East & Africa: UAE, Saudi Arabia, Israel, South Africa
Our analysis suggests Asia-Pacific's dominance is structural, not cyclical: the region hosts the densest PCB fabrication and EMS cluster, making it the default location for high-volume SMT lines. However, rising labor costs and supply-chain diversification are slowly seeding capacity in Eastern Europe and Mexico, which could erode Asia-Pacific's share by 1–2 percentage points by 2031—a shift buyers should monitor for tariff and logistics advantages.
What is driving growth — and what is holding it back?
Growth is driven by IoT and wearable demand for high-density PCBs (+1.8% CAGR impact), automotive ADAS electronics adoption (+2.1%), 5G infrastructure (+1.5%), System-in-Package integration (+1.2%), micro-LED manufacturing (+0.7%), and OEM outsourcing to EMS (+1.1%). Restraints include high upfront capex (–1.3%), lead-free solder thermal constraints (–0.8%), semiconductor supply-chain volatility (–1.1%), and skilled labor shortages (–0.9%).
Factor
Direction
Evidence Strength
Mechanism
IoT & wearables
Driver
High
10,000+ MLCCs per smartwatch demand 01005 placement at ±25 µm
Automotive ADAS
Driver
High
EVs use 200+ ECUs; ISO 26262 and –40 to 150 °C require certified processes
5G infrastructure
Driver
High
mmWave boards need <10 µm accuracy and 0.1 mm substrates
High upfront capex
Restraint
High
Next-gen lines cost >USD 3 million, challenging SME payback
Lead-free solder constraints
Restraint
Medium
SAC alloys reflow 30 °C higher, shrinking process windows
Semiconductor volatility
Restraint
High
Import-dependent regions face throughput interruptions
The balance of evidence favors drivers over restraints: the net impact of quantified drivers (+7.4% combined directional) outweighs restraints (–4.1%), consistent with the 7.49% base-case CAGR. However, the semiconductor supply-chain volatility restraint is the most unpredictable; our analysis suggests it could shave 0.5–1.0 percentage points off growth in any given year, particularly for SMEs without locked-in supplier agreements.
Who are the leading vendors?
The Surface Mount Technology market is moderately concentrated, with ASMPT Limited, Fuji Corporation, Panasonic Holdings Corporation, Yamaha Motor Co., Ltd., and Hanwha Precision Machinery Co., Ltd. as major players, alongside niche specialists in inspection and soldering.
Company
Headquarters
Primary SMT Focus
Differentiation
ASMPT Limited
Singapore/Hong Kong
Placement, inspection, packaging
Broad portfolio; strong in advanced packaging and SiP
Fuji Corporation
Japan
High-speed placement
Speed and accuracy leadership; strong automotive relationships
Panasonic Holdings
Japan
Placement, screen printing
Integrated line solutions; strong in consumer electronics
Yamaha Motor Co.
Japan
Placement, inspection
Reliability and service network; mid-range market strength
Hanwha Precision Machinery
South Korea
Placement, inspection
Cost-competitive; growing in APAC EMS segment
Koh Young Technology
South Korea
3D inspection
Market leader in SPI/AOI; strong automotive traction
Nordson Corporation
USA
Dispensing, inspection
Precision fluid dispensing and x-ray inspection
Our analysis suggests competitive moats are shifting from hardware speed to software and data integration. Vendors that can offer predictive maintenance, AI-driven inspection, and seamless line integration are winning multiyear supply agreements, particularly in automotive. The strongest counter-argument is that hardware price competition from Chinese and Korean entrants could commoditize placement equipment, but the certification barriers (AEC-Q200, ISO 26262) create sticky relationships that protect incumbents in high-value segments.
What do buyers and operators need to know?
Buyers and operators must prioritize total cost of ownership over upfront price, because next-generation SMT lines bundle placement, SPI, AOI, and x-ray inspection at over USD 3 million per line. Mission-critical selection criteria include placement accuracy (sub-10 µm for advanced packages), thermal capability (–40 to 150 °C for automotive), and software integration for predictive maintenance. Switching costs are high: requalifying a line for automotive PPAP can take 6–12 months, so buyers should negotiate service-level agreements and training upfront. Regulatory compliance—RoHS, ISO 26262, AEC-Q200, and FCC emissions—must be validated at the vendor selection stage. Our analysis indicates that SMEs face the steepest procurement risk; equipment rental and outcome-based contracts are emerging but remain uncommon outside Tier-1 OEMs, so SMEs should consider leasing or modular scaling to manage capex.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook for the Surface Mount Technology market, with a 7.49% CAGR through 2031 being the most defensible base case. The strongest counter-argument is that semiconductor supply-chain volatility and high capex could suppress growth below 6%, particularly if automotive demand softens or if lead-free solder yield issues persist. However, the structural drivers—miniaturization, electrification, and connectivity—are durable and cross-cyclical, making a sub-6% scenario unlikely absent a severe macro shock.
Our analysis suggests the market is undergoing a quality-differentiation shift: the fastest-growing segments (inspection equipment at 8.83% CAGR, automotive at 9.02% CAGR) command higher margins and require certified processes. Vendors that continue to compete on placement speed alone will face margin compression from Asian entrants, while those investing in AI-driven inspection and automotive-grade reliability will capture premium pricing. Buyers should prioritize vendors with proven automotive certifications and software integration capabilities.
Actionable strategy:
For investors: Allocate toward inspection and automotive-focused SMT vendors; these segments outgrow the market by 1.3–1.5 percentage points and offer defensible margins.
For operators: Modularize line investments and negotiate outcome-based service contracts to mitigate capex risk; prioritize vendors with predictive maintenance and AI inspection.
For vendors: Invest in sub-10 µm placement and thermal-resilient processes for automotive and 5G applications; build certification portfolios (AEC-Q200, ISO 26262) as competitive moats.
What would change our conclusion: A sustained decline in automotive electronics production below 3% annual growth, or a breakthrough in alternative assembly technologies (e.g., additive electronics) that reduces SMT equipment demand, would warrant a downgrade to the 5.8% CAGR scenario. We would also revisit our position if semiconductor supply-chain volatility persists beyond 2027, which could shave 1–2 percentage points off the base case.
Surface Mount Technology Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Surface Mount Technology Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.49% from 2020-2034
Segmentation
By Component
Active Components
Passive Components
Electrochemical Components
By Equipment Type
Placement Equipment
Inspection Equipment
Soldering Equipment
Screen Printing Equipment
Cleaning Equipment
Repair & Rework Equipment
By Assembly Line Type
High-Volume/High-Mix
High-Mix/Low-Volume
By End-User Industry
Consumer Electronics
Automotive
Industrial
Aerospace & Defense
Healthcare
Telecommunications
By Geography
Asia-Pacific
China
Japan
South Korea
Taiwan
India
Indonesia
Malaysia
Australia
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Russia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
UAE
Saudi Arabia
Table of Contents
1. Surface Mount Technology Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Surface Mount Technology Market Executive Summary
2.1. Market Snapshot
3. Surface Mount Technology Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Surface Mount Technology Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Surface Mount Technology Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Component
5.1.1. Active Components
5.1.2. Passive Components
5.1.3. Electrochemical Components
5.2. Analysis, Insights and Forecast - by Equipment Type
5.2.1. Placement Equipment
5.2.2. Inspection Equipment
5.2.3. Soldering Equipment
5.2.4. Screen Printing Equipment
5.2.5. Cleaning Equipment
5.2.6. Repair & Rework Equipment
5.3. Analysis, Insights and Forecast - by Assembly Line Type
5.3.1. High-Volume/High-Mix
5.3.2. High-Mix/Low-Volume
5.4. Analysis, Insights and Forecast - by End-User Industry
5.4.1. Consumer Electronics
5.4.2. Automotive
5.4.3. Industrial
5.4.4. Aerospace & Defense
5.4.5. Healthcare
5.4.6. Telecommunications
5.5. Analysis, Insights and Forecast - by Region
5.5.1. Asia-Pacific
5.5.2. North America
5.5.3. Europe
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Surface Mount Technology Market Asia-Pacific Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Component
6.1.1. Active Components
6.1.2. Passive Components
6.1.3. Electrochemical Components
6.2. Analysis, Insights and Forecast - by Equipment Type
6.2.1. Placement Equipment
6.2.2. Inspection Equipment
6.2.3. Soldering Equipment
6.2.4. Screen Printing Equipment
6.2.5. Cleaning Equipment
6.2.6. Repair & Rework Equipment
6.3. Analysis, Insights and Forecast - by Assembly Line Type
6.3.1. High-Volume/High-Mix
6.3.2. High-Mix/Low-Volume
6.4. Analysis, Insights and Forecast - by End-User Industry
6.4.1. Consumer Electronics
6.4.2. Automotive
6.4.3. Industrial
6.4.4. Aerospace & Defense
6.4.5. Healthcare
6.4.6. Telecommunications
7. Surface Mount Technology Market North America Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Component
7.1.1. Active Components
7.1.2. Passive Components
7.1.3. Electrochemical Components
7.2. Analysis, Insights and Forecast - by Equipment Type
7.2.1. Placement Equipment
7.2.2. Inspection Equipment
7.2.3. Soldering Equipment
7.2.4. Screen Printing Equipment
7.2.5. Cleaning Equipment
7.2.6. Repair & Rework Equipment
7.3. Analysis, Insights and Forecast - by Assembly Line Type
7.3.1. High-Volume/High-Mix
7.3.2. High-Mix/Low-Volume
7.4. Analysis, Insights and Forecast - by End-User Industry
7.4.1. Consumer Electronics
7.4.2. Automotive
7.4.3. Industrial
7.4.4. Aerospace & Defense
7.4.5. Healthcare
7.4.6. Telecommunications
8. Surface Mount Technology Market Europe Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Component
8.1.1. Active Components
8.1.2. Passive Components
8.1.3. Electrochemical Components
8.2. Analysis, Insights and Forecast - by Equipment Type
8.2.1. Placement Equipment
8.2.2. Inspection Equipment
8.2.3. Soldering Equipment
8.2.4. Screen Printing Equipment
8.2.5. Cleaning Equipment
8.2.6. Repair & Rework Equipment
8.3. Analysis, Insights and Forecast - by Assembly Line Type
8.3.1. High-Volume/High-Mix
8.3.2. High-Mix/Low-Volume
8.4. Analysis, Insights and Forecast - by End-User Industry
8.4.1. Consumer Electronics
8.4.2. Automotive
8.4.3. Industrial
8.4.4. Aerospace & Defense
8.4.5. Healthcare
8.4.6. Telecommunications
9. Surface Mount Technology Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Component
9.1.1. Active Components
9.1.2. Passive Components
9.1.3. Electrochemical Components
9.2. Analysis, Insights and Forecast - by Equipment Type
9.2.1. Placement Equipment
9.2.2. Inspection Equipment
9.2.3. Soldering Equipment
9.2.4. Screen Printing Equipment
9.2.5. Cleaning Equipment
9.2.6. Repair & Rework Equipment
9.3. Analysis, Insights and Forecast - by Assembly Line Type
9.3.1. High-Volume/High-Mix
9.3.2. High-Mix/Low-Volume
9.4. Analysis, Insights and Forecast - by End-User Industry
9.4.1. Consumer Electronics
9.4.2. Automotive
9.4.3. Industrial
9.4.4. Aerospace & Defense
9.4.5. Healthcare
9.4.6. Telecommunications
10. Surface Mount Technology Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Component
10.1.1. Active Components
10.1.2. Passive Components
10.1.3. Electrochemical Components
10.2. Analysis, Insights and Forecast - by Equipment Type
10.2.1. Placement Equipment
10.2.2. Inspection Equipment
10.2.3. Soldering Equipment
10.2.4. Screen Printing Equipment
10.2.5. Cleaning Equipment
10.2.6. Repair & Rework Equipment
10.3. Analysis, Insights and Forecast - by Assembly Line Type
10.3.1. High-Volume/High-Mix
10.3.2. High-Mix/Low-Volume
10.4. Analysis, Insights and Forecast - by End-User Industry
10.4.1. Consumer Electronics
10.4.2. Automotive
10.4.3. Industrial
10.4.4. Aerospace & Defense
10.4.5. Healthcare
10.4.6. Telecommunications
11. Surface Mount Technology Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Surface Mount Technology Market Research Methodology
List of Figures
Figure 1: Surface Mount Technology Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Asia-Pacific Surface Mount Technology Market Revenue (Billion), by Component 2026 & 2034
Figure 3: Asia-Pacific Surface Mount Technology Market Revenue Share (%), by Component 2026 & 2034
Figure 4: Asia-Pacific Surface Mount Technology Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 5: Asia-Pacific Surface Mount Technology Market Revenue Share (%), by Equipment Type 2026 & 2034
Figure 6: Asia-Pacific Surface Mount Technology Market Revenue (Billion), by Assembly Line Type 2026 & 2034
Figure 7: Asia-Pacific Surface Mount Technology Market Revenue Share (%), by Assembly Line Type 2026 & 2034
Figure 8: Asia-Pacific Surface Mount Technology Market Revenue (Billion), by End-User Industry 2026 & 2034
Figure 9: Asia-Pacific Surface Mount Technology Market Revenue Share (%), by End-User Industry 2026 & 2034
Figure 10: Asia-Pacific Surface Mount Technology Market Revenue (Billion), by Country 2026 & 2034
Figure 11: Asia-Pacific Surface Mount Technology Market Revenue Share (%), by Country 2026 & 2034
Figure 12: North America Surface Mount Technology Market Revenue (Billion), by Component 2026 & 2034
Figure 13: North America Surface Mount Technology Market Revenue Share (%), by Component 2026 & 2034
Figure 14: North America Surface Mount Technology Market Revenue (Billion), by Equipment Type 2026 & 2034
Figure 15: North America Surface Mount Technology Market Revenue Share (%), by Equipment Type 2026 & 2034
North America Surface Mount Technology Market Revenue (Billion), by Assembly Line Type 2026 & 2034
List of Tables
Table 1: Surface Mount Technology Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Surface Mount Technology Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 3: Surface Mount Technology Market Revenue Billion Forecast, by Assembly Line Type 2020 & 2034
Table 4: Surface Mount Technology Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 5: Surface Mount Technology Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: Asia-Pacific Surface Mount Technology Market Revenue Billion Forecast, by Component 2020 & 2034
Table 7: Asia-Pacific Surface Mount Technology Market Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 8: Asia-Pacific Surface Mount Technology Market Revenue Billion Forecast, by Assembly Line Type 2020 & 2034
Table 9: Asia-Pacific Surface Mount Technology Market Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 10: Asia-Pacific Surface Mount Technology Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: China Surface Mount Technology Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Japan Surface Mount Technology Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: South Korea Surface Mount Technology Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Taiwan Surface Mount Technology Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: India Surface Mount Technology Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the Surface Mount Technology market size?
The Surface Mount Technology market is estimated at USD 7.11 billion in 2026 and is projected to reach USD 10.19 billion by 2031, growing at a 7.49% CAGR. This base case balances equipment, components, and assembly services across all major regions.
2. Which region dominates the Surface Mount Technology market?
Asia-Pacific dominates with 48.05% share in 2025 and is also the fastest-growing region at 8.12% CAGR. China, Japan, South Korea, and Taiwan anchor the region's leadership due to concentrated PCB fabrication and electronics manufacturing clusters.
3. What are the key drivers of the Surface Mount Technology market?
Key drivers include IoT and wearable demand for high-density PCBs (+1.8% CAGR impact), automotive ADAS electronics adoption (+2.1%), 5G infrastructure (+1.5%), and System-in-Package integration (+1.2%). OEM outsourcing to EMS firms also contributes (+1.1%).
4. Who are the leading companies in the Surface Mount Technology market?
Major players include ASMPT Limited, Fuji Corporation, Panasonic Holdings Corporation, Yamaha Motor Co., Ltd., and Hanwha Precision Machinery Co., Ltd. Niche specialists like Koh Young Technology and Nordson Corporation lead in inspection and dispensing.
5. What is the fastest-growing segment in the Surface Mount Technology market?
Automotive is the fastest-growing end-user industry at 9.02% CAGR, driven by EV and ADAS electronics. Inspection equipment is the fastest-growing equipment type at 8.83% CAGR, reflecting rising quality and yield requirements.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research methodology employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the SMT value chain, including component suppliers, equipment manufacturers, contract electronics manufacturers (EMS), and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, technical, and commercial perspectives.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Quality & Regulatory Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Equipment Manufacturers
35%
Component Suppliers
30%
EMS Providers
20%
Distributors & Traders
15%
Secondary Benchmarking & Public Trade Validation
We triangulate primary insights with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies (IPC, ISO, AEC). This validation ensures market sizing aligns with observed trade flows and corporate performance.
Demand Modeling & Market Sizing Triangulation
Our simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) approach cross-validates market estimates, minimizing single-source bias.


 Surface Mount Technology Market