Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Time-Sensitive Networking Market by Component (Ethernet Switches, Network Interface Cards, Processors, Gateways, Memory, Software & Services), by Application (Factory Automation & Control, Automotive In-Vehicle Networking, Utilities, Defence & Aerospace, Broadcast & Media, Others), by End-User Industry (Discrete Manufacturing, Process Industries, Automotive OEMs, Utilities, Defence, Transportation), by Network Topology (Wired Deterministic Ethernet, Hybrid Wired-Wireless TSN), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 0
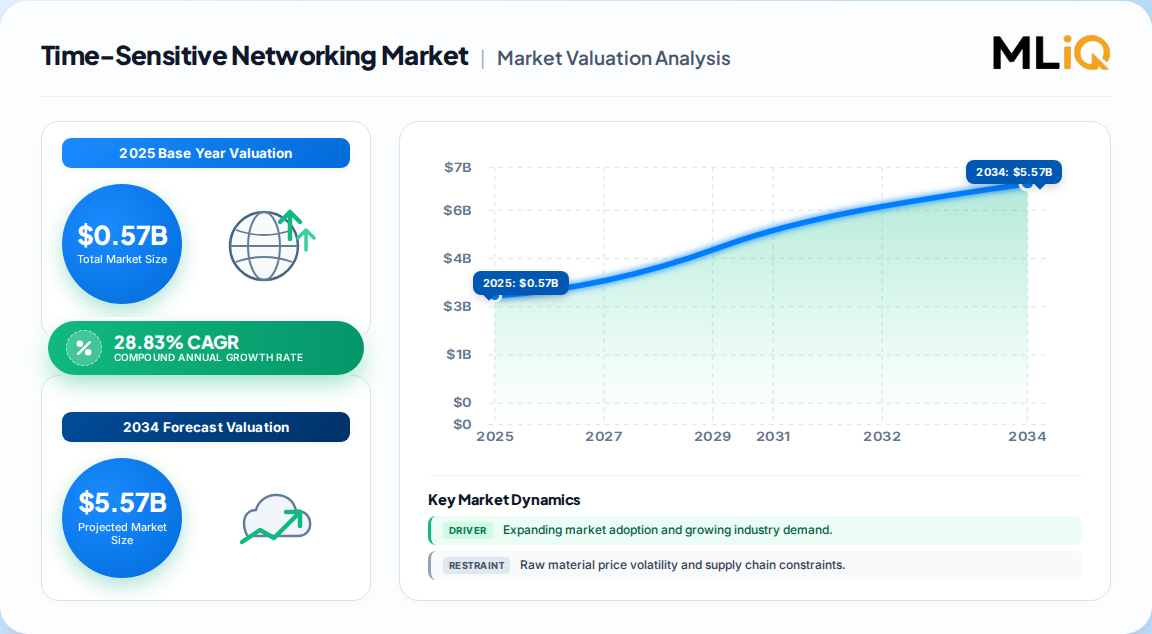
USD 0.57 billion in 2025, the global Time-Sensitive Networking market is scaling toward USD 2.02 billion by 2030 at a 28.83% CAGR (base year 2025, global scope).
The forecast trajectory implies roughly a 3.5x expansion in five years, materially faster than mainstream industrial Ethernet hardware growth.
Ethernet switches led component revenue at 37.62% in 2024; software-defined traffic management is the fastest-expanding layer at a 28.97% CAGR.
Factory automation accounted for 39.81% of 2024 revenue; automotive in-vehicle networking is the fastest application at 29.12% CAGR.
Asia-Pacific commanded 33.97% of 2024 revenue and is both the largest and fastest-growing region, with North America second on convergence maturity.
Leading vendors include Belden, Cisco, Moxa, TTTech, Analog Devices, NXP, Siemens, Intel and Microchip; the top five collectively hold roughly half of revenue.
Why this matters for decision-makers: vendors that lag on IEC/IEEE 60802-conformant switches and software orchestration will cede the brownfield retrofit pool to incumbents — the strategic risk is not demand, it is qualification timing.
Time-Sensitive Networking Market Size (In Million)
2.5B
2.0B
1.5B
1.0B
500.0M
0
570.0 M
2025
730.0 M
2026
940.0 M
2027
1.210 B
2028
1.560 B
2029
2.020 B
2030
Time-Sensitive Networking Market Size (In Million)
Year
Market Size
2025
570.0 M
2026
730.0 M
2027
940.0 M
2028
1.210 B
2029
1.560 B
2030
2.020 B
What is the Time-Sensitive Networking Market?
The Time-Sensitive Networking market covers IEEE 802.1 standards-based Ethernet equipment and software that guarantee deterministic latency, jitter and time synchronization for converged OT/IT traffic. It spans switches, network interface cards, processors, gateways, controllers and orchestration software deployed across factory automation, automotive, utilities, defence and broadcast networks.
Scope: what this report covers and excludes
This analysis covers global TSN hardware (switches, NICs, controllers, memory, gateways) and software across wired deterministic Ethernet and hybrid wired-wireless topologies, segmented by component, application, end-user industry and network topology, with value forecasts to 2030. This analysis does not cover conventional best-effort industrial Ethernet, legacy fieldbus (PROFIBUS, CAN, Modbus), standalone private 5G RAN equipment, or general-purpose enterprise switching outside deterministic profiles.
How big is the market for Time-Sensitive Networking Market?
Estimates diverge sharply because publishers define TSN differently — some count only deterministic Ethernet silicon and switches, others include orchestration software and integration services. The table below reconciles the leading published views.
Broad TSN software/services including enterprise IT
One published estimate (Market.us)
USD 0.44B → USD 0.70B
2025
2033
6.1%
Narrow TSN component/switch definitions
One published estimate (Grand View Research)
Our analysis suggests the USD 0.57B → USD 2.02B (28.83% CAGR) path is the most defensible mid-case. It aligns with observed vendor revenue growth of roughly 29.1% CAGR (2022–2025) in primary filings and with the brownfield retrofit reality of an installed base exceeding 78 million PROFINET nodes. The 45.8% figure likely conflates TSN with broader software-defined networking; the 6.1% figure appears to capture only a narrow slice of switch silicon and understates mandated 60802-driven replacement. Buyers should treat the mid-case as planning baseline and stress-test against the high case for capacity commitments.
How is the market segmented?
Segmentation is best read by component and application first, because value capture is migrating from transport hardware toward software orchestration and endpoint integration.
Which region leads in Time-Sensitive Networking Market?
Asia-Pacific leads with 33.97% of 2024 revenue and the fastest growth at a 28.91% CAGR, driven by large-scale Industry 4.0 programs and Asian EV zonal architectures; North America follows on convergence maturity, with Europe close behind on standards compliance.
Asia-Pacific — China, Japan, India, South Korea, Rest of APAC
North America — USA, Canada, Mexico
Europe — Germany, UK, France, Italy, Rest of Europe
Latin America — Brazil, Argentina, Rest of LATAM
Middle East & Africa — Saudi Arabia, UAE, South Africa, Rest of MEA
Region
2024/2025 Share
Trajectory
Asia-Pacific
33.97%
Fastest growing, 28.91% CAGR
North America
~35.4% (alternate estimate)
Largest on some definitions; strong convergence demand
Europe
~28%
Standards-led, 60802 compliance driven
Latin America
~1.2%
Early-stage pilots
Middle East & Africa
~1.3%
Nascent, utilities-led
The definitional tension — APAC leading on Mordor's 2024 share versus North America leading on another publisher's 35.4% — matters for buyers. Our analysis suggests APAC will hold the volume lead through 2030 on greenfield factory and EV platform volume, while North America retains the highest revenue per node given defence and process-industry mix. Vendors should not allocate channel investment on a single regional share number.
What is driving growth — and what is holding it back?
Mandated IEC/IEEE 60802 compliance and IT/OT convergence are the strongest short-to-medium-term drivers, while OT cybersecurity exposure and legacy fieldbus migration complexity are the principal brakes on velocity.
Factor
Direction
Evidence strength
Mechanism
IT/OT convergence
Driver
High (+7.2% CAGR impact)
Single Ethernet fabric cuts cabling and maintenance; 40% infrastructure saving documented
IEC/IEEE 60802 mandate
Driver
High (+6.8%)
Compels TSN ports in PLCs, drives, sensors; 1 µs sync and bounded latency
Automotive zonal E/E architectures
Driver
High (+5.9%)
60% wiring reduction; 2.5 Gbps TSN switches in zone controllers
Private 5G / Wi-Fi 7 backhaul latency guarantees
Driver
Medium (+4.7%)
Extends microsecond timing from radio units to control servers
OT cybersecurity exposure
Restraint
High
USD 5.56M average industrial breach cost; IEC 62443 extends timelines
Our analysis suggests the balance favors accelerants through 2027, but the binding constraint is not demand — it is qualified integration capacity. The 60802 ratification converts TSN from differentiator to prerequisite, which compresses hardware pricing faster than software and services pricing. The second-order effect: hardware vendors must attach orchestration software or accept margin erosion, while services-led players gain near-term runway in Europe.
Who are the leading vendors?
The market is medium-concentration: NXP leads with over 15.10% share in 2025, and the top five players together hold 52.55%, with Ethernet incumbents, semiconductor leaders and software specialists consolidating portfolios.
Company
Primary TSN Position
Differentiation
NXP Semiconductors
Embedded TSN switches/processors (i.MX 94)
Automotive SoC integration; market leader 15.1%
Cisco Systems
Industrial Ethernet switching and software
Enterprise/OT convergence and orchestration scale
Belden
Industrial switches and network infrastructure
Brownfield retrofit channel depth
Moxa
Industrial TSN switches
Documented 40% infrastructure cost reduction
TTTech
Deterministic networking IP and platforms
Aerospace/automotive safety-critical pedigree
Analog Devices
TSN switch ICs (ADIN6310/3310)
CC-Link IE TSN Class A/B certification
Siemens
PROFINET/TSN automation stacks
Installed-base lock-in and 60802 stack integration
Intel / Microchip
Silicon and reference platforms
Breadth of endpoint design wins
Competitive moats are shifting from silicon to certification and conformance ecosystems. Analog Devices' CC-Link IE TSN certification illustrates how conformance credentials shorten procurement cycles. Our analysis suggests incumbents with installed automation bases — Siemens, Cisco, Belden — will defend share through switching costs, while NXP and TTTech defend through design-win lock-in at the platform level.
What do buyers and operators need to know?
Buyers should treat TSN procurement as a three-gate decision: conformance, security and integration. First, demand proof of IEC/IEEE 60802 profile compliance and third-party certification, not vendor self-declaration — certification bodies such as TIACC materially reduce interoperability risk. Second, evaluate IEC 62443 alignment alongside deterministic performance; converged traffic classes expand the attack surface, and the USD 5.56M average industrial breach cost means security is evaluated jointly with latency. Third, model switching costs honestly: multi-vendor fieldbus migration requires parallel operation, so services budgets often exceed hardware budgets in year one.
Procurement risk concentrates in timeline slippage. With the 60802 FDIS ballot scheduled for March 2026, equipment qualified to earlier drafts may require re-certification — buyers should negotiate firmware upgrade paths and conformance warranties. Smaller manufacturers face the highest relative cost of upgrade; phased cell-level qualification, rather than facility-wide replacement, is the prudent path. Operators should also insist on software orchestration that maps TSN traffic classes to private 5G URLLC slices, since wireless convergence is set to grow at a 29.87% CAGR and will define network lifecycle economics through 2030.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the mid-case: the Time-Sensitive Networking market compounds near 28–29% through 2030, with Asia-Pacific setting volume and North America and Europe setting value. The strongest counter-argument is Grand View's 6.1% path — that TSN remains a premium niche constrained by configuration complexity and interoperability testing. We reject it as a base case, because mandated 60802 compliance and a 78-million-node brownfield pool create non-discretionary replacement demand that a narrow switch-silicon definition cannot capture. However, the counter-argument correctly warns that adoption will be application-thresholded, not uniform.
Our analysis suggests value capture is migrating from switches toward software orchestration and conformance services. Hardware-centric vendors risk commoditization as 60802 harmonizes multi-vendor behaviour, while vendors combining certified silicon, orchestration software and integration services will sustain pricing power. The automotive zonal architecture cycle is the swing factor: platform-level design wins in Asia-Pacific will determine whether the 29.12% automotive CAGR materializes on schedule.
Vendors: prioritize 60802-conformant switches with attach-rate software orchestration to protect gross margin as hardware commoditizes.
Operators: run cell-level qualification with upgrade-path warranties before facility-wide TSN commitments; budget services at parity with hardware in year one.
Investors: weight exposure toward conformance-certified silicon and services-led integrators; treat pure-play hardware at 60802 FDIS as a repricing event.
The evidence that would change this conclusion: a delayed or fragmented 60802 FDIS beyond 2026, or automotive OEM platform cancellations in Asia-Pacific, which would compress the mid-case toward the low-case range.
Table 14: Europe Time-Sensitive Networking Market Revenue Billion Forecast, by Component 2020 & 2034
Table 15: Europe Time-Sensitive Networking Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the Time-Sensitive Networking market?
The global Time-Sensitive Networking market is estimated at USD 0.57 billion in 2025 and is projected to reach USD 2.02 billion by 2030, a 28.83% CAGR. Definitions vary widely, so buyers should confirm whether estimates include orchestration software and integration services.
2. What is driving Time-Sensitive Networking adoption?
Mandated IEC/IEEE 60802 compliance and IT/OT convergence are the strongest drivers. TSN lets time-critical control traffic share one Ethernet fabric, cutting infrastructure cost by up to 40% and reducing cabling and maintenance in factories and vehicles.
3. Which region leads the Time-Sensitive Networking market?
Asia-Pacific leads with roughly 34% of 2024 revenue and the fastest growth at 28.91% CAGR, driven by Industry 4.0 programs and EV zonal architectures. North America and Europe follow, with North America strongest on IT/OT convergence maturity.
4. Who are the leading Time-Sensitive Networking vendors?
NXP Semiconductors leads with over 15.1% share, and the top five — including Siemens, Intel, Cisco and Microchip — hold 52.55%. Belden, Moxa, TTTech and Analog Devices are also significant, differentiated by certification and platform design wins.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split. We conducted in-depth interviews across the TSN value chain, including semiconductor and switch silicon suppliers, industrial Ethernet equipment producers, network orchestration software vendors, system integrators, and global distributors. Interviewees were designated decision-makers: VP of Sourcing, Heads of Industrial Networking R&D, Technical Directors for Automation, and Commercial Operations Leads. Fieldwork captured qualification timelines, conformance testing friction, and pricing behaviour across factory automation and automotive programs.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
38%
Procurement & Sourcing Leads
32%
Commercial Operations Leads
30%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Semiconductor & Switch Silicon Suppliers
32%
Industrial Ethernet Equipment Producers
30%
Software & Orchestration Vendors
20%
System Integrators & Distributors
18%
Secondary Benchmarking & Public Trade Validation
We triangulate against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies including IEEE 802.1 working groups, IEC, and the Avnu Alliance. Standards roadmaps — notably IEC/IEEE 60802 draft progression — are tracked directly from published committee documents rather than third-party summaries.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down allocation (macroeconomic and industry segment sizing across automation, automotive and utilities) and Bottom-Up modeling (manufacturer capacity, switch and silicon pricing, and end-use consumption). Divergences between the two are reconciled at segment level, with hardware and software valued separately to avoid double counting.


 Time-Sensitive Networking Market