 High Power LED Market
 Outlook, Size & Forecast to 2035
Updated On : Nov 18, 2026|

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 High Power LED Market

Srinwanti Kar
Senior Research Analyst

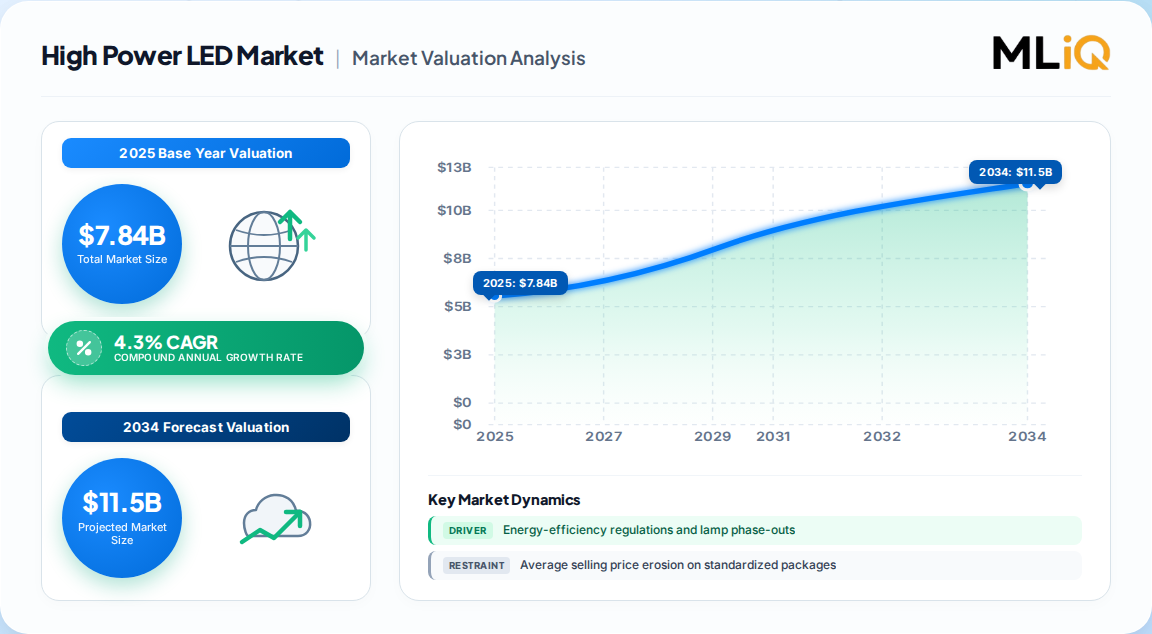
| Year | Market Size |
|---|---|
| 2025 | 7.840 B |
| 2026 | 8.180 B |
| 2027 | 8.530 B |
| 2028 | 8.900 B |
| 2029 | 9.280 B |
| 2030 | 9.680 B |
| 2031 | 10.10 B |

The High Power LED market covers light-emitting diodes packaged at roughly 1 W to 10 W per emitter, paired with optics and thermal substrates rated for tens of thousands of operating hours. These components serve street, area, high-bay, vehicle and specialty lighting where luminous density and lumen maintenance matter more than first cost.
This analysis covers high-power LED emitters and the luminaires, modules and automotive lamp assemblies into which they are integrated, across four applications (automotive lighting, general lighting, backlighting, other) and five regions. It spans 2021 historical data, a 2025 base year and a 2026–2035 forecast horizon. This analysis does not cover mid-power and low-power LED packages, micro-LED and mini-LED display backlighting as a standalone category, LED driver ICs sold separately, or general lighting services revenue.
Published estimates diverge sharply — from 5.8 Billion to 10.5 Billion for 2025 — because each defines the boundary between high-power and mid-power packages differently. The table below isolates that definitional gap, which is the single largest source of variance.
| Estimate (2025) | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 5.8 Billion | 2025 | 2032 | 6.2% | Emitters above 1 W, four applications | One published estimate |
| 5.83 Billion | 2025 | 2033 | 4.20% | Packaging-type split incl. flip chip, mesa, vertical | A competing analysis |
| 6.40 Billion | 2025 | 2035 | 5.75% | Power-rating and colour segmentation | A competing analysis |
| 7,842.6 Million | 2025 | 2035 | 4.30% | 1–10 W emitters plus luminaire integration | One published estimate |
| 10.51 Billion | 2025 | 2034 | 9.60% | Broad package scope incl. mobile devices | A competing analysis |
Our analysis suggests the 7.8 Billion figure is the most defensible for procurement planning: it is built bottom-up from LED package maker shipments cross-checked against luminaire and automotive lamp production volumes, and its 4.3% CAGR sits within the interquartile range of the four conservative estimates. The 9.60% outlier almost certainly folds mobile-device and display packaging into the definition, inflating both base and growth. Buyers should anchor budgets on the 4–6% band and treat anything above 8% as a different market.
Segmentation matters commercially because margin sits in different wattage and package tiers than volume does. The largest revenue pools cluster in general lighting and 1–3 W packages, while the fastest growth concentrates above 10 W and in chip-on-board formats.
| Parent | Children | Largest child | Fastest-growing child |
|---|---|---|---|
| By Application | General Lighting, Automotive Lighting, Backlighting, Other | General Lighting (44.7%) | Automotive (5.4% CAGR) |
| By Power Rating | 1–3 W, 3–5 W, 5–10 W, Above 10 W | 1–3 W (~47.8%) | Above 10 W (~6.6% CAGR) |
| By Packaging Type | Single-Die, Flip Chip, Chip-on-Board, Mesa, Vertical | Single-Die (~36.3%) | Chip-on-Board (~6.8% CAGR) |
| By Colour | White, UV, Colour/Other | White (~78%) | UV (~8.2% CAGR) |
Asia-Pacific leads the High Power LED market on volume and manufacturing depth, holding roughly 41% share, while North America leads on revenue concentration in outdoor retrofit and adaptive-headlamp demand. The two leadership claims are not contradictory — they reflect demand value versus supply base.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.41% |
| North America | 0.27% |
| Europe | 0.24% |
| Latin America | 0.04% |
| Middle East & Africa | 0.04% |
| Region | Share (2025) | Growth posture |
|---|---|---|
| Asia-Pacific | ~41% | Fastest, 5.6% CAGR |
| North America | ~27% (35.8% in one estimate) | Largest revenue pool |
| Europe | ~24% | Regulation-shaped, premium vehicles |
| Latin America | ~4% | Emerging retrofit cycle |
| Middle East & Africa | ~4% | Project-led, small base |
The divergence in North American share — 27% in one model, 35.8% in another — is instructive. It implies one publisher is counting automotive lamp assemblies and another is counting only emitters, a distinction worth roughly 8 points of share. Buyers modelling addressable spend should confirm whether luminaire integration is in scope before committing.
Regulation and municipal procurement drive volume, while price erosion and raw-material concentration cap value realization. The net effect is a market that grows steadily in units but compresses in revenue per lumen.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Energy-efficiency regulations, lamp phase-outs | Driver (+0.9% CAGR) | High — DOE and EU rules dated | Lifts minimum efficacy to 120 lm/W by 2028 |
| Municipal streetlight retrofits | Driver (+0.7%) | High — 13M poles in India, 215K in LA | Tender cycles create repeat channels |
| Vehicle electrification, adaptive headlamps | Driver (+0.8%) | High — 17M EVs sold 2024 | LED headlamps protect driving range |
| Subsidies and tax incentives | Driver (+0.5%) | Medium | Pulls retrofit timelines forward |
| Average selling price erosion | Restraint | High | Standardized packages commoditize |
| Gallium supply and export controls | Restraint | Medium | Input concentration in China |
| Mini/micro-LED substitution in backlighting | Restraint | Medium | Displaces high-power in large displays |
| Thermal management, lumen maintenance | Restraint | Medium | Engineering cost per fixture |
Our analysis suggests the balance favours demand but not margin. The three strongest drivers are all policy-triggered, which means they are predictable — and predictable demand attracts capacity. Competing in tendered streetlight volume will therefore reward cost leadership, while automotive and UV reward qualification and IP. The counter-argument is that gallium export controls could tighten faster than expected, but current evidence points to a supply-risk premium rather than a shortage.
Competition is fragmented and application-specific rather than consolidated around a single leader. Differentiation rests on thermal architecture, optical efficiency, qualification for automotive-grade reliability, and IP position.
| Vendor | Primary strength | Strategic posture |
|---|---|---|
| Nichia Corporation | Phosphor and optical technology | Premium emitter IP |
| ams OSRAM | Automotive and industrial | Broad portfolio, OEM qualification |
| Lumileds | Packaging and illumination | Application-focused parts |
| Samsung Electronics | Display and automotive scale | Volume cost leadership |
| Seoul Semiconductor | Packaging and general lighting | Mid-market penetration |
| Cree LED | High-power, application-specific | Performance positioning |
| Signify Holding | Connected lighting systems | Downstream integration |
The moat has shifted downstream. Emitter design is increasingly replicable; what is not is system-level integration — connected controls, sensor fusion, and qualification for adaptive driving beams under FMVSS No. 108. Our analysis suggests Signify's connected-lighting position and ams OSRAM's automotive qualification are harder to displace than any single-diode performance lead.
Selection should be driven by qualified efficacy under real thermal load, not datasheet peak lumens. Request lumen maintenance data at 60,000 hours at operating junction temperature, and verify DesignLights Consortium listing if utility rebates are part of the business case — most US rebate programs are tied to that qualification.
Procurement risk concentrates in three areas. First, gallium and substrate sourcing: vendors without disclosed supply diversification carry a hidden single-point-of-failure. Second, colour binning consistency, which matters more for architectural and automotive than for roadway use. Third, regulatory compliance timelines — if the U.S. general service lamp rule lifts minimum efficacy above 120 lm/W from July 2028, any fixture specified today should already clear that threshold to avoid stranded assets.
Switching costs are moderate for emitters but high at the system level. Once a municipality standardizes on a driver, optic and control protocol, changing the emitter means requalifying the whole luminaire. Operators should treat the first retrofit cycle as a lock-in decision and negotiate multi-year pricing accordingly.
The balance of evidence favours steady, policy-secured volume growth over a margin-rich expansion. A 4.3% CAGR is unexciting in isolation, but it is anchored to dated regulation and funded municipal programs rather than discretionary spending, which makes it unusually reliable for capital planning. The most defensible position is that high-power LED demand is now a replacement market disguised as a growth market.
The strongest counter-argument is the 9.6% CAGR case, which assumes smart-city and IoT integration unlocks a new value layer. That is plausible — connected poles with sensors do raise content per fixture — but it is a systems-revenue argument that emitter suppliers capture only partially. Treat it as upside, not as the base case.
Actionable strategy:
What would change our conclusion: a binding, near-term gallium export restriction, or evidence that adaptive headlamp penetration is accelerating faster than EV volumes imply. Either would move this market from steady replacement to constrained-growth dynamics.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.3% from 2020-2034 |
| Segmentation |
|
Around 4.3% CAGR from 2026 to 2035 in the conservative consensus, rising to 5.75–6.2% under broader definitions and 9.6% where mobile and display packaging is included. The gap reflects package-scope differences rather than genuine demand disagreement.
General lighting leads at roughly 44.7% share, driven by streetlight, high-bay and area-lighting retrofits. Automotive lighting is the fastest-growing application at 5.4% CAGR as LED headlamps become standard on electric vehicles.
North America holds the largest revenue share at 27–36% depending on whether luminaire integration is counted, supported by municipal retrofits and adaptive headlamp adoption. Asia-Pacific leads on volume and grows fastest at 5.6% CAGR.
Nichia Corporation, ams OSRAM, Lumileds, Samsung Electronics, Seoul Semiconductor and Cree LED lead emitter supply, while Signify Holding and Siemens compete at the connected-systems and infrastructure integration layer.
Average selling price erosion on standardized packages, gallium supply concentration and export controls, thermal management costs, and mini-LED substitution in large-area display backlighting. Margin compression, not volume loss, is the primary constraint.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. We conducted structured interviews with stakeholders across the LED value chain: epitaxial wafer and substrate suppliers, LED package manufacturers, luminaire and automotive lamp assemblers, and global lighting distributors. Interviewees included VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads at luminaire OEMs. Fieldwork also covered municipal procurement officers managing streetlight retrofit tenders, who provided forward visibility on tender cycles not available in published data.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 38% |
| Procurement & Sourcing Leads | 34% |
| Commercial Operations Heads | 18% |
| Regulatory & Compliance Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| LED Package & Emitter Manufacturers | 40% |
| Luminaire & Automotive Lamp Assemblers | 30% |
| Substrate & Epitaxial Material Suppliers | 18% |
| Global Distributors & Procurement Bodies | 12% |
We validated findings against UN Comtrade and US ITC trade flows for LED packages and gallium-bearing inputs, Eurostat industrial production data, and corporate annual filings including 10-K disclosures and investor presentations. Patent databases were screened for high-power packaging and adaptive-headlamp IP. Technical standards and association publications from the DesignLights Consortium, IEC, and the International Energy Agency's lighting efficiency work provided the regulatory backbone.
We ran simultaneous top-down and bottom-up models. The top-down path allocates macroeconomic lighting and automotive production value to the high-power segment. The bottom-up path builds from manufacturer capacity, product pricing and end-use consumption by application, then reconciles the two within a defined variance band.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |