Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Emission Monitoring System Market: 2026 Size & Forecast
Emission Monitoring System Market
Emission Monitoring System Market: 2026 Size & Forecast
Emission Monitoring System Market by Type (Continuous Emission Monitoring System (CEMS), Predictive Emission Monitoring System (PEMS)), by Component (Hardware, Software, Service), by End-User (Oil and Gas, Chemicals and Fertilizers, Iron and Steel, Power Generation, Pharmaceuticals, Food and Beverage, Healthcare, Mining, Waste-to-Energy, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
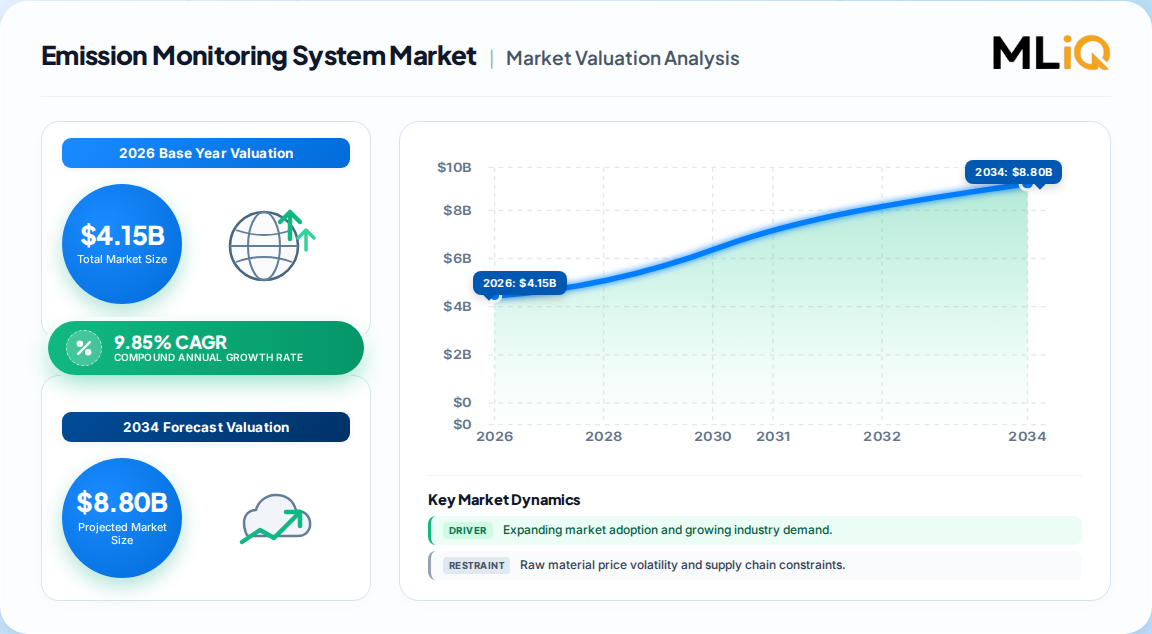
USD 4.15 Billion in 2026 is the most defensible base for the global emission monitoring system market, rising to USD 8.80 Billion by 2034 at a 9.85% CAGR under the most recent published estimate.
Continuous Emission Monitoring Systems (CEMS) lead, capturing roughly 61% of type revenue in 2025; Predictive EMS is the fastest-advancing sub-segment.
North America leads with ~34% share, but Asia-Pacific grows fastest at ~10.4% CAGR, driven by industrial build-out and tightening air-quality regulation.
Oil and gas is the largest end-user (~25% share), with chemicals and fertilizers, iron and steel, power, and waste-to-energy advancing quickly.
Software and services are the margin engine, growing near 9.8% CAGR as data-management, reporting, and cybersecurity requirements intensify.
Emerson, Siemens, Honeywell, ABB, Teledyne, and Horiba anchor a moderately concentrated, innovation-led vendor field.
Why this matters for decision-makers: Buyers should budget for recurring software, calibration, and cybersecurity costs, not just analyzer hardware, because total cost of ownership increasingly sits outside the stack sensor.
Emission Monitoring System Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
3.780 B
2025
4.150 B
2026
4.560 B
2027
5.010 B
2028
5.500 B
2029
6.040 B
2030
6.640 B
2031
Emission Monitoring System Market Size (In Billion)
Year
Market Size
2025
3.780 B
2026
4.150 B
2027
4.560 B
2028
5.010 B
2029
5.500 B
2030
6.040 B
2031
6.640 B
What is the Emission Monitoring System Market?
The emission monitoring system (EMS) market covers the analyzers, sample-conditioning hardware, data acquisition and handling software, and services used to measure and report pollutants from industrial exhaust streams. Systems track SO2, NOx, CO2, particulate matter, mercury, VOCs, and methane for regulatory compliance and corporate disclosure. CEMS and PEMS are the two principal architectures.
Scope: what this report covers and excludes
This analysis covers global EMS demand across CEMS and PEMS types, hardware, software, and service components, and end-users spanning oil and gas, chemicals and fertilizers, iron and steel, power generation, pharmaceuticals, food and beverage, mining, and waste-to-energy. It addresses regulatory, technological, and competitive dynamics shaping 2026–2034. This analysis does not cover ambient air-quality monitoring networks, indoor air-quality sensors, laboratory analytical instrumentation, or vehicle on-board diagnostics.
How big is the market for Emission Monitoring System Market?
The global emission monitoring system market was most credibly sized at USD 4.15 billion for 2026, with a path to USD 8.80 billion by 2034 at 9.85% CAGR, based on the most recent published estimate with a full segment and regional breakdown. Competing analyses bracket this range, and the divergence is instructive.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 3.50 Billion → 6.71 Billion
2023
2030
10.3%
Global EMS, CEMS + PEMS, hardware-led
One published estimate (2024)
USD 4.07 Billion → 7.51 Billion
2025
2035
6.3%
Global EMS, broader verticals incl. pulp and paper
A competing analysis (2026)
USD 3.78 Billion → 8.80 Billion
2025
2034
9.85%
Global EMS, full component and end-user split
Most recent published estimate (2026)
USD 1.13 Billion → 1.92 Billion
2023
2030
7.9%
United States only
U.S. country databook
The spread between 6.3% and 10.3% CAGR is largely a scope artifact: broader-vertical definitions dilute growth, while CEMS-heavy, software-inclusive scopes lift it. Our analysis favors the 9.85% trajectory because it reconciles U.S. country-level growth (7.9%) with faster Asia-Pacific expansion, implying a mid-to-high single-digit global blended rate climbing toward double digits as carbon reporting matures. The 6.3% figure likely understates software and methane-detection upside.
How is the market segmented?
Segmentation follows three axes: system type, component, and end-user. Type is the primary revenue lens, with CEMS commanding the majority of spend and PEMS gaining on lower capital intensity and modeling-driven flexibility.
Parent segment
Children
By Type
Continuous Emission Monitoring System (CEMS), Predictive Emission Monitoring System (PEMS)
By Component
Hardware, Software, Service
By End-User
Oil and Gas, Chemicals and Fertilizers, Iron and Steel, Power Generation, Pharmaceuticals, Food and Beverage, Healthcare, Mining, Waste-to-Energy, Others
CEMS dominance reflects regulatory mandates for continuous stationary-source measurement at power plants, cement kilns, pulp mills, and incinerators. PEMS is winning where capital budgets are tight and process modeling can substitute for full analyzer stacks. On components, hardware still carries the majority of revenue, but software is the fastest-growing slice as data acquisition, reporting, and cybersecurity requirements expand. Oil and gas leads end-use at roughly a quarter of revenue, with chemicals and power close behind.
Which region leads in Emission Monitoring System Market?
North America leads the global emission monitoring system market with roughly 34% revenue share, anchored by U.S. EPA rules and a dense installed base. Asia-Pacific is the fastest-growing region at about 10.4% CAGR, powered by Chinese, Indian, and Southeast Asian industrial expansion.
Emission Monitoring System Market Regional Market Share
Loading chart...
Emission Monitoring System Market Regional Market Share
Region
Market Share (%)
North America
0.34%
Europe
0.26%
Asia-Pacific
0.31%
Latin America
0.05%
Middle East & Africa
0.04%
North America — U.S., Canada, Mexico
Europe — Germany, UK, France, Italy
Asia-Pacific — China, Japan, India, South Korea
Latin America — Brazil, Mexico, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa
Region
2025 share (approx.)
North America
34%
Europe
26%
Asia-Pacific
31%
Latin America
5%
Middle East & Africa
4%
The U.S. alone accounted for roughly 27% of global revenue in 2023, and its country market is projected to reach USD 1.92 billion by 2030 at 7.9% CAGR. Our analysis suggests the regional balance will shift modestly toward Asia-Pacific through 2034 as new capacity is built to tighter standards, but North America's retrofit and enforcement cycle keeps it the revenue anchor.
What is driving growth — and what is holding it back?
Regulation is the dominant growth engine: stricter industrial emission limits and expanding carbon disclosure requirements force investment in verifiable measurement. Methane rules, including facility-level continuous detection thresholds, are pulling new demand into oil and gas.
Factor
Direction
Evidence strength
Mechanism
Stricter industrial emission limits
Driver
High
Mandated CEMS at power, cement, chemical plants
Carbon reporting and disclosure
Driver
High
Structured emissions data for corporate filings
Continuous methane detection rules
Driver
Medium-High
Facility-level uptime and leak-threshold requirements
Remote and satellite sensing
Driver
Medium
Coverage of dispersed and fugitive sources
High initial system cost
Restraint
High
Capital burden delays SME adoption
Installation and integration complexity
Restraint
Medium
Engineering, calibration, compatibility costs
Sensor drift and calibration load
Challenge
Medium
Harsh conditions erode accuracy and uptime
Data management and cybersecurity
Challenge
Medium
Continuous data streams raise software risk
The balance of evidence favors demand: regulatory drivers are non-discretionary and compounding, while cost and complexity are cyclical and falling as software-defined architectures mature. The key second-order effect is that value is migrating from analyzer boxes to data integrity and uptime guarantees, which favors vendors with service networks.
Who are the leading vendors?
The vendor field is moderately concentrated, with diversified automation majors competing against specialized analyzer makers. Differentiation rests on analyzer accuracy, calibration service depth, software integration, and regulatory certification breadth.
Company
HQ
Primary strength
Emerson Electric
U.S.
Process automation and CEMS integration
Siemens AG
Germany
Analyzer hardware and plant controls
Honeywell
U.S.
Leak detection and monitoring software
ABB Ltd
Switzerland
System integration and waste-to-energy
Teledyne Technologies
U.S.
Gas analyzer and sensor depth
Horiba Ltd
Japan
Analytical and emissions instrumentation
AMETEK
U.S.
Process and environmental analyzers
SICK AG
Germany
Optical and in-situ gas measurement
Our analysis suggests incumbents' moats are built on installed-base service contracts and regulatory certifications rather than raw hardware performance, which is increasingly commoditized. That makes data platforms and uptime guarantees the decisive battleground through 2034.
What do buyers and operators need to know?
Buyers should evaluate total cost of ownership across a five-to-ten year horizon, because calibration, consumables, software licenses, and cybersecurity patching often exceed initial hardware spend. Procurement risk concentrates in integration with existing DCS and plant networks; specification should demand proven compatibility and defined commissioning timelines.
Switching costs are high once a CEMS is certified and embedded in compliance workflows, so first-purchase decisions carry long tails. Regulatory certification breadth matters more than price in regulated jurisdictions. Operators should also contract for data ownership and export rights to avoid lock-in as disclosure regimes evolve. Finally, uptime guarantees and remote diagnostics are now table stakes; buyers should treat service-level agreements as core specification, not an afterthought.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the higher-growth trajectory for the emission monitoring system market: regulatory drivers are structural and expanding into methane and carbon reporting, while the cost and complexity restraints are eroding as software-defined systems mature. The strongest counter-argument is that capital-constrained SMEs in emerging markets will delay adoption, capping volume growth; that risk is real but is more than offset by mandated spending at large regulated facilities.
Our analysis suggests the most important shift is margin migration from hardware to software and services. Vendors that anchor revenue in analyzers alone will face pricing pressure as sensor costs fall; those that bundle data acquisition, reporting, calibration, and cybersecurity into recurring contracts will capture disproportionate value. Buyers, conversely, should negotiate multi-year service agreements early to lock favorable terms before renewal cycles tighten.
Investors: prioritize vendors with recurring software and service revenue above 30% of EMS segment sales; these command premium multiples as hardware commoditizes.
Operators: budget 40–60% of lifecycle cost for calibration, software, and cybersecurity, and specify data export rights in every contract.
Vendors: target Asia-Pacific power and oil and gas greenfield projects with PEMS-led offerings to win share before CEMS retrofit cycles dominate.
The evidence that would change our conclusion is a sustained slowdown in U.S. and EU enforcement funding, or a step-change decline in analyzer costs that collapses hardware pricing faster than software attach can offset.
Emission Monitoring System Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Emission Monitoring System Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 9.85% from 2020-2034
Segmentation
By Type
Continuous Emission Monitoring System (CEMS)
Predictive Emission Monitoring System (PEMS)
By Component
Hardware
Software
Service
By End-User
Oil and Gas
Chemicals and Fertilizers
Iron and Steel
Power Generation
Pharmaceuticals
Food and Beverage
Healthcare
Mining
Waste-to-Energy
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Emission Monitoring System Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Emission Monitoring System Market Executive Summary
2.1. Market Snapshot
3. Emission Monitoring System Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Emission Monitoring System Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Emission Monitoring System Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Continuous Emission Monitoring System (CEMS)
5.1.2. Predictive Emission Monitoring System (PEMS)
5.2. Analysis, Insights and Forecast - by Component
5.2.1. Hardware
5.2.2. Software
5.2.3. Service
5.3. Analysis, Insights and Forecast - by End-User
5.3.1. Oil and Gas
5.3.2. Chemicals and Fertilizers
5.3.3. Iron and Steel
5.3.4. Power Generation
5.3.5. Pharmaceuticals
5.3.6. Food and Beverage
5.3.7. Healthcare
5.3.8. Mining
5.3.9. Waste-to-Energy
5.3.10. Others
5.4. Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. Emission Monitoring System Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Continuous Emission Monitoring System (CEMS)
6.1.2. Predictive Emission Monitoring System (PEMS)
6.2. Analysis, Insights and Forecast - by Component
6.2.1. Hardware
6.2.2. Software
6.2.3. Service
6.3. Analysis, Insights and Forecast - by End-User
6.3.1. Oil and Gas
6.3.2. Chemicals and Fertilizers
6.3.3. Iron and Steel
6.3.4. Power Generation
6.3.5. Pharmaceuticals
6.3.6. Food and Beverage
6.3.7. Healthcare
6.3.8. Mining
6.3.9. Waste-to-Energy
6.3.10. Others
7. Emission Monitoring System Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Continuous Emission Monitoring System (CEMS)
7.1.2. Predictive Emission Monitoring System (PEMS)
7.2. Analysis, Insights and Forecast - by Component
7.2.1. Hardware
7.2.2. Software
7.2.3. Service
7.3. Analysis, Insights and Forecast - by End-User
7.3.1. Oil and Gas
7.3.2. Chemicals and Fertilizers
7.3.3. Iron and Steel
7.3.4. Power Generation
7.3.5. Pharmaceuticals
7.3.6. Food and Beverage
7.3.7. Healthcare
7.3.8. Mining
7.3.9. Waste-to-Energy
7.3.10. Others
8. Emission Monitoring System Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Continuous Emission Monitoring System (CEMS)
8.1.2. Predictive Emission Monitoring System (PEMS)
8.2. Analysis, Insights and Forecast - by Component
8.2.1. Hardware
8.2.2. Software
8.2.3. Service
8.3. Analysis, Insights and Forecast - by End-User
8.3.1. Oil and Gas
8.3.2. Chemicals and Fertilizers
8.3.3. Iron and Steel
8.3.4. Power Generation
8.3.5. Pharmaceuticals
8.3.6. Food and Beverage
8.3.7. Healthcare
8.3.8. Mining
8.3.9. Waste-to-Energy
8.3.10. Others
9. Emission Monitoring System Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Continuous Emission Monitoring System (CEMS)
9.1.2. Predictive Emission Monitoring System (PEMS)
9.2. Analysis, Insights and Forecast - by Component
9.2.1. Hardware
9.2.2. Software
9.2.3. Service
9.3. Analysis, Insights and Forecast - by End-User
9.3.1. Oil and Gas
9.3.2. Chemicals and Fertilizers
9.3.3. Iron and Steel
9.3.4. Power Generation
9.3.5. Pharmaceuticals
9.3.6. Food and Beverage
9.3.7. Healthcare
9.3.8. Mining
9.3.9. Waste-to-Energy
9.3.10. Others
10. Emission Monitoring System Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Continuous Emission Monitoring System (CEMS)
10.1.2. Predictive Emission Monitoring System (PEMS)
10.2. Analysis, Insights and Forecast - by Component
10.2.1. Hardware
10.2.2. Software
10.2.3. Service
10.3. Analysis, Insights and Forecast - by End-User
10.3.1. Oil and Gas
10.3.2. Chemicals and Fertilizers
10.3.3. Iron and Steel
10.3.4. Power Generation
10.3.5. Pharmaceuticals
10.3.6. Food and Beverage
10.3.7. Healthcare
10.3.8. Mining
10.3.9. Waste-to-Energy
10.3.10. Others
11. Emission Monitoring System Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Emission Monitoring System Market Research Methodology
List of Figures
Figure 1: Emission Monitoring System Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Emission Monitoring System Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Emission Monitoring System Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Emission Monitoring System Market Revenue (Billion), by Component 2026 & 2034
Figure 5: North America Emission Monitoring System Market Revenue Share (%), by Component 2026 & 2034
Figure 6: North America Emission Monitoring System Market Revenue (Billion), by End-User 2026 & 2034
Figure 7: North America Emission Monitoring System Market Revenue Share (%), by End-User 2026 & 2034
Figure 8: North America Emission Monitoring System Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Emission Monitoring System Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Emission Monitoring System Market Revenue (Billion), by Type 2026 & 2034
Figure 11: Europe Emission Monitoring System Market Revenue Share (%), by Type 2026 & 2034
Figure 12: Europe Emission Monitoring System Market Revenue (Billion), by Component 2026 & 2034
Figure 13: Europe Emission Monitoring System Market Revenue Share (%), by Component 2026 & 2034
Figure 14: Europe Emission Monitoring System Market Revenue (Billion), by End-User 2026 & 2034
Figure 15: Europe Emission Monitoring System Market Revenue Share (%), by End-User 2026 & 2034
Figure 16: Europe Emission Monitoring System Market Revenue (Billion), by Country 2026 & 2034
List of Tables
Table 1: Emission Monitoring System Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Emission Monitoring System Market Revenue Billion Forecast, by Component 2020 & 2034
Table 3: Emission Monitoring System Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 4: Emission Monitoring System Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America Emission Monitoring System Market Revenue Billion Forecast, by Type 2020 & 2034
Table 6: North America Emission Monitoring System Market Revenue Billion Forecast, by Component 2020 & 2034
Table 7: North America Emission Monitoring System Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 8: North America Emission Monitoring System Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA Emission Monitoring System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada Emission Monitoring System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Emission Monitoring System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe Emission Monitoring System Market Revenue Billion Forecast, by Type 2020 & 2034
Table 13: Europe Emission Monitoring System Market Revenue Billion Forecast, by Component 2020 & 2034
Table 14: Europe Emission Monitoring System Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 15: Europe Emission Monitoring System Market Revenue Billion Forecast, by Country 2020 & 2034
Germany Emission Monitoring System Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the emission monitoring system market size in 2026?
The global emission monitoring system market is estimated at USD 4.15 billion in 2026. It is projected to reach USD 8.80 billion by 2034, growing at a 9.85% CAGR over the forecast period.
2. Which region leads the emission monitoring system market?
North America leads with roughly 34% of global revenue in 2025, supported by U.S. EPA regulations and a dense installed base. Asia-Pacific is the fastest-growing region at about 10.4% CAGR.
3. Which segment dominates the emission monitoring system market?
Continuous Emission Monitoring Systems (CEMS) dominate, holding about 61% of type revenue in 2025. Predictive Emission Monitoring Systems are the fastest-growing sub-segment as modeling substitutes for full analyzer stacks.
4. Who are the key players in the emission monitoring system market?
Leading vendors include Emerson, Siemens, Honeywell, ABB, Teledyne Technologies, Horiba, AMETEK, and SICK AG. Competition centers on analyzer accuracy, calibration service depth, software integration, and regulatory certification breadth.
5. Why is the emission monitoring system market growing?
Growth is driven by stricter industrial emission limits, expanding carbon disclosure requirements, and new continuous methane detection rules. High initial system cost and integration complexity are the main restraints on faster adoption.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research operates on a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the EMS value chain: analyzer and sensor manufacturers, system integrators, calibration and service providers, and industrial end-users. Decision-maker designations interviewed included VP-level sourcing leads, Heads of Environmental Compliance, Technical Directors of instrumentation, and Commercial Operations Leads at process-automation firms.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Environmental Compliance Heads
35%
Sourcing & Procurement VPs
30%
Technical & Instrumentation Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Analyzer & Sensor Manufacturers
40%
System Integrators
30%
Calibration & Service Providers
20%
Industrial End-Users
10%
Secondary Benchmarking & Public Trade Validation
We triangulate against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and technical standards from recognized bodies including ISO and national environmental agencies. This anchors every estimate in verifiable public evidence rather than single-source claims.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic and industry-segment allocation) and Bottom-Up (manufacturer capacity, unit pricing, and end-use consumption) models, then reconcile the two to produce a defensible base-year valuation and compound forecast.


 Emission Monitoring System Market