Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Superconductors Market Size, Share & Forecast to 2035
Superconductors Market Size, Share & Forecast to 2035
Superconductors Market
Superconductors Market Size, Share & Forecast to 2035
Superconductors Market by Type (Low-Temperature Superconductors, High-Temperature Superconductors, Superconducting Tapes and Wires), by Material Type (Cuprate Superconductors, Iron-Based Superconductors, Magnesium Diboride Superconductors), by Application (Medical Imaging, Power Transmission, Magnetic Resonance Imaging, Particle Accelerators, Fusion Energy), by End-Use Industry (Healthcare, Energy and Power, Transportation, Manufacturing, Electronics and Quantum Technology), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Rest of Europe), by Asia Pacific (China, Japan, South Korea, India, Rest of Asia-Pacific), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 277
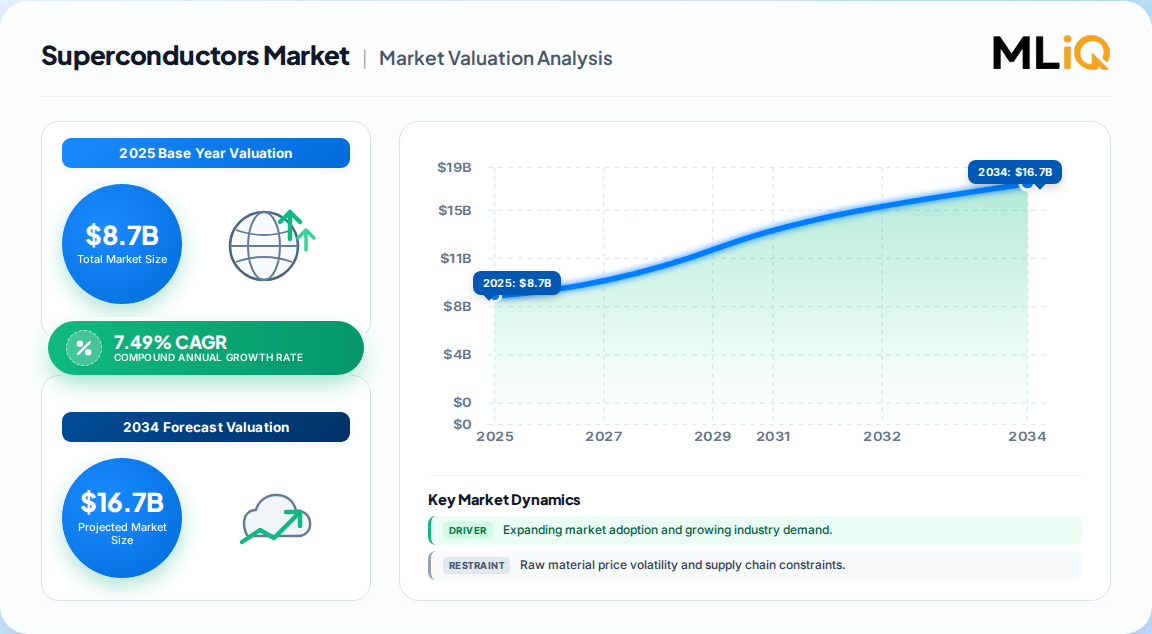
USD 8.7 Billion in 2025 — the base-year superconductor market size, global scope, all conductor types and end uses.
7.49% CAGR (2026–2034) is the most defensible growth rate; competing estimates range from 7.49% to 11.8% depending on whether quantum and fusion are fully counted.
USD 16.9 Billion by 2034 is the mid-case forecast; aggressive HTS-capacity scenarios reach USD 30 Billion by 2035.
High-temperature superconductors (HTS) hold 52.8% of revenue and grow fastest at 9.47% CAGR, displacing LTS in new-build projects.
North America leads with roughly 38–48% share, while Asia-Pacific is the fastest-growing region at 9.27% CAGR, anchored by China and Japan.
Bruker, Fujikura, Sumitomo Electric, American Superconductor and Furukawa form the core vendor set; consolidation is accelerating around REBCO tape capacity.
Why this matters for decision-makers: Conductor supply — not demand — is the binding constraint through 2030. Buyers who lock multi-year REBCO and Nb3Sn offtake now will avoid the qualification bottlenecks that will define 2028–2032 project economics.
Superconductors Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.700 B
2025
9.500 B
2026
10.20 B
2027
11.00 B
2028
11.80 B
2029
12.70 B
2030
13.70 B
2031
Superconductors Market Size (In Billion)
Year
Market Size
2025
8.700 B
2026
9.500 B
2027
10.20 B
2028
11.00 B
2029
11.80 B
2030
12.70 B
2031
13.70 B
What is the Superconductors Market?
The superconductors market covers materials that carry direct current with zero electrical resistance below a critical temperature, plus the tapes, wires and magnets fabricated from them. It spans low-temperature superconductors (LTS), high-temperature superconductors (HTS), cuprates, iron-based and magnesium diboride materials sold into medical imaging, power, fusion, transport and quantum computing.
Scope: what this report covers and excludes
This analysis covers global demand for LTS and HTS conductors, superconducting tapes and wires, cuprate, iron-based and magnesium diboride materials, and end-use consumption across healthcare, energy and power, transportation, manufacturing, electronics and quantum technology. It addresses both merchant conductor supply and captive magnet production.
This analysis does not cover conventional copper and aluminium conductors, non-superconducting permanent magnets, cryogenic equipment as a standalone category, or the downstream MRI and NMR system market beyond its conductor content.
How big is the market for Superconductors Market?
Published estimates for the global superconductor market diverge by more than 3x because analysts disagree on whether fusion, quantum and grid-cable programmes are counted at conductor value or at system value. The table below reconciles the principal benchmarks.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
USD 8.7 Billion
2025
2034
7.49%
Conductor and magnet value, all applications
One published estimate (IMARC)
USD 9.4 Billion
2025
2030
11.8%
Conductor value, fusion and maglev weighted
One published estimate (BCC Research)
USD 11.1 Billion
2025
2035
10.52%
Broad definition including tapes, wires and systems
One published estimate (Market Research Future)
USD 1.45 Billion
2026
2031
7.89%
Narrow merchant conductor-only revenue
One published estimate (Mordor Intelligence)
Our analysis suggests the USD 8.7 Billion base with a 7.49% CAGR is the most defensible central case. The USD 1.45 Billion figure almost certainly excludes captive magnet production inside MRI and accelerator OEMs, which is where the majority of LTS value sits. Conversely, the 11.8% CAGR requires fusion procurement to scale on schedule — a plausible but not yet evidenced assumption.
The practical implication for buyers is that planning should be anchored to the 7.5–8% corridor, with upside optionality if ITER-adjacent and private tokamak programmes convert to firm conductor orders before 2029.
How is the market segmented?
Segmentation matters because growth rates differ sharply by node: HTS tape grows at roughly twice the rate of established LTS wire, and fusion/accelerator applications outpace medical imaging by more than 4 percentage points.
Parent segment
Children
Growth signal
By Type
Low-temperature superconductors, High-temperature superconductors, Superconducting tapes and wires
HTS 52.8% share, 9.47% CAGR
By Material Type
Cuprate, Iron-based, Magnesium diboride
Cuprates 55.7% share; MgB2 9.42% CAGR
By Application
Medical imaging, Power transmission, MRI, Particle accelerators, Fusion energy
Medical imaging 42.7% share; fusion/accelerators 11.35% CAGR
By End-Use Industry
Healthcare, Energy and power, Transportation, Manufacturing, Electronics and quantum
The segmentation reveals a market with a stable, replacement-driven core (MRI magnets) and a high-growth, project-driven periphery (fusion, grid cables, quantum). Our analysis suggests suppliers that only serve the core will see revenue growth converge toward 6%, while those qualified on fusion and HTS tape can sustain double-digit growth.
Which region leads in Superconductors Market?
North America leads the global superconductor market with approximately 38–48% of revenue, depending on whether captive OEM magnet production is included. Asia-Pacific is the fastest-growing region at a 9.27% CAGR, driven by Japanese and Chinese REBCO tape capacity and Korean fusion procurement.
Superconductors Market Regional Market Share
Loading chart...
Superconductors Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.24%
Asia Pacific
0.29%
South America
0.04%
Middle East & Africa
0.05%
North America
United States
Canada
Mexico
Europe
Germany
United Kingdom
France
Italy
Rest of Europe
Asia Pacific
China
Japan
South Korea
India
Rest of Asia-Pacific
South America
Brazil
Mexico-adjacent trade blocs
Middle East & Africa
Saudi Arabia
UAE
South Africa
The regional divergence carries a clear strategic signal. North America's lead is concentrated in MRI replacement demand and defence electronics, which are relatively price-insensitive but contractually sticky. Asia-Pacific's growth is capacity-led: Japan and China are adding long-length REBCO tape lines that will determine global supply from 2028 onward. Europe's position is weakest on supply security — as one EU industry submission noted, the bloc is highly dependent on REBCO imports from a small number of non-European suppliers.
This divergence implies European buyers face the highest supply-chain risk and should be prioritizing qualification of alternative tape sources ahead of 2030.
What is driving growth — and what is holding it back?
Growth is driven by MRI fleet replacement, fusion energy procurement, grid modernisation in dense urban corridors, and the emergence of superconducting components for AI data-centre power. Restraints centre on cryogenic operating costs, long qualification cycles and thin long-length tape capacity.
Factor
Direction
Evidence strength
Mechanism
High-field MRI replacement cycle
Driver
High
1.5T/3.0T systems installed 2000–2010 reaching end of life; +2.1% CAGR impact
Fusion and particle accelerator projects
Driver
High
ITER magnet testing and private tokamaks create firm Nb3Sn/REBCO demand; +1.8%
Grid modernisation and HTS cables
Driver
Medium
HTS cables carry 3–5x XLPE power in 10x narrower corridors; +1.5%
Liquid helium and cooling plant dominate total cost of ownership
Long-length REBCO tape yield
Restraint
High
Critical-current variability at tape edges raises qualification waste
Raw material and processing cost
Restraint
Medium
Rare-earth and niobium price volatility compresses margins
The balance of evidence favours the drivers through 2030. Medical imaging alone provides a floor of roughly 40% of revenue that is largely immune to macroeconomic cycles, while fusion adds a credible long-cycle growth layer. However, the restraints are not trivial: cryogenic economics still prevent superconducting cables from competing with conventional conductors outside space-constrained urban corridors. Our analysis suggests the market will grow steadily rather than explosively, with the 11.8% upper estimate requiring fusion to convert from pilot to procurement at scale.
Who are the leading vendors?
The superconductor vendor landscape is moderately concentrated and split between integrated Japanese and European conductor producers and specialist American and Chinese magnet and tape suppliers.
Differentiation rests on three moats: long-length tape yield consistency, application-close testing capability, and multi-year offtake relationships with OEMs. Bruker's 2026 announcement of USD 500 million in multi-year MRI superconductor supply agreements illustrates how contract length, not price, has become the decisive competitive variable. Vendors without locked offtake will find capacity expansion difficult to finance.
What do buyers and operators need to know? (Decision Support)
Procurement in this market is engineering-led, not price-led. The dominant selection criteria are critical-current consistency over long lengths, traceability for fusion and accelerator qualification, helium consumption per magnet, and the supplier's ability to support field service over a 10–15 year asset life. Buyers should treat tape edge-quality data and flux-jump behaviour as non-negotiable qualification gates.
Switching costs are high and asymmetric. Once a conductor is qualified into an MRI platform or a fusion magnet design, requalification typically takes 12–24 months and carries programme-schedule risk. This locks buyers in but also locks suppliers into fixed capacity allocations, which is why multi-year agreements are becoming standard.
Regulatory and standards exposure is concentrated in medical device compliance, nuclear safety-grade requirements for fusion, and emerging critical-materials designations. The European Union's Advanced Materials Act consultation is a leading indicator that REBCO may be classified as a strategic material, which would change import dependency risk and could trigger domestic-content requirements. Operators should model this scenario explicitly rather than treat it as tail risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours a steady-growth, supply-constrained market rather than a demand-constrained one. The most credible reading of the benchmarks is a USD 8.7 Billion base growing at roughly 7.5% to 2034, with HTS and fusion applications providing the upside skew. The strongest counter-argument is that fusion timelines routinely slip, and if ITER-adjacent procurement defers by three to five years, the market reverts to a medical-imaging-led 6–7% growth story with far less pricing power for HTS tape producers.
A second-order effect deserves more attention than it receives: the bottleneck is migrating from material discovery to manufacturing yield. As one EU industry submission noted, REBCO tape supply is concentrated in a small number of non-European producers, and testing capacity is limited to facilities such as CERN and SULTAN. This means the winners through 2030 will be defined by qualification throughput and testing access, not by patent portfolios.
Actionable Strategy
For investors: Prioritize conductor producers with locked multi-year offtake and demonstrated long-length yield, over early-stage material developers with unproven scale-up.
For operators and OEMs: Secure REBCO and Nb3Sn supply agreements now, and dual-qualify a second tape source before 2028 to hedge concentration risk.
For European buyers: Treat domestic REBCO capacity and application-close testing access as strategic procurement priorities, given documented import dependency.
The evidence that would change this conclusion is a confirmed slip in ITER and private tokamak construction schedules combined with flat MRI replacement orders — a combination that would push the market toward the low end of the 7–8% corridor.
While this overview reconciles the headline benchmarks, precise sub-segment forecasting — particularly fusion conductor volumes by project and REBCO tape yield economics — requires the full report's bottom-up model.
Superconductors Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Superconductors Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.49% from 2020-2034
Segmentation
By Type
Low-Temperature Superconductors
High-Temperature Superconductors
Superconducting Tapes and Wires
By Material Type
Cuprate Superconductors
Iron-Based Superconductors
Magnesium Diboride Superconductors
By Application
Medical Imaging
Power Transmission
Magnetic Resonance Imaging
Particle Accelerators
Fusion Energy
By End-Use Industry
Healthcare
Energy and Power
Transportation
Manufacturing
Electronics and Quantum Technology
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Rest of Europe
Asia Pacific
China
Japan
South Korea
India
Rest of Asia-Pacific
South America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Superconductors Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Superconductors Market Executive Summary
2.1. Market Snapshot
3. Superconductors Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Superconductors Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Superconductors Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Low-Temperature Superconductors
5.1.2. High-Temperature Superconductors
5.1.3. Superconducting Tapes and Wires
5.2. Analysis, Insights and Forecast - by Material Type
5.2.1. Cuprate Superconductors
5.2.2. Iron-Based Superconductors
5.2.3. Magnesium Diboride Superconductors
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Medical Imaging
5.3.2. Power Transmission
5.3.3. Magnetic Resonance Imaging
5.3.4. Particle Accelerators
5.3.5. Fusion Energy
5.4. Analysis, Insights and Forecast - by End-Use Industry
5.4.1. Healthcare
5.4.2. Energy and Power
5.4.3. Transportation
5.4.4. Manufacturing
5.4.5. Electronics and Quantum Technology
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. Superconductors Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Low-Temperature Superconductors
6.1.2. High-Temperature Superconductors
6.1.3. Superconducting Tapes and Wires
6.2. Analysis, Insights and Forecast - by Material Type
6.2.1. Cuprate Superconductors
6.2.2. Iron-Based Superconductors
6.2.3. Magnesium Diboride Superconductors
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Medical Imaging
6.3.2. Power Transmission
6.3.3. Magnetic Resonance Imaging
6.3.4. Particle Accelerators
6.3.5. Fusion Energy
6.4. Analysis, Insights and Forecast - by End-Use Industry
6.4.1. Healthcare
6.4.2. Energy and Power
6.4.3. Transportation
6.4.4. Manufacturing
6.4.5. Electronics and Quantum Technology
7. Superconductors Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Low-Temperature Superconductors
7.1.2. High-Temperature Superconductors
7.1.3. Superconducting Tapes and Wires
7.2. Analysis, Insights and Forecast - by Material Type
7.2.1. Cuprate Superconductors
7.2.2. Iron-Based Superconductors
7.2.3. Magnesium Diboride Superconductors
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Medical Imaging
7.3.2. Power Transmission
7.3.3. Magnetic Resonance Imaging
7.3.4. Particle Accelerators
7.3.5. Fusion Energy
7.4. Analysis, Insights and Forecast - by End-Use Industry
7.4.1. Healthcare
7.4.2. Energy and Power
7.4.3. Transportation
7.4.4. Manufacturing
7.4.5. Electronics and Quantum Technology
8. Superconductors Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Low-Temperature Superconductors
8.1.2. High-Temperature Superconductors
8.1.3. Superconducting Tapes and Wires
8.2. Analysis, Insights and Forecast - by Material Type
8.2.1. Cuprate Superconductors
8.2.2. Iron-Based Superconductors
8.2.3. Magnesium Diboride Superconductors
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Medical Imaging
8.3.2. Power Transmission
8.3.3. Magnetic Resonance Imaging
8.3.4. Particle Accelerators
8.3.5. Fusion Energy
8.4. Analysis, Insights and Forecast - by End-Use Industry
8.4.1. Healthcare
8.4.2. Energy and Power
8.4.3. Transportation
8.4.4. Manufacturing
8.4.5. Electronics and Quantum Technology
9. Superconductors Market South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Low-Temperature Superconductors
9.1.2. High-Temperature Superconductors
9.1.3. Superconducting Tapes and Wires
9.2. Analysis, Insights and Forecast - by Material Type
9.2.1. Cuprate Superconductors
9.2.2. Iron-Based Superconductors
9.2.3. Magnesium Diboride Superconductors
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Medical Imaging
9.3.2. Power Transmission
9.3.3. Magnetic Resonance Imaging
9.3.4. Particle Accelerators
9.3.5. Fusion Energy
9.4. Analysis, Insights and Forecast - by End-Use Industry
9.4.1. Healthcare
9.4.2. Energy and Power
9.4.3. Transportation
9.4.4. Manufacturing
9.4.5. Electronics and Quantum Technology
10. Superconductors Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Low-Temperature Superconductors
10.1.2. High-Temperature Superconductors
10.1.3. Superconducting Tapes and Wires
10.2. Analysis, Insights and Forecast - by Material Type
10.2.1. Cuprate Superconductors
10.2.2. Iron-Based Superconductors
10.2.3. Magnesium Diboride Superconductors
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Medical Imaging
10.3.2. Power Transmission
10.3.3. Magnetic Resonance Imaging
10.3.4. Particle Accelerators
10.3.5. Fusion Energy
10.4. Analysis, Insights and Forecast - by End-Use Industry
10.4.1. Healthcare
10.4.2. Energy and Power
10.4.3. Transportation
10.4.4. Manufacturing
10.4.5. Electronics and Quantum Technology
11. Superconductors Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Superconductors Market Research Methodology
List of Figures
Figure 1: Superconductors Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Superconductors Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Superconductors Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Superconductors Market Revenue (Billion), by Material Type 2026 & 2034
Figure 5: North America Superconductors Market Revenue Share (%), by Material Type 2026 & 2034
Figure 6: North America Superconductors Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Superconductors Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Superconductors Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 9: North America Superconductors Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 10: North America Superconductors Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Superconductors Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Superconductors Market Revenue (Billion), by Type 2026 & 2034
Figure 13: Europe Superconductors Market Revenue Share (%), by Type 2026 & 2034
Figure 14: Europe Superconductors Market Revenue (Billion), by Material Type 2026 & 2034
Figure 15: Europe Superconductors Market Revenue Share (%), by Material Type 2026 & 2034
Figure 16: Europe Superconductors Market Revenue (Billion), by Application 2026 & 2034
Europe Superconductors Market Revenue Share (%), by Application 2026 & 2034
List of Tables
Table 1: Superconductors Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Superconductors Market Revenue Billion Forecast, by Material Type 2020 & 2034
Table 14: Europe Superconductors Market Revenue Billion Forecast, by Type 2020 & 2034
Table 15: Europe Superconductors Market Revenue Billion Forecast, by Material Type 2020 & 2034
Table 16: Europe Superconductors Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the superconductors market in 2025?
The global superconductor market was valued at approximately USD 8.7 Billion in 2025 under the broadest conductor-and-magnet definition. Narrower merchant-conductor-only estimates are materially lower because they exclude captive magnet production inside MRI and accelerator OEMs.
2. What is the superconductors market growth rate?
The most defensible CAGR is 7.49% for 2026–2034, reaching USD 16.9 Billion by 2034. More aggressive estimates of 10.5–11.8% depend on fusion procurement scaling on schedule and on HTS tape capacity expanding faster than currently announced.
3. Which segment dominates the superconductors market?
High-temperature superconductors hold 52.8% of revenue and grow at 9.47% CAGR, while medical imaging remains the largest application at 42.7% of revenue. Cuprate materials lead with 55.7% share, with magnesium diboride the fastest-growing material type.
4. Which region leads the superconductors market?
North America leads with roughly 38–48% of global revenue, concentrated in MRI replacement and defence electronics. Asia-Pacific is the fastest-growing region at 9.27% CAGR, driven by Japanese and Chinese REBCO tape capacity and Korean fusion procurement.
5. Who are the leading superconductors companies?
Bruker, Fujikura, Sumitomo Electric, American Superconductor and Furukawa Electric form the core vendor set, alongside Hyper Tech Research, Shanghai Superconductor and Faraday Factory Japan. Competition is shifting toward locked multi-year offtake and long-length tape yield.
6. What is holding back superconductors adoption?
Cryogenic operating cost and complexity remain the primary restraint, alongside long qualification cycles and inconsistent long-length REBCO tape yield. These factors keep superconducting cables uncompetitive with conventional conductors outside space-constrained urban corridors.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis follows a 70/30 primary-to-secondary research split. Between Q3 2025 and Q1 2026 we conducted structured in-depth interviews across the superconductor value chain, including rare-earth and niobium raw material suppliers, REBCO and Nb3Sn conductor producers, magnet and cryostat integrators, and global distributors serving MRI and fusion OEMs. Interviews targeted decision-makers including VP-level Sourcing leads, Heads of R&D, Technical Directors and Commercial Operations Leads, with each respondent screened for direct procurement or specification authority.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
35%
Commercial Operations Leads
20%
Regulatory & Quality Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Rare-Earth Suppliers
30%
Conductor & Tape Producers
40%
Magnet & Cryostat Integrators
20%
Distributors & Trading Houses
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases covering HTS and LTS conductor processing, and technical standards published by recognised non-profit bodies including ISO, IEC and the IEEE Council on Superconductivity. Trade flow data is used to reconcile reported conductor shipments against declared end-use consumption by region.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic and end-industry output to superconductor content per application, while the bottom-up model builds from manufacturer capacity, product pricing and end-use consumption. Divergence between the two is resolved through capacity-utilisation and pricing checks before a central case is set.


 Superconductors Market