Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Next Generation Data Center Market Outlook 2026
Next Generation Data Center Market
Next Generation Data Center Market Outlook 2026
Next Generation Data Center Market by Component (Hardware, Software, Services), by Type (Hyperscale, Colocation, Edge, On-premise), by Server Rack Density (Below 10 kW, 10–19 kW, 20–49 kW, 50+ kW), by Redundancy (N, N+1, 2N, 2N+1), by PUE (Below 1.3, 1.3–1.6, Above 1.6), by Design (Traditional, Modular, Containerized), by Tier Level (Tier I, Tier II, Tier III, Tier IV), by Enterprise Size (Large Enterprises, SMEs), by End Use (BFSI, IT & Telecom, Government, Energy & Utilities, Healthcare, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Ireland, Netherlands, Nordics), by Asia Pacific (China, Japan, India, South Korea, Australia, Singapore), by Latin America (Brazil, Mexico, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 0
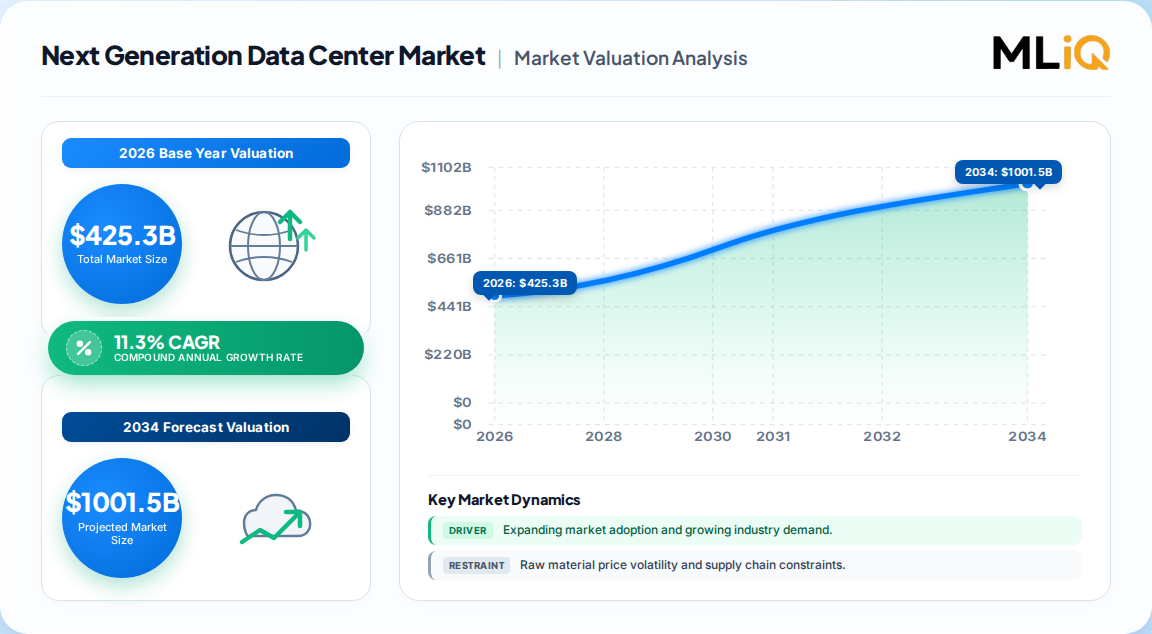
425.3 Billion — the global Next Generation Data Center Market value projected for 2026, up from 383.8 Billion in 2025.
902.2 Billion — the forecast for 2033, implying an 11.3% CAGR across the 2026–2033 window; a competing analysis puts 2035 at 1,103.7 Billion on 11.06%.
Hardware remains the largest component block at roughly 67% of 2025 revenue, but services and software grow faster as operators optimize AI-era facilities.
North America leads with 38–41% revenue share; Asia Pacific is the fastest-growing region, with 12% capacity CAGR to 2030.
Hyperscale and colocation are the fastest-growing facility types; on-premise capacity is projected to decline about 6% as enterprises migrate.
Key players include hyperscalers (AWS, Microsoft Azure, Google Cloud, Alibaba Cloud), colocation leaders (Equinix, Digital Realty), and infrastructure vendors (Schneider Electric, Vertiv, Eaton, Siemens).
Why this matters for decision-makers: Power availability, not land or capital, is now the binding constraint — site selection and energy procurement strategy must precede facility design, or projects will stall in interconnection queues.
Next Generation Data Center Market Size (In Billion)
750.0B
600.0B
450.0B
300.0B
150.0B
0
383.8 B
2025
425.3 B
2026
473.4 B
2027
526.9 B
2028
586.4 B
2029
652.7 B
2030
726.4 B
2031
Next Generation Data Center Market Size (In Billion)
Year
Market Size
2025
383.8 B
2026
425.3 B
2027
473.4 B
2028
526.9 B
2029
586.4 B
2030
652.7 B
2031
726.4 B
What is the Next Generation Data Center Market?
The Next Generation Data Center Market covers facilities and infrastructure engineered for AI, cloud and edge workloads — spanning high-density racks, liquid cooling, modular power, AI-driven management software, and colocation or hyperscale capacity. It replaces legacy enterprise build-outs with scalable, energy-efficient designs optimized for accelerated computing.
Scope: what this report covers and excludes
This analysis covers global data center capacity, components (hardware, software, services), facility types (hyperscale, colocation, edge, on-premise), rack density bands, redundancy and PUE tiers, design and tier levels, enterprise size, and end-use verticals. This analysis does not cover pure semiconductor fabrication, consumer electronics, telecom network equipment outside the facility, or commercial real estate unrelated to data center use.
How big is the market for Next Generation Data Center Market?
Published estimates converge tightly on a low-double-digit CAGR, though base-year values and horizon endpoints differ by definition and scope. The table below compares the leading figures and what each actually measures.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
383.8 Billion
2025
2033 (902.2B)
11.3%
Broad data center market incl. hardware, software, services
One published estimate
430.18 Billion
2026
2035 (1,103.7B)
11.06%
Data center solutions and services across colocation, hyperscale, edge
A competing analysis
~14% capacity CAGR
2025
2030 (200 GW)
14%
Capacity (GW) and construction value, not revenue
Industry real-estate research
Our analysis suggests the ~11% revenue CAGR is the most defensible planning anchor, while the 14% capacity CAGR captures the physical build-out — the gap between them implies falling unit economics per GW as efficiency improves and services revenue lags hardware. Buyers should use 11–12% for budgeting and 14% for power and land planning.
How is the market segmented?
Segmentation spans component, facility type, rack density, redundancy, PUE, design, tier, enterprise size and end use — with AI workloads cutting across every band.
Parent
Children
Component
Hardware, Software, Services
Type
Hyperscale, Colocation, Edge, On-premise
Server Rack Density
Below 10 kW, 10–19 kW, 20–49 kW, 50+ kW
Redundancy
N, N+1, 2N, 2N+1
PUE
Below 1.3, 1.3–1.6, Above 1.6
Design
Traditional, Modular, Containerized
Tier Level
Tier I–IV
Enterprise Size
Large Enterprises, SMEs
End Use
BFSI, IT & Telecom, Government, Energy & Utilities, Healthcare, Others
The 10–19 kW rack band held the largest 2025 share, but 50+ kW AI racks are the fastest-growing band — a shift that invalidates legacy cooling designs and favors liquid-ready builds.
Which region leads in Next Generation Data Center Market?
The Americas lead with roughly half of global capacity, but Asia Pacific is the fastest-growing region and the Middle East is emerging as a sovereign-AI hub.
Next Generation Data Center Market Regional Market Share
Loading chart...
Next Generation Data Center Market Regional Market Share
Region
Market Share (%)
North America
0.4%
Europe
0.22%
Asia-Pacific
0.28%
Latin America
0.05%
Middle East & Africa
0.05%
North America — about 38–41% of revenue; the U.S. alone is ~90% of Americas capacity.
United States, Canada, Mexico
Asia Pacific — 32 GW rising to 57 GW by 2030; 12% capacity CAGR.
China, Japan, India, South Korea, Australia, Singapore
Europe — 10% CAGR, adding ~13 GW; sovereign AI cloud demand.
Germany, UK, France, Ireland, Netherlands, Nordics
Middle East & Africa — emerging, government-backed AI infrastructure.
Saudi Arabia, UAE, South Africa
Latin America — Brazil and Mexico lead early hyperscale entry.
Brazil, Mexico, Argentina, Chile
What is driving growth — and what is holding it back?
Drivers outbalance restraints on a three-to-one basis, but the power constraint is the single most consequential factor in project viability through 2030.
Factor
Direction
Evidence strength
Mechanism
AI and cloud workload expansion
Driver
Strong
AI could be half of workloads by 2030; inference overtakes training by 2027
Hyperscale capacity build-out
Driver
Strong
~100 GW new capacity 2026–2030; ~$3T total spend
Edge and low-latency demand
Driver
Moderate
IoT, autonomous systems, real-time applications
Sustainability and efficiency mandates
Driver
Moderate
PUE targets, renewables procurement, liquid cooling adoption
Grid interconnection delays
Restraint
Strong
Average wait exceeds four years in primary markets
High CapEx and OpEx
Restraint
Strong
Construction cost rising ~7% CAGR; $10.7M/MW in 2025
Skilled labor and supply-chain lead times
Restraint
Moderate
Extended lead times on turbines, transformers, cooling units
Regulatory and permitting friction
Restraint
Moderate
Local zoning, water use, energy rules
The balance favors growth, but operators who cannot secure power face stranded capital. Our analysis suggests "speed to power" has overtaken latency and land cost as the top site-selection criterion — a structural shift that reshuffles regional winners.
Who are the leading vendors?
Competition splits into hyperscalers, colocation providers, and infrastructure vendors, each defending a different moat — capital scale, interconnection density, or thermal and power engineering.
Company
Category
Differentiator / moat
Amazon Web Services
Hyperscaler
Global region breadth, custom silicon, AI services
Microsoft Azure
Hyperscaler
Enterprise integration, OpenAI partnership, sovereign cloud
Google Cloud
Hyperscaler
TPU infrastructure, efficiency leadership, data analytics
Alibaba Cloud
Hyperscaler
China and APAC dominance, regional sovereign cloud
Equinix
Colocation
Interconnection density, global IBX footprint
Digital Realty
Colocation
Hyperscale leasing, power-secured campuses
Schneider Electric
Infrastructure
Power distribution, cooling, modular data center systems
Hyperscalers are executing a dual lease-and-self-build strategy, compressing margins for pure colocation resellers. Infrastructure vendors with liquid-cooling and high-density power portfolios are best positioned as AI rack densities cross 50 kW.
What do buyers and operators need to know? (Decision Support)
Selection criteria now prioritize power availability, liquid-cooling readiness, and grid-interconnection timelines ahead of latency and land cost. Buyers should require evidence of secured power contracts, not just lease terms, since interconnection queues exceed four years in primary markets. Procurement risk centers on long lead times for transformers, turbines and cooling units, and on vendors' ability to scale from 10–19 kW to 50+ kW racks without redesign.
Switching costs are high once a facility is built around a fixed cooling and power architecture; modular designs lower this risk by allowing phased deployment. Regulatory compliance spans local energy and water rules, data-sovereignty requirements in EMEA and APAC, and emerging grid-connection guidelines for co-located AI loads in the U.S. Buyers should also stress-test PUE and redundancy assumptions under AI inference loads, which differ materially from training clusters. Finally, contract structures are shifting toward power-backed SLAs and bring-your-own-power arrangements in markets like Ireland and Texas.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a structural expansion thesis: ~100 GW of new capacity by 2030 and an 11–12% revenue CAGR are supported by multiple independent sources, making a contraction scenario unlikely absent a macro shock. The strongest counter-argument is that power constraints, not demand, cap growth — interconnection delays and 7% construction-cost inflation could push effective capacity additions below headline forecasts. Our analysis suggests headline CAGRs slightly overstate deliverable revenue if grid bottlenecks persist.
For buyers, the implication is that energy strategy is now core to data center strategy. Operators should lock in power before committing to design, favor liquid-ready modular builds, and diversify across regions where "bring your own power" frameworks exist. Vendors should prioritize high-density thermal and power portfolios to capture the 50+ kW rack migration.
Actionable strategy:
Secure power contracts and grid interconnection before finalizing site or design commitments.
Design for 50+ kW rack densities and liquid cooling from day one to avoid costly retrofits.
Diversify regional exposure toward APAC and Middle East growth corridors to offset North America grid risk.
What would change our conclusion: a sustained slowdown in AI inference adoption after 2027, or a step-change in grid capacity that removes the power bottleneck, either of which would shift the forecast materially.
Next Generation Data Center Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Next Generation Data Center Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.3% from 2020-2034
Segmentation
By Component
Hardware
Software
Services
By Type
Hyperscale
Colocation
Edge
On-premise
By Server Rack Density
Below 10 kW
10–19 kW
20–49 kW
50+ kW
By Redundancy
N
N+1
2N
2N+1
By PUE
Below 1.3
1.3–1.6
Above 1.6
By Design
Traditional
Modular
Containerized
By Tier Level
Tier I
Tier II
Tier III
Tier IV
By Enterprise Size
Large Enterprises
SMEs
By End Use
BFSI
IT & Telecom
Government
Energy & Utilities
Healthcare
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Ireland
Netherlands
Nordics
Asia Pacific
China
Japan
India
South Korea
Australia
Singapore
Latin America
Brazil
Mexico
Argentina
Chile
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Next Generation Data Center Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Next Generation Data Center Market Executive Summary
2.1. Market Snapshot
3. Next Generation Data Center Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Next Generation Data Center Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Next Generation Data Center Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Component
5.1.1. Hardware
5.1.2. Software
5.1.3. Services
5.2. Analysis, Insights and Forecast - by Type
5.2.1. Hyperscale
5.2.2. Colocation
5.2.3. Edge
5.2.4. On-premise
5.3. Analysis, Insights and Forecast - by Server Rack Density
5.3.1. Below 10 kW
5.3.2. 10–19 kW
5.3.3. 20–49 kW
5.3.4. 50+ kW
5.4. Analysis, Insights and Forecast - by Redundancy
5.4.1. N
5.4.2. N+1
5.4.3. 2N
5.4.4. 2N+1
5.5. Analysis, Insights and Forecast - by PUE
5.5.1. Below 1.3
5.5.2. 1.3–1.6
5.5.3. Above 1.6
5.6. Analysis, Insights and Forecast - by Design
5.6.1. Traditional
5.6.2. Modular
5.6.3. Containerized
5.7. Analysis, Insights and Forecast - by Tier Level
5.7.1. Tier I
5.7.2. Tier II
5.7.3. Tier III
5.7.4. Tier IV
5.8. Analysis, Insights and Forecast - by Enterprise Size
5.8.1. Large Enterprises
5.8.2. SMEs
5.9. Analysis, Insights and Forecast - by End Use
5.9.1. BFSI
5.9.2. IT & Telecom
5.9.3. Government
5.9.4. Energy & Utilities
5.9.5. Healthcare
5.9.6. Others
5.10. Analysis, Insights and Forecast - by Region
5.10.1. North America
5.10.2. Europe
5.10.3. Asia Pacific
5.10.4. Latin America
5.10.5. Middle East & Africa
6. Next Generation Data Center Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Component
6.1.1. Hardware
6.1.2. Software
6.1.3. Services
6.2. Analysis, Insights and Forecast - by Type
6.2.1. Hyperscale
6.2.2. Colocation
6.2.3. Edge
6.2.4. On-premise
6.3. Analysis, Insights and Forecast - by Server Rack Density
6.3.1. Below 10 kW
6.3.2. 10–19 kW
6.3.3. 20–49 kW
6.3.4. 50+ kW
6.4. Analysis, Insights and Forecast - by Redundancy
6.4.1. N
6.4.2. N+1
6.4.3. 2N
6.4.4. 2N+1
6.5. Analysis, Insights and Forecast - by PUE
6.5.1. Below 1.3
6.5.2. 1.3–1.6
6.5.3. Above 1.6
6.6. Analysis, Insights and Forecast - by Design
6.6.1. Traditional
6.6.2. Modular
6.6.3. Containerized
6.7. Analysis, Insights and Forecast - by Tier Level
6.7.1. Tier I
6.7.2. Tier II
6.7.3. Tier III
6.7.4. Tier IV
6.8. Analysis, Insights and Forecast - by Enterprise Size
6.8.1. Large Enterprises
6.8.2. SMEs
6.9. Analysis, Insights and Forecast - by End Use
6.9.1. BFSI
6.9.2. IT & Telecom
6.9.3. Government
6.9.4. Energy & Utilities
6.9.5. Healthcare
6.9.6. Others
7. Next Generation Data Center Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Component
7.1.1. Hardware
7.1.2. Software
7.1.3. Services
7.2. Analysis, Insights and Forecast - by Type
7.2.1. Hyperscale
7.2.2. Colocation
7.2.3. Edge
7.2.4. On-premise
7.3. Analysis, Insights and Forecast - by Server Rack Density
7.3.1. Below 10 kW
7.3.2. 10–19 kW
7.3.3. 20–49 kW
7.3.4. 50+ kW
7.4. Analysis, Insights and Forecast - by Redundancy
7.4.1. N
7.4.2. N+1
7.4.3. 2N
7.4.4. 2N+1
7.5. Analysis, Insights and Forecast - by PUE
7.5.1. Below 1.3
7.5.2. 1.3–1.6
7.5.3. Above 1.6
7.6. Analysis, Insights and Forecast - by Design
7.6.1. Traditional
7.6.2. Modular
7.6.3. Containerized
7.7. Analysis, Insights and Forecast - by Tier Level
7.7.1. Tier I
7.7.2. Tier II
7.7.3. Tier III
7.7.4. Tier IV
7.8. Analysis, Insights and Forecast - by Enterprise Size
7.8.1. Large Enterprises
7.8.2. SMEs
7.9. Analysis, Insights and Forecast - by End Use
7.9.1. BFSI
7.9.2. IT & Telecom
7.9.3. Government
7.9.4. Energy & Utilities
7.9.5. Healthcare
7.9.6. Others
8. Next Generation Data Center Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Component
8.1.1. Hardware
8.1.2. Software
8.1.3. Services
8.2. Analysis, Insights and Forecast - by Type
8.2.1. Hyperscale
8.2.2. Colocation
8.2.3. Edge
8.2.4. On-premise
8.3. Analysis, Insights and Forecast - by Server Rack Density
8.3.1. Below 10 kW
8.3.2. 10–19 kW
8.3.3. 20–49 kW
8.3.4. 50+ kW
8.4. Analysis, Insights and Forecast - by Redundancy
8.4.1. N
8.4.2. N+1
8.4.3. 2N
8.4.4. 2N+1
8.5. Analysis, Insights and Forecast - by PUE
8.5.1. Below 1.3
8.5.2. 1.3–1.6
8.5.3. Above 1.6
8.6. Analysis, Insights and Forecast - by Design
8.6.1. Traditional
8.6.2. Modular
8.6.3. Containerized
8.7. Analysis, Insights and Forecast - by Tier Level
8.7.1. Tier I
8.7.2. Tier II
8.7.3. Tier III
8.7.4. Tier IV
8.8. Analysis, Insights and Forecast - by Enterprise Size
8.8.1. Large Enterprises
8.8.2. SMEs
8.9. Analysis, Insights and Forecast - by End Use
8.9.1. BFSI
8.9.2. IT & Telecom
8.9.3. Government
8.9.4. Energy & Utilities
8.9.5. Healthcare
8.9.6. Others
9. Next Generation Data Center Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Component
9.1.1. Hardware
9.1.2. Software
9.1.3. Services
9.2. Analysis, Insights and Forecast - by Type
9.2.1. Hyperscale
9.2.2. Colocation
9.2.3. Edge
9.2.4. On-premise
9.3. Analysis, Insights and Forecast - by Server Rack Density
9.3.1. Below 10 kW
9.3.2. 10–19 kW
9.3.3. 20–49 kW
9.3.4. 50+ kW
9.4. Analysis, Insights and Forecast - by Redundancy
9.4.1. N
9.4.2. N+1
9.4.3. 2N
9.4.4. 2N+1
9.5. Analysis, Insights and Forecast - by PUE
9.5.1. Below 1.3
9.5.2. 1.3–1.6
9.5.3. Above 1.6
9.6. Analysis, Insights and Forecast - by Design
9.6.1. Traditional
9.6.2. Modular
9.6.3. Containerized
9.7. Analysis, Insights and Forecast - by Tier Level
9.7.1. Tier I
9.7.2. Tier II
9.7.3. Tier III
9.7.4. Tier IV
9.8. Analysis, Insights and Forecast - by Enterprise Size
9.8.1. Large Enterprises
9.8.2. SMEs
9.9. Analysis, Insights and Forecast - by End Use
9.9.1. BFSI
9.9.2. IT & Telecom
9.9.3. Government
9.9.4. Energy & Utilities
9.9.5. Healthcare
9.9.6. Others
10. Next Generation Data Center Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Component
10.1.1. Hardware
10.1.2. Software
10.1.3. Services
10.2. Analysis, Insights and Forecast - by Type
10.2.1. Hyperscale
10.2.2. Colocation
10.2.3. Edge
10.2.4. On-premise
10.3. Analysis, Insights and Forecast - by Server Rack Density
10.3.1. Below 10 kW
10.3.2. 10–19 kW
10.3.3. 20–49 kW
10.3.4. 50+ kW
10.4. Analysis, Insights and Forecast - by Redundancy
10.4.1. N
10.4.2. N+1
10.4.3. 2N
10.4.4. 2N+1
10.5. Analysis, Insights and Forecast - by PUE
10.5.1. Below 1.3
10.5.2. 1.3–1.6
10.5.3. Above 1.6
10.6. Analysis, Insights and Forecast - by Design
10.6.1. Traditional
10.6.2. Modular
10.6.3. Containerized
10.7. Analysis, Insights and Forecast - by Tier Level
10.7.1. Tier I
10.7.2. Tier II
10.7.3. Tier III
10.7.4. Tier IV
10.8. Analysis, Insights and Forecast - by Enterprise Size
10.8.1. Large Enterprises
10.8.2. SMEs
10.9. Analysis, Insights and Forecast - by End Use
10.9.1. BFSI
10.9.2. IT & Telecom
10.9.3. Government
10.9.4. Energy & Utilities
10.9.5. Healthcare
11. Next Generation Data Center Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Next Generation Data Center Market Research Methodology
List of Figures
Figure 1: Next Generation Data Center Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Next Generation Data Center Market Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Next Generation Data Center Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Next Generation Data Center Market Revenue (Billion), by Type 2026 & 2034
Figure 5: North America Next Generation Data Center Market Revenue Share (%), by Type 2026 & 2034
Figure 6: North America Next Generation Data Center Market Revenue (Billion), by Server Rack Density 2026 & 2034
Figure 7: North America Next Generation Data Center Market Revenue Share (%), by Server Rack Density 2026 & 2034
Figure 8: North America Next Generation Data Center Market Revenue (Billion), by Redundancy 2026 & 2034
Figure 9: North America Next Generation Data Center Market Revenue Share (%), by Redundancy 2026 & 2034
Figure 10: North America Next Generation Data Center Market Revenue (Billion), by PUE 2026 & 2034
Figure 11: North America Next Generation Data Center Market Revenue Share (%), by PUE 2026 & 2034
Figure 12: North America Next Generation Data Center Market Revenue (Billion), by Design 2026 & 2034
Figure 13: North America Next Generation Data Center Market Revenue Share (%), by Design 2026 & 2034
Figure 14: North America Next Generation Data Center Market Revenue (Billion), by Tier Level 2026 & 2034
Figure 15: North America Next Generation Data Center Market Revenue Share (%), by Tier Level 2026 & 2034
North America Next Generation Data Center Market Revenue (Billion), by Enterprise Size 2026 & 2034
List of Tables
Table 1: Next Generation Data Center Market Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Next Generation Data Center Market Revenue Billion Forecast, by Type 2020 & 2034
Table 3: Next Generation Data Center Market Revenue Billion Forecast, by Server Rack Density 2020 & 2034
Table 4: Next Generation Data Center Market Revenue Billion Forecast, by Redundancy 2020 & 2034
Table 5: Next Generation Data Center Market Revenue Billion Forecast, by PUE 2020 & 2034
Table 6: Next Generation Data Center Market Revenue Billion Forecast, by Design 2020 & 2034
Table 7: Next Generation Data Center Market Revenue Billion Forecast, by Tier Level 2020 & 2034
Table 8: Next Generation Data Center Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 9: Next Generation Data Center Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 10: Next Generation Data Center Market Revenue Billion Forecast, by Region 2020 & 2034
Table 11: North America Next Generation Data Center Market Revenue Billion Forecast, by Component 2020 & 2034
Table 12: North America Next Generation Data Center Market Revenue Billion Forecast, by Type 2020 & 2034
Table 13: North America Next Generation Data Center Market Revenue Billion Forecast, by Server Rack Density 2020 & 2034
Table 14: North America Next Generation Data Center Market Revenue Billion Forecast, by Redundancy 2020 & 2034
Table 15: North America Next Generation Data Center Market Revenue Billion Forecast, by PUE 2020 & 2034
North America Next Generation Data Center Market Revenue Billion Forecast, by Design 2020 & 2034
Frequently Asked Questions
1. How big is the Next Generation Data Center Market?
The global market is projected at 425.3 Billion in 2026, rising to 902.2 Billion by 2033 at an 11.3% CAGR, according to one published estimate. A competing analysis puts 2035 at 1,103.7 Billion on 11.06%.
2. Which region leads the Next Generation Data Center Market?
North America leads with roughly 38–41% of global revenue, driven by U.S. hyperscale demand. Asia Pacific is the fastest-growing region, with capacity expanding from 32 GW to 57 GW by 2030.
3. What is driving Next Generation Data Center Market growth?
AI workload expansion, cloud migration, hyperscale build-out and edge computing are the primary drivers. AI could represent half of all data center workloads by 2030, with inference overtaking training around 2027.
4. What is the biggest constraint on data center growth?
Power availability is the binding constraint. Average grid interconnection waits exceed four years in primary markets, and construction costs are rising at roughly 7% CAGR, forcing operators toward on-site generation and battery storage.
5. Who are the leading companies in the Next Generation Data Center Market?
Hyperscalers AWS, Microsoft Azure, Google Cloud and Alibaba Cloud lead capacity, alongside colocation providers Equinix and Digital Realty, and infrastructure vendors Schneider Electric, Vertiv, Eaton and Siemens.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the data center value chain, including power and cooling equipment manufacturers, IT infrastructure OEMs, colocation and hyperscale operators, engineering and construction firms, and enterprise end users. Decision-maker designations interviewed included VP-level Facilities and Infrastructure leads, Heads of Data Center Engineering, Procurement and Sourcing Directors, and Commercial Operations Leads responsible for capacity planning and energy contracts.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Facilities & Infrastructure VPs
35%
Data Center Engineering Heads
30%
Procurement & Sourcing Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Power & Cooling Equipment Manufacturers
35%
IT Infrastructure OEMs
30%
Colocation & Hyperscale Operators
25%
Engineering & Construction Firms
10%
Secondary Benchmarking & Public Trade Validation
Findings were cross-validated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K reports from listed operators and equipment vendors, patent databases, and recognized industry standards bodies including Uptime Institute, ASHRAE, ISO/IEC data center standards, and national energy regulators. No third-party market research publisher data was relied upon for primary validation.
Demand Modeling & Market Sizing Triangulation
Market sizing was triangulated through simultaneous top-down allocation from macroeconomic and industry segment data and bottom-up modeling of manufacturer capacity, equipment pricing, and end-use consumption. Capacity (GW) and revenue (USD) models were reconciled to avoid double counting between colocation leases and enterprise self-build.


 Next Generation Data Center Market