Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Robotic Fueling Systems Market 2026: Size, CAGR & Outlook
Robotic Fueling Systems Market 2026: Size, CAGR & Outlook
Robotic Fueling Systems Market
Robotic Fueling Systems Market 2026: Size, CAGR & Outlook
Robotic Fueling Systems Market by Component (Hardware, Software, Services), by Fuel Pumped (Gasoline, Diesel, Natural Gas, Petrochemicals, Other Fuels), by Payload Capacity (Up to 50 kg, 50.01-100 kg, 100.01-150 kg), by End User (Automotive, Aerospace, Construction, Marine and Shipping, Mining, Military and Defense, Oil and Gas, Warehouse and Logistics, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
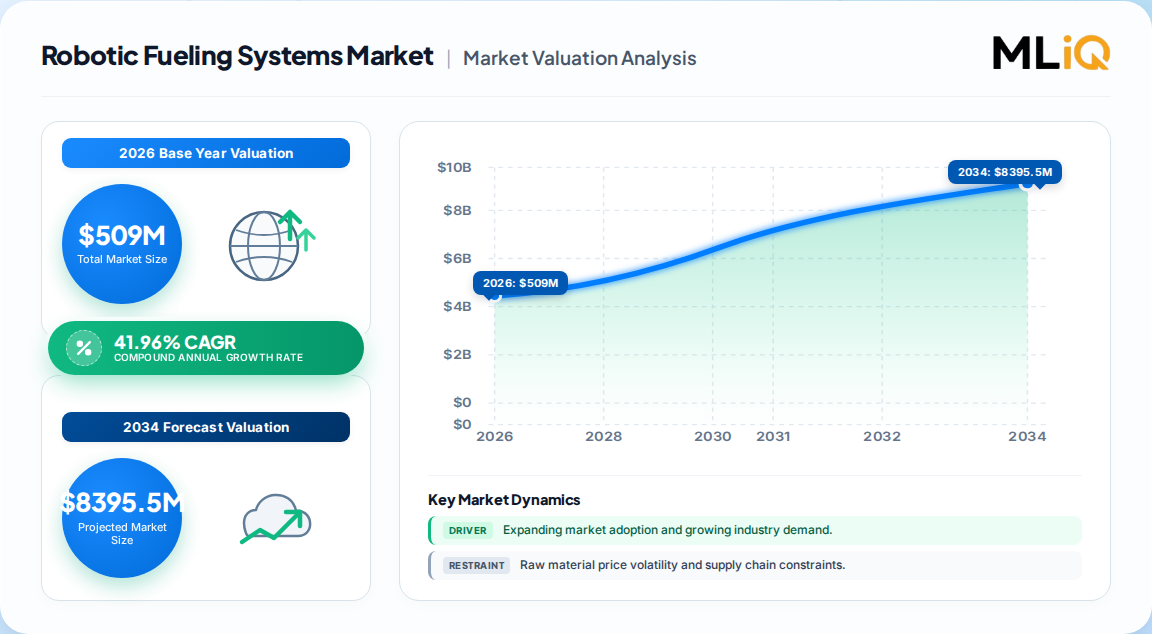
USD 509 million in 2026, within a global robotic fueling systems market expanding at roughly 42% annually — one of the fastest-scaling niches in industrial automation.
Forecasts diverge sharply: 1.95 billion by 2030 in one estimate, 3.02 billion by 2032 in another, and 8.40 billion by 2034 in a third; our analysis favors the mid-path near 3 billion by 2032.
Gasoline is the leading fuel segment at about 32% of 2025 revenue; software is the fastest-growing component at roughly 46% CAGR.
Sub-50 kg payload units dominate with 46% share, reflecting aerospace, defense and depot-scale deployments rather than heavy fleet terminals.
North America holds about 38.5% of global revenue, while Asia Pacific grows fastest at roughly 47% CAGR, led by China and South Korea.
ABB, FANUC, KUKA, Stäubli and Tatsuno anchor the vendor field, with specialists such as Orbit Fab and Fuelmatics serving defense and space niches.
Why this matters for decision-makers: the bottleneck is no longer robotics hardware but certified integration — vendors that pair robotic arms with validated fuel-handling and safety software will capture disproportionately more margin.
Robotic Fueling Systems Market Size (In Million)
3.0B
2.0B
1.0B
0
359.0 M
2025
509.0 M
2026
723.0 M
2027
1.030 B
2028
1.460 B
2029
2.070 B
2030
2.940 B
2031
Robotic Fueling Systems Market Size (In Million)
Year
Market Size
2025
359.0 M
2026
509.0 M
2027
723.0 M
2028
1.030 B
2029
1.460 B
2030
2.070 B
2031
2.940 B
What is the Robotic Fueling Systems Market?
Robotic fueling systems are automated platforms that locate, connect and disengage fuel nozzles without human intervention. Combining articulated arms, machine vision, sensors and control software, they refuel vehicles, aircraft, mining equipment and spacecraft where speed, spill prevention and worker safety are critical.
Scope: what this report covers and excludes
This analysis covers robotic refueling hardware, embedded control software and associated engineering services across gasoline, diesel, natural gas and petrochemical applications, from sub-50 kg depot units through 150 kg heavy-equipment systems. Coverage spans automotive, aerospace, defense, mining, marine, oil and gas, and warehouse logistics end users globally.
This analysis does not cover conventional fuel dispensers, manual nozzle systems, electric-vehicle charging infrastructure, autonomous refueling tanker aircraft boom systems as a standalone category, or industrial robotic arms sold without fueling integration.
How big is the market for Robotic Fueling Systems Market?
One published estimate puts the robotic fueling systems market at USD 509 million in 2026, rising to USD 8.40 billion by 2034 at 41.96% CAGR. A competing analysis shows USD 0.49 billion in 2026 reaching USD 1.95 billion by 2030 at 41.1%, while a third projects USD 3.02 billion by 2032 at 43.4%.
Adds services line; includes diesel as distinct fuel type
A competing analysis
0.24 Billion (2025)
2025
2032
43.4%
Narrower industrial/military framing; includes frequency segmentation
A third published estimate
Our analysis suggests the 2026 base is broadly agreed near USD 0.49–0.51 billion; the divergence is almost entirely in the back-end horizon. The 2034 figure implies a compounding plateau that ignores certification bottlenecks and station retrofit costs. The 2032 mid-path of roughly USD 3 billion is the most defensible planning anchor — and even that assumes defense and autonomous-fleet procurement survives budget cycles.
How is the market segmented?
Segmentation is defined by component, fuel type, payload capacity and end-user vertical. Component splits matter most commercially because software carries the margin and the switching cost.
Parent
Children
By Component
Hardware (robotic arms, dispensing units, sensors and cameras, control systems, connectors and valves, power supply), Software (control, navigation and mapping, safety and monitoring, analytics, integration), Services
By Fuel Pumped
Gasoline, Diesel, Natural Gas, Petrochemicals, Other Fuels
By Payload Capacity
Up to 50 kg, 50.01–100 kg, 100.01–150 kg
By End User
Automotive, Aerospace, Construction, Marine and Shipping, Mining, Military and Defense, Oil and Gas, Warehouse and Logistics, Others
Which region leads the Robotic Fueling Systems Market?
North America led with 38.5% of 2025 revenue, anchored by U.S. defense refueling programs and early autonomous-fleet trials. Asia Pacific is the fastest-growing region at roughly 47% CAGR, with China and South Korea driving mining, marine and port automation demand.
Robotic Fueling Systems Market Regional Market Share
Loading chart...
Robotic Fueling Systems Market Regional Market Share
Region
Market Share (%)
North America
0.39%
Europe
0.2%
Asia-Pacific
0.32%
South America
0.05%
Middle East & Africa
0.05%
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
The implication for buyers is that procurement cycles, not technology readiness, set the regional tempo. North American demand is program-led and slow; Asia Pacific demand is capex-led and faster, which is where vendors should place localization investment.
What is driving growth — and what is holding it back?
Worker-safety mandates and autonomous fleet economics are the two strongest demand drivers, while certification cost and integration complexity are the binding constraints. Growth is real, but it is gated by safety validation rather than by robotics capability.
Factor
Direction
Evidence strength
Mechanism
Rising oil and gas throughput
Driver
Strong
Continuous fuelling cuts downtime in high-volume production
Worker safety and hazard exposure
Driver
Strong
Removes humans from fuel, heat and confined-space risk
Autonomous fleet and defense automation
Driver
Moderate
Enables unattended refueling cycles in controlled environments
Machine vision and sensor cost decline
Driver
Moderate
Improves positioning accuracy and spill prevention
Strict certification and electrical-safety rules
Restraint
Strong
Adds testing, validation and time-to-market cost
High upfront capex and retrofit complexity
Restraint
Strong
Deters smaller station and fleet operators
Who are the leading vendors?
ABB, FANUC, KUKA and Stäubli bring articulated-arm scale and global service networks, while Tatsuno, Fuelmatics, Shaw Development and Orbit Fab own fueling-specific and space/defense niches. The competitive moat is integration certification, not arm manufacturing.
Vendor
Positioning
Differentiation
ABB Limited
Industrial automation leader
Broad arm portfolio, global service footprint
FANUC Corporation
Robotics scale
Reliability and installed-base support
KUKA Aktiengesellschaft
Automotive robotics
Line integration with OEMs
Stäubli International
Precision connectors and robotics
Fluid-connection expertise
Tatsuno Corporation
Fueling equipment specialist
Dispenser and nozzle heritage
Fuelmatics / Shaw Development
Automation specialists
Nozzle-automation and vehicle interface IP
Orbit Fab
Space refueling
In-orbit servicing niche
What do buyers and operators need to know?
Selection should be driven by certified safety architecture, not arm payload alone. Buyers must verify emergency-shutdown behavior, leak detection, ATEX or equivalent hazardous-area ratings, and cybersecurity posture for remote monitoring before committing to a platform.
Switching costs are high once a system is integrated with fleet management and site infrastructure, so specification errors are expensive. Retrofit complexity with legacy dispensers is the single most common deployment risk. Operators should insist on vendor maintenance contracts and validated mean time between failures, because a refueling fault halts the whole operation.
Regulatory variance across countries lengthens approval cycles. Procurement teams should build certification timelines into business cases and favor vendors with existing approvals in the target jurisdiction.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-path forecast: roughly USD 3 billion by 2032, with software and safety certification capturing disproportionate value. The strongest counter-argument is that defense and space programs could accelerate adoption beyond even the 8 billion upper estimate — but those budgets are cyclical and concentrated in few buyers.
Our analysis suggests the market's real constraint is engineering labor: certified integration engineers, not robotic arms, gate deployment. Vendors that build reusable safety architectures and pre-certified software stacks will compress project timelines and win share from general automation incumbents.
Regional divergence reinforces this. North America will reward compliance depth; Asia Pacific will reward cost-optimized, rapid-deployment packages. A single global product strategy will underperform.
Prioritize certified safety-software platforms over arm hardware to protect margin as competition intensifies.
Target Asia Pacific mining, marine and logistics operators for volume, and North American defense for premium contracts.
Underwrite business cases on certification timelines and service contracts, not headline payload specifications.
What would change our conclusion: a major defense refueling program award above USD 500 million, or a standardized international safety certification for automated fueling, either of which would justify the higher forecast path.
Robotic Fueling Systems Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Robotic Fueling Systems Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 41.96% from 2020-2034
Segmentation
By Component
Hardware
Software
Services
By Fuel Pumped
Gasoline
Diesel
Natural Gas
Petrochemicals
Other Fuels
By Payload Capacity
Up to 50 kg
50.01-100 kg
100.01-150 kg
By End User
Automotive
Aerospace
Construction
Marine and Shipping
Mining
Military and Defense
Oil and Gas
Warehouse and Logistics
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Argentina
Mexico
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Robotic Fueling Systems Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Robotic Fueling Systems Market Executive Summary
2.1. Market Snapshot
3. Robotic Fueling Systems Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Robotic Fueling Systems Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Robotic Fueling Systems Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Component
5.1.1. Hardware
5.1.2. Software
5.1.3. Services
5.2. Analysis, Insights and Forecast - by Fuel Pumped
5.2.1. Gasoline
5.2.2. Diesel
5.2.3. Natural Gas
5.2.4. Petrochemicals
5.2.5. Other Fuels
5.3. Analysis, Insights and Forecast - by Payload Capacity
5.3.1. Up to 50 kg
5.3.2. 50.01-100 kg
5.3.3. 100.01-150 kg
5.4. Analysis, Insights and Forecast - by End User
5.4.1. Automotive
5.4.2. Aerospace
5.4.3. Construction
5.4.4. Marine and Shipping
5.4.5. Mining
5.4.6. Military and Defense
5.4.7. Oil and Gas
5.4.8. Warehouse and Logistics
5.4.9. Others
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. Robotic Fueling Systems Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Component
6.1.1. Hardware
6.1.2. Software
6.1.3. Services
6.2. Analysis, Insights and Forecast - by Fuel Pumped
6.2.1. Gasoline
6.2.2. Diesel
6.2.3. Natural Gas
6.2.4. Petrochemicals
6.2.5. Other Fuels
6.3. Analysis, Insights and Forecast - by Payload Capacity
6.3.1. Up to 50 kg
6.3.2. 50.01-100 kg
6.3.3. 100.01-150 kg
6.4. Analysis, Insights and Forecast - by End User
6.4.1. Automotive
6.4.2. Aerospace
6.4.3. Construction
6.4.4. Marine and Shipping
6.4.5. Mining
6.4.6. Military and Defense
6.4.7. Oil and Gas
6.4.8. Warehouse and Logistics
6.4.9. Others
7. Robotic Fueling Systems Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Component
7.1.1. Hardware
7.1.2. Software
7.1.3. Services
7.2. Analysis, Insights and Forecast - by Fuel Pumped
7.2.1. Gasoline
7.2.2. Diesel
7.2.3. Natural Gas
7.2.4. Petrochemicals
7.2.5. Other Fuels
7.3. Analysis, Insights and Forecast - by Payload Capacity
7.3.1. Up to 50 kg
7.3.2. 50.01-100 kg
7.3.3. 100.01-150 kg
7.4. Analysis, Insights and Forecast - by End User
7.4.1. Automotive
7.4.2. Aerospace
7.4.3. Construction
7.4.4. Marine and Shipping
7.4.5. Mining
7.4.6. Military and Defense
7.4.7. Oil and Gas
7.4.8. Warehouse and Logistics
7.4.9. Others
8. Robotic Fueling Systems Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Component
8.1.1. Hardware
8.1.2. Software
8.1.3. Services
8.2. Analysis, Insights and Forecast - by Fuel Pumped
8.2.1. Gasoline
8.2.2. Diesel
8.2.3. Natural Gas
8.2.4. Petrochemicals
8.2.5. Other Fuels
8.3. Analysis, Insights and Forecast - by Payload Capacity
8.3.1. Up to 50 kg
8.3.2. 50.01-100 kg
8.3.3. 100.01-150 kg
8.4. Analysis, Insights and Forecast - by End User
8.4.1. Automotive
8.4.2. Aerospace
8.4.3. Construction
8.4.4. Marine and Shipping
8.4.5. Mining
8.4.6. Military and Defense
8.4.7. Oil and Gas
8.4.8. Warehouse and Logistics
8.4.9. Others
9. Robotic Fueling Systems Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Component
9.1.1. Hardware
9.1.2. Software
9.1.3. Services
9.2. Analysis, Insights and Forecast - by Fuel Pumped
9.2.1. Gasoline
9.2.2. Diesel
9.2.3. Natural Gas
9.2.4. Petrochemicals
9.2.5. Other Fuels
9.3. Analysis, Insights and Forecast - by Payload Capacity
9.3.1. Up to 50 kg
9.3.2. 50.01-100 kg
9.3.3. 100.01-150 kg
9.4. Analysis, Insights and Forecast - by End User
9.4.1. Automotive
9.4.2. Aerospace
9.4.3. Construction
9.4.4. Marine and Shipping
9.4.5. Mining
9.4.6. Military and Defense
9.4.7. Oil and Gas
9.4.8. Warehouse and Logistics
9.4.9. Others
10. Robotic Fueling Systems Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Component
10.1.1. Hardware
10.1.2. Software
10.1.3. Services
10.2. Analysis, Insights and Forecast - by Fuel Pumped
10.2.1. Gasoline
10.2.2. Diesel
10.2.3. Natural Gas
10.2.4. Petrochemicals
10.2.5. Other Fuels
10.3. Analysis, Insights and Forecast - by Payload Capacity
10.3.1. Up to 50 kg
10.3.2. 50.01-100 kg
10.3.3. 100.01-150 kg
10.4. Analysis, Insights and Forecast - by End User
10.4.1. Automotive
10.4.2. Aerospace
10.4.3. Construction
10.4.4. Marine and Shipping
10.4.5. Mining
10.4.6. Military and Defense
10.4.7. Oil and Gas
10.4.8. Warehouse and Logistics
10.4.9. Others
11. Robotic Fueling Systems Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Robotic Fueling Systems Market Research Methodology
List of Figures
Figure 1: Robotic Fueling Systems Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Robotic Fueling Systems Market Revenue (Million), by Component 2026 & 2034
Figure 3: North America Robotic Fueling Systems Market Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Robotic Fueling Systems Market Revenue (Million), by Fuel Pumped 2026 & 2034
Figure 5: North America Robotic Fueling Systems Market Revenue Share (%), by Fuel Pumped 2026 & 2034
Figure 6: North America Robotic Fueling Systems Market Revenue (Million), by Payload Capacity 2026 & 2034
Figure 7: North America Robotic Fueling Systems Market Revenue Share (%), by Payload Capacity 2026 & 2034
Figure 8: North America Robotic Fueling Systems Market Revenue (Million), by End User 2026 & 2034
Figure 9: North America Robotic Fueling Systems Market Revenue Share (%), by End User 2026 & 2034
Figure 10: North America Robotic Fueling Systems Market Revenue (Million), by Country 2026 & 2034
Figure 11: North America Robotic Fueling Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Robotic Fueling Systems Market Revenue (Million), by Component 2026 & 2034
Figure 13: Europe Robotic Fueling Systems Market Revenue Share (%), by Component 2026 & 2034
Figure 14: Europe Robotic Fueling Systems Market Revenue (Million), by Fuel Pumped 2026 & 2034
Figure 15: Europe Robotic Fueling Systems Market Revenue Share (%), by Fuel Pumped 2026 & 2034
Figure 16: Europe Robotic Fueling Systems Market Revenue (Million), by Payload Capacity 2026 & 2034
List of Tables
Table 1: Robotic Fueling Systems Market Revenue Million Forecast, by Component 2020 & 2034
Table 2: Robotic Fueling Systems Market Revenue Million Forecast, by Fuel Pumped 2020 & 2034
Table 3: Robotic Fueling Systems Market Revenue Million Forecast, by Payload Capacity 2020 & 2034
Table 4: Robotic Fueling Systems Market Revenue Million Forecast, by End User 2020 & 2034
Table 5: Robotic Fueling Systems Market Revenue Million Forecast, by Region 2020 & 2034
Table 6: North America Robotic Fueling Systems Market Revenue Million Forecast, by Component 2020 & 2034
Table 7: North America Robotic Fueling Systems Market Revenue Million Forecast, by Fuel Pumped 2020 & 2034
Table 8: North America Robotic Fueling Systems Market Revenue Million Forecast, by Payload Capacity 2020 & 2034
Table 9: North America Robotic Fueling Systems Market Revenue Million Forecast, by End User 2020 & 2034
Table 10: North America Robotic Fueling Systems Market Revenue Million Forecast, by Country 2020 & 2034
Table 11: USA Robotic Fueling Systems Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 12: Canada Robotic Fueling Systems Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 13: Mexico Robotic Fueling Systems Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: Europe Robotic Fueling Systems Market Revenue Million Forecast, by Component 2020 & 2034
Table 15: Europe Robotic Fueling Systems Market Revenue Million Forecast, by Fuel Pumped 2020 & 2034
Europe Robotic Fueling Systems Market Revenue Million Forecast, by Payload Capacity 2020 & 2034
Frequently Asked Questions
1. How big is the robotic fueling systems market in 2026?
The market is approximately USD 509 million in 2026, up from roughly USD 359 million in 2025. Forecasts converge on the base year and diverge mainly on the long-term horizon and scope of services included.
2. What is the robotic fueling systems market growth rate?
Published estimates cluster between 41% and 43.4% CAGR through the early 2030s. Our analysis treats roughly 41–42% as the defensible planning rate, reflecting certification bottlenecks rather than hardware limits.
3. Which region dominates robotic refueling adoption?
North America held about 38.5% of 2025 revenue, driven by U.S. defense and autonomous-vehicle programs. Asia Pacific is the fastest-growing region at roughly 47% CAGR, led by China and South Korea.
4. Who are the leading robotic fueling system vendors?
ABB, FANUC, KUKA and Stäubli lead on robotics scale and service networks. Tatsuno, Fuelmatics, Shaw Development and Orbit Fab hold fueling-specific, defense and space niches with proprietary integration IP.
5. What restrains robotic fueling system adoption?
Strict safety certification, hazardous-area compliance and high upfront capex slow deployment. Retrofit complexity with legacy dispensers and limited certified integration engineers are the most common operational blockers.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including robotic arm and connector suppliers, fuel-dispensing equipment producers, system integrators, and global distributors serving defense and industrial fleets. Interviewees included VP-level sourcing executives, heads of automation R&D, technical directors responsible for hazardous-area compliance, and commercial operations leads at fueling-equipment OEMs.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Automation & R&D Directors
38%
Procurement & Sourcing Leads
32%
Safety & Compliance Managers
30%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Robotics & Arm Manufacturers
35%
Fueling Equipment Producers
30%
System Integrators
22%
Distributors & Service Providers
13%
Secondary Benchmarking & Public Trade Validation
Estimates were cross-checked against UN Comtrade and US ITC trade flows for industrial robots and dispensing equipment, Eurostat industrial automation data, corporate 10-K and annual investor filings from robotics and fueling-equipment vendors, patent databases covering nozzle-automation and machine-vision docking, and recognized technical standards bodies governing fueling safety and hazardous-area equipment.
Demand Modeling & Market Sizing Triangulation
We triangulate top-down macroeconomic and end-user segment allocation against bottom-up manufacturer capacity, unit pricing, and end-use consumption modeling. Where published estimates diverge, we reconcile by normalizing scope definitions — particularly services inclusion and horizon length — before projecting.


 Robotic Fueling Systems Market