 Fly-By-Wire System Market
: Size, Share & 2033 Forecast
Updated On : Nov 18, 2026|Base Year : 2025

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Fly-By-Wire System Market

Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 8.900 B |
| 2026 | 9.800 B |
| 2027 | 10.70 B |
| 2028 | 11.60 B |
| 2029 | 12.70 B |
| 2030 | 13.80 B |
| 2031 | 15.10 B |

The Fly-By-Wire System Market covers electronic flight-control architectures that replace mechanical and hydraulic linkages with computers, sensors, actuators and cockpit controls, converting pilot and autopilot inputs into digital commands. It spans digital and analog systems across commercial, military and business aviation, including line-fit and retrofit installations.
This analysis covers the global Fly-By-Wire System Market across technology (digital, analog), component (flight control computers, actuators, cockpit controls, sensors), application (commercial, military, business aviation) and all major regions, with line-fit and retrofit demand assessed separately. This analysis does not cover full hydraulic actuation-only systems, satellite avionics, or cabin electronics outside the flight-control loop.
Estimates diverge sharply because some sources size fly-by-wire narrowly (electronic flight-control architecture only) while others fold it into the broader aircraft flight control system market. That definitional gap explains most of the spread below.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 8.9 Billion → 17.9 Billion | 2025 | 2033 | 9.0% | Fly-by-wire systems only (digital + analog) | One published market analysis (2026 edition) |
| 17.94 Billion → 26.80 Billion | 2025 | 2030 | 8.36% | Entire aircraft flight control systems market, FBW as one technology | A competing analysis (Mordor-style framing) |
| 28.9 Billion → 47.4 Billion | 2023 | 2033 | 5.07% | Full flight control system incl. control surfaces and mechanisms | A separate published forecast |
| 66.56% FBW share of FCS | 2024 | 2030 | — | FBW share within broader flight-control spend | Cross-referenced benchmark |
Our analysis suggests the 8.9 Billion base is the most defensible reading of the pure fly-by-wire category, because it excludes control surfaces and mechanism hardware that inflate the broader FCS figures. The 9.0% CAGR also aligns with a 66.56% FBW share inside an ~8.4% growing parent market — a coherence check the faster, narrower estimate passes and the slower 5.07% figure does not.
Segmentation is technology-led: digital architectures capture the overwhelming majority of value, while component and application splits reveal where growth is concentrating.
| Parent segment | Children |
|---|---|
| Technology | Digital, Analog |
| Component | Flight Control Computers, Actuators, Cockpit Controls, Sensors |
| Application | Commercial Aviation, Military Aviation, Business Aviation |
| Fit | Line-Fit, Retrofit |
The practical implication: digital plus flight-computer spend is the profit pool today, but sensors and retrofit are where incremental share shifts will occur through 2033.
North America leads the Fly-By-Wire System Market with roughly 37% of 2025 revenue, anchored by Boeing, Lockheed Martin, defense procurement and dense tier-one supplier networks; Asia Pacific is the fastest-growing region.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.24% |
| Asia-Pacific | 0.26% |
| South America | 0.06% |
| Middle East & Africa | 0.07% |
This divergence implies that capacity investment should follow Asia Pacific volume growth, while margin capture remains concentrated where certification authority and OEM relationships sit — namely North America and Europe.
Growth is driven by weight and fuel-efficiency mandates plus aircraft production recovery; restraint comes from certification cost and supply-chain fragility rather than lack of demand.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Fuel-efficiency and lightweighting mandates | Driver | High | Electronic interfaces cut weight and fuel burn versus hydromechanical linkages |
| Commercial aircraft production recovery | Driver | High | ~44,000 deliveries projected through 2043; ~71% single-aisle |
| Military fleet modernization | Driver | High | Quad-redundant architectures and cyber-hardened computers |
| Power-by-wire / MEA transition | Driver | Medium-High | 15–20% system weight reduction; new certification pathways |
| Certification cost and time | Restraint | High | Novel architectures can add USD 100M+ and years to programs |
| Precision component shortages | Restraint | Medium | ~66% of aerospace firms report parts delays |
| Cybersecurity exposure | Restraint | Medium | Networked architectures raise attack surface and validation burden |
The balance favors growth: drivers are structural and multi-year, while restraints are cost-and-time frictions that disproportionately hit new entrants rather than incumbents. Our analysis suggests certification burden is effectively a moat, consolidating share toward established integrators.
Competition is concentrated among a handful of tier-one aerospace integrators with in-house certification depth, redundancy expertise and OEM program positions.
| Vendor | Core strength | Notable positioning |
|---|---|---|
| Honeywell International | Flight control computers, actuation | Broad FBW portfolio, dual-lane fault-tolerant architecture |
| Collins Aerospace (RTX) | Integrated flight controls, power and cooling | Enhanced Power and Cooling System at TRL 6 in 2025 |
| Safran Electronics & Defense | Actuation, flight control electronics | Electromechanical actuation unit being divested to Woodward |
| Thales | Flight control computers, avionics | Strong European OEM relationships |
| BAE Systems | Military flight-control computers | F-15EX and F/A-18E/F upgrade contracts |
| Moog Inc. | Actuators and servo systems | High-precision actuation specialist |
| Parker Hannifin | Hydraulic and electro-mechanical actuation | Broad motion-control footprint |
| Liebherr-Aerospace | Electro-mechanical actuators | Integrated EMAs for eVTOL platforms |
Differentiation rests on certified redundancy architecture, cyber-hardening and thermal headroom for high-voltage actuation rather than unit price. The Woodward–Safran actuation transaction signals that electric-flight expertise is being bought, not built — a second-order effect that will squeeze sub-scale actuation suppliers out of prime positions.
Selection criteria now hinge on certified architecture maturity, not catalogue specifications. Buyers should demand documented redundancy levels, DO-178C/DO-254-style software and hardware assurance evidence, and a clear power-by-wire migration path, because re-qualifying a flight-control computer mid-program is prohibitively expensive.
Procurement risk concentrates in three areas: precision servo valve and aerospace-grade electronics lead times, cybersecurity validation of networked architectures, and bespoke certification conditions for novel designs. Switching costs are high — typically multi-year re-certification plus pilot-training and maintenance-program changes — so incumbency is sticky and retrofit decisions should be modeled over the full lifecycle, not acquisition price.
Regulatory compliance is the gating factor. FAA system-safety rulemaking on electric-flight risks and special conditions for new aircraft types mean buyers should verify the supplier's certification record on comparable architectures before committing. Operators retrofitting legacy fleets should weigh analog upgrades where mission profiles tolerate them; our analysis suggests the analog CAGR of roughly 2.5% understates its retrofit value in cost-sensitive regional markets.
The balance of evidence favors a digital-led, certification-gated expansion story: roughly 9% CAGR to 2033, concentrated in flight-control computers and sensors, with Asia Pacific supplying volume and North America supplying margin. The strongest counter-argument is that power-by-wire and autonomy could compress the value of conventional FBW computers faster than forecast — but certification timelines make that a post-2030 risk, not a near-term one.
For decision-makers, three moves stand out:
What would change this conclusion: a step-change in certification efficiency for novel architectures, or accelerated eVTOL/UAM volume that shifts demand from conventional FBW toward compact dual-lane systems. Absent either, the incumbent-weighted forecast holds. Precise sub-segment forecasting by component and region requires the full report's bottom-up model, which this overview deliberately does not substitute for.
This study applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the value chain — flight-control computer and avionics suppliers, actuation and sensor specialists, airframe integrators, and maintenance/retrofit providers — targeting VP-level sourcing, heads of flight-control engineering, certification directors, and commercial operations leads. Interviews validated architecture adoption timelines, qualification bottlenecks, and pricing structures.
We triangulated corporate annual filings (10-K, SEC filings, investor presentations), aerospace trade statistics from UN Comtrade and US ITC, patent filings, and standards documentation from SAE International, RTCA and FAA/EASA rulemaking. These sources anchored installed-base estimates and component pricing.
Top-down macroeconomic and aircraft-delivery allocation was run simultaneously with bottom-up supplier capacity, unit pricing and end-use consumption modeling. Divergences between the two were reconciled against certification and delivery schedules.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.0% from 2020-2034 |
| Segmentation |
|
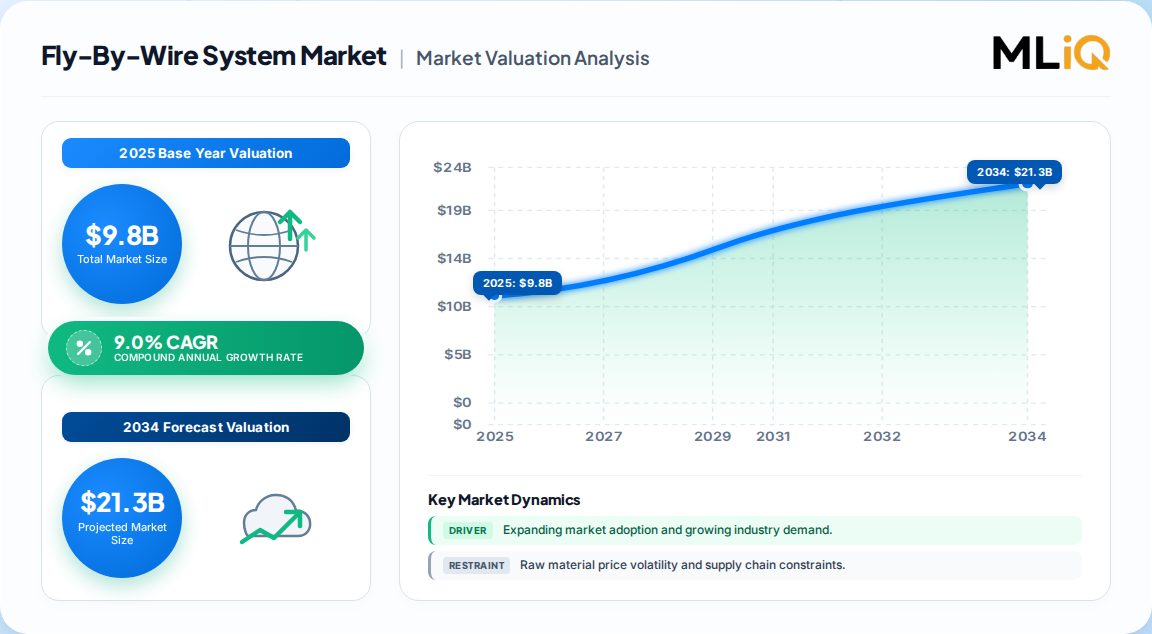
The global Fly-By-Wire System Market was valued at 8.9 Billion in 2025 and is estimated at 9.8 Billion in 2026. One published analysis projects 17.9 Billion by 2033, reflecting a 9.0% CAGR across the forecast period.
The market is forecast to grow at a 9.0% CAGR from 2026 to 2033. Growth is underpinned by aircraft production recovery, fuel-efficiency mandates, military modernization and the shift toward more-electric aircraft architectures.
North America led with roughly 37% of 2025 revenue, supported by major OEMs, defense spending and dense supplier networks. Asia Pacific is the fastest-growing region as narrowbody fleets and domestic aerospace capacity expand.
Digital fly-by-wire held about 87% of 2025 revenue, and flight control computers were the largest component segment. Sensors are the fastest-growing component, driven by autonomy and sensor-fusion requirements.
Leading suppliers include Honeywell, Collins Aerospace, Safran Electronics & Defense, Thales, BAE Systems, Moog, Parker Hannifin and Liebherr-Aerospace. Competition hinges on certified redundancy architecture and cyber-hardened flight-control computers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the fly-by-wire value chain — flight-control computer and avionics suppliers, actuation and sensor specialists, airframe integrators, and maintenance/retrofit providers — targeting VP-level sourcing, heads of flight-control engineering, certification directors, and commercial operations leads. Interviews validated architecture adoption timelines, qualification bottlenecks, and pricing structures.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| Flight-Control Engineering Heads | 30% |
| Certification & Regulatory Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Flight-Control Computer & Avionics Suppliers | 40% |
| Actuation & Sensor Specialists | 30% |
| Airframe Integrators & OEMs | 20% |
| Maintenance, Retrofit & Certification Providers | 10% |
We triangulated corporate annual filings (10-K, SEC filings, investor presentations), aerospace trade statistics from UN Comtrade and US ITC, Eurostat, patent filings, and standards documentation from SAE International, RTCA and FAA/EASA rulemaking. These sources anchored installed-base estimates, component pricing and regional demand distribution.
Top-down macroeconomic and aircraft-delivery allocation was run simultaneously with bottom-up supplier capacity, unit pricing and end-use consumption modeling. Divergences between the two were reconciled against certification and delivery schedules to produce a single reconciled forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |