 Smart Plugs and Switches Market
 2025: Size, CAGR & Trends
Updated On : Nov 18, 2026

Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.

+1 2315155523
 Smart Plugs and Switches Market

Srinwanti Kar
Senior Research Analyst

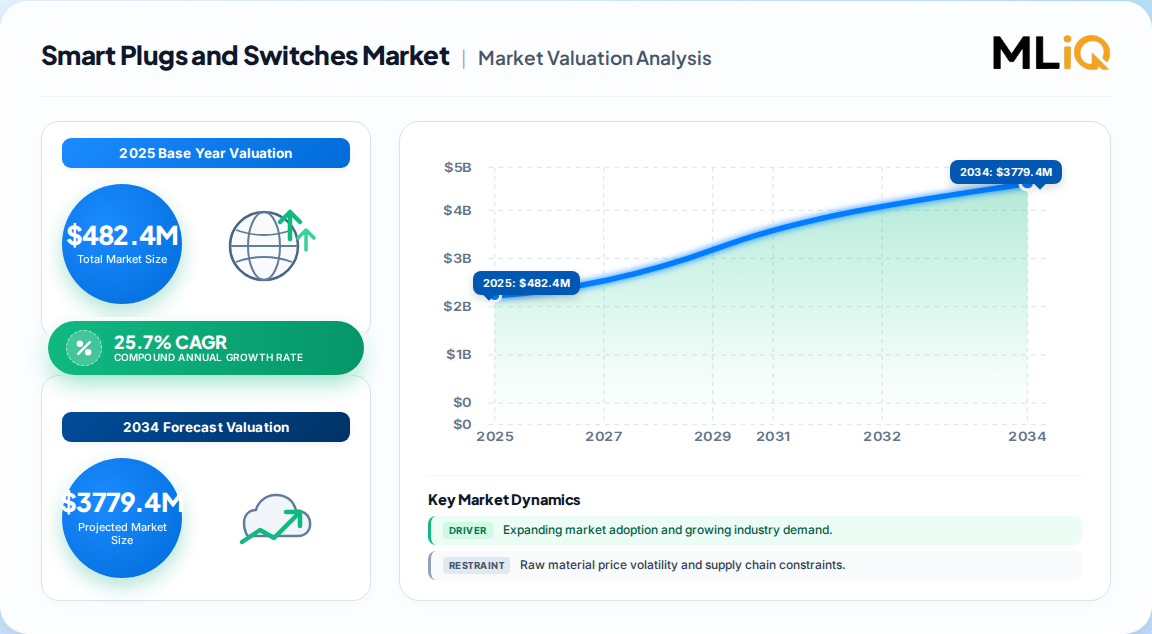
| Year | Market Size |
|---|---|
| 2025 | 482.0 M |
| 2026 | 606.0 M |
| 2027 | 762.0 M |
| 2028 | 958.0 M |
| 2029 | 1.200 B |
| 2030 | 1.510 B |
| 2031 | 1.900 B |

The Smart Plugs and Switches Market covers connected electrical devices that enable remote, scheduled, voice-controlled, or sensor-triggered switching of plug loads and lighting circuits. It spans wall-plug adapters, in-wall outlets, and modular switches used in residential, commercial, and light-industrial settings, increasingly bundled with energy monitoring and interoperability standards such as Matter.
This report covers global smart plugs (wall-plug adapters, in-wall outlets, smart power strips) and smart switches (touch, dimmer, modular, sensor-linked) across residential, commercial, and light-industrial end-uses. Connectivity types include Wi-Fi, Bluetooth, Zigbee, Z-Wave, and Thread. This analysis does not cover conventional non-connected wiring devices, whole-home building management systems, smart lighting fixtures, or smart meters.
The market size depends heavily on whether plug-only or combined plug-and-switch definitions are used, and on whether value is counted at manufacturer, brand, or retail level. The table below reconciles the most-cited published estimates.
| Estimate (Base Year) | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|
| 482.4M (2025) | 2031 | 25.7% | Combined smart plugs + smart switches, manufacturer value | Aggregated industry benchmark |
| 5.29B (2026) | 2031 | 25.7% | Smart plugs only, retail-value anchored | One published estimate |
| 6.5B (2024) | 2030 | ~24% | Smart plug category, broader end-user inclusion | A competing analysis |
| 217.8M (2021) | 2030 | 32.0% | Smart plugs only, narrower historical base | Another published benchmark |
Our analysis suggests the combined plug-and-switch definition at 482.4M in 2025 is the most defensible for buyers evaluating the connected switching category holistically. Plug-only figures in the multi-billion range reflect retail-value aggregation and broader device categories, making them non-comparable to manufacturer-level switch data.
Segmentation follows connectivity, application environment, end-use, form factor, and sales channel. The combination matters because Wi-Fi-led residential demand behaves very differently from Zigbee/Thread-led commercial retrofit demand.
| Parent Segment | Children |
|---|---|
| By Connection Type | Wi-Fi, Bluetooth, Zigbee/Thread, Z-Wave |
| By Application | Indoor, Outdoor |
| By End-Use | Residential, Commercial, Industrial |
| By Form Factor | Wall-Plug Adapter, In-Wall Outlet, Smart Power Strip, Modular Switch |
| By Sales Channel | Online, Offline |
Wi-Fi remains the volume anchor because of voice-assistant compatibility and router ubiquity. Zigbee/Thread is the fastest-growing connectivity segment at ~26% CAGR, driven by Matter adoption and local-control preferences in larger homes and commercial sites.
North America leads with roughly 32% of global value in 2025, supported by high smart-home penetration, mature retail channels, and utility-led energy-efficiency programs. Asia Pacific is the fastest-growing region, led by China, India, and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| South America | 0.07% |
| Middle East & Africa | 0.09% |
Our analysis suggests Asia Pacific's share will converge toward North America's by 2029, compressing the historical price premium that Western brands have enjoyed.
Growth is anchored by regulatory mandates, voice-assistant ecosystems, and falling Wi-Fi chipset costs that have pushed retail prices below USD 10 in several markets. Restraints are concentrated in cybersecurity trust and measurement accuracy.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Government energy-efficiency mandates | Driver | High | Plug-load control embedded in building codes (e.g., California Title 24) |
| Voice-assistant ecosystems | Driver | High | Alexa/Google/Apple expand addressable use cases (140k+ compatible devices) |
| Falling Wi-Fi chipset ASPs | Driver | High | Sub-USD 10 retail pricing unlocks emerging markets |
| Matter 1.3 interoperability | Driver | Medium-High | Reduces ecosystem lock-in and return rates |
| Cybersecurity breaches | Restraint | High | Smart-device attacks doubled in 2024; trust erosion |
| Inaccurate energy-metering claims | Restraint | Medium | Recall risk and regulatory scrutiny in NA/EU |
| Fragmented RF spectrum | Restraint | Medium | Limits reliability in emerging markets |
| EU WEEE recycling costs | Restraint | Medium | Margin pressure on EU-sold devices |
The balance favors growth: regulatory tailwinds are structural and multi-year, while cybersecurity risk is being addressed through certification schemes (e.g., the FCC Cyber Trust Mark). Vendors that invest early in certified security will convert a shared restraint into a differentiation moat.
The competitive field is fragmented but consolidating around ecosystem owners and networking incumbents. No single vendor holds a dominant global share, but TP-Link, Belkin, Xiaomi, Amazon, and Schneider Electric each lead distinct demand pools.
| Company | Primary Positioning | Notable Strength |
|---|---|---|
| TP-Link | Volume leader in smart plugs | Kasa/Tapo lines, Matter-ready, broad retail reach |
| Belkin (Wemo) | Premium iOS-integrated plugs | Apple HomeKit depth, design-led |
| Xiaomi | Price-led, Asia-focused | Bundled ecosystem, D2C distribution |
| Amazon (First-Party) | Alexa-native plugs | Frictionless setup within Echo ecosystem |
| D-Link | Security-adjacent networking plugs | Brand trust in networking |
| Legrand | Premium switches and sockets | Specification-led commercial channels |
| Schneider Electric | Modular switches + building controls | Code compliance, contractor relationships |
| Leviton | North American wiring-device incumbent | Installed-base leverage, voice-control integration |
| Lutron | Lighting-control specialty | Premium dimming ecosystems |
| Honeywell | Building and safety integration | Commercial and industrial footprint |
Differentiation is shifting from app quality toward interoperability, energy intelligence, and installer support. Ecosystem owners (Amazon, Xiaomi) monetize through attach rates, while networking and wiring-device incumbents defend through channel relationships and specification compliance.
Buyers should treat interoperability, security certification, and energy-metering accuracy as mission-critical, not premium extras. Matter compatibility is now the strongest predictor of long-term usability, while FCC Cyber Trust Mark or equivalent labeling reduces procurement risk in regulated channels.
Switching costs are rising for commercial and industrial buyers: once plug-level data feeds into demand-response or building-management systems, rip-and-replace becomes expensive. For residential buyers, switching costs remain low, which keeps price sensitivity high and favors bundled multipacks.
Regulatory compliance is the hidden differentiator. California Title 24, Energy Star SHEMS, and UK smart-appliance rules increasingly dictate which devices can be specified. Buyers in regulated channels should prioritize vendors with documented certification histories and published firmware-update commitments, not just feature lists.
The balance of evidence favors a “compliance-plus-interoperability” strategy over pure price competition. The market's 25.7% CAGR is real, but the incremental growth is concentrating where devices must pass certification, integrate with utility programs, or operate inside Matter ecosystems. Vendors that treat these as afterthoughts will win unit share in unregulated retail and lose value share in specification-led channels.
The strongest counter-argument is that price-led Asian brands (notably Xiaomi and second-tier ODMs) could commoditize the category faster than regulation can premiumize it, especially in emerging markets where certification enforcement is weak. This is plausible in residential retail, but our analysis suggests commercial and industrial demand will remain certification-gated, preserving margin pools for compliant vendors.
Actionable Strategy:
The evidence that would change our conclusion: if Matter adoption stalls below 40% of new device shipments by 2027, or if utility demand-response programs fail to scale beyond pilot stage, the premiumization thesis weakens materially and price-led competition becomes the dominant dynamic.
While this overview covers the strategic landscape, precise sub-segment forecasting — particularly for industrial plug-load controls and regional certification timelines — requires the full report's segment-level modeling and vendor benchmarking.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 25.7% from 2020-2034 |
| Segmentation |
|
The market is growing at approximately 25.7% CAGR from 2026 to 2031, driven by energy-efficiency mandates, voice-assistant ecosystems, and falling Wi-Fi chipset costs.
North America leads with roughly 32% of global value in 2025, while Asia Pacific is the fastest-growing region at a ~27.6% CAGR through 2031.
Smart plugs are plug-in adapters controlling appliances via an outlet, while smart switches replace wall switches to control lighting circuits directly. Both enable remote and automated control.
Matter certification ensures devices work across Apple, Amazon, Google, and Samsung ecosystems, reducing lock-in risk and improving long-term usability and resale value.
Cybersecurity breaches, inaccurate energy-metering claims, fragmented RF spectrum in emerging markets, and EU recycling costs are the primary restraints on adoption and margins.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement to validate category-level dynamics. In-depth interviews were conducted with stakeholders across the value chain, including Wi-Fi and Zigbee chipset suppliers, smart plug and switch ODMs, contract manufacturers, and global distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads across residential and commercial channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Product Development Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Chipset & Component Suppliers | 30% |
| Smart Plug & Switch Manufacturers | 40% |
| Global Distributors & Retailers | 20% |
| Certification & Standards Bodies | 10% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and recognized technical standards bodies. Regulatory frameworks referenced include the Connectivity Standards Alliance (Matter), IEC 60947 low-voltage switchgear standards, the U.S. FCC equipment rules, and California Title 24 building-code requirements. All secondary benchmarks are cross-referenced against primary interview findings before inclusion.
Market sizing triangulates top-down macroeconomic allocation (housing starts, smart-home penetration, energy-efficiency program spend) against bottom-up modeling (manufacturer capacity, product pricing, and end-use consumption by region). The reconciliation process isolates definitional differences — plug-only versus combined plug-and-switch scope, manufacturer versus retail value — to produce a single defensible base-year figure.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |