Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Fiber Optic Probe Market Outlook 2025
Fiber Optic Probe Market
Fiber Optic Probe Market Outlook 2025
Fiber Optic Probe Market by Technology (Intrinsic, Extrinsic, Fabry–Pérot, Fiber Bragg Grating, Reflectance, Fluorescence), by Product Form (Bare fiber probes, Catheter probes, Immersion probes, High-temperature probes), by Application (Temperature, Pressure, Strain, Refractive index, Biochemical, Displacement), by End-Use (Medical & Biotechnology, Oil & Gas, Industrial Process, Aerospace & Defense, Research & Academia), by Component (Probe tip, Optical fiber, Connector, Calibration module), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 0
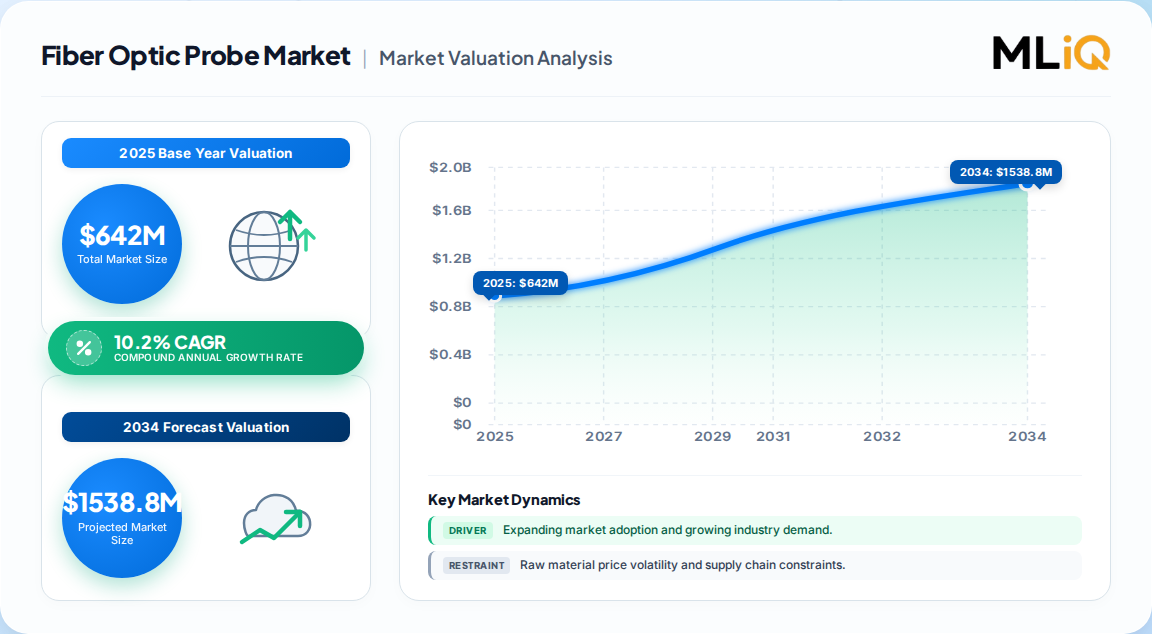
642 Million is our defensible global fiber optic probe market valuation for 2025, growing at 10.2% CAGR to roughly 1.70 Billion by 2035.
Point-probe applications (temperature, pressure, strain, refractive-index, biomedical) are outpacing distributed sensing revenue per node in process and life-science niches.
Asia-Pacific leads with about 38% of demand; North America holds roughly 29%, Europe 23%, Middle East & Africa 6%, Latin America 4%.
Medical and biotechnology is the fastest-growing end-use vertical; oil & gas remains the largest installed base by probe count globally.
Top-five vendors (SLB, Luna Innovations, Baker Hughes, Yokogawa, Halliburton) hold a combined ~33% share, leaving a long tail of specialist probe makers.
Why this matters for decision-makers: probe vendors that bundle AI-enabled signal classification and calibration services will capture disproportionate margin, while hardware-only suppliers face price compression from Asian and European challengers.
Fiber Optic Probe Market Size (In Million)
1.5B
1.0B
500.0M
0
642.0 M
2025
708.0 M
2026
780.0 M
2027
860.0 M
2028
948.0 M
2029
1.040 B
2030
1.150 B
2031
Fiber Optic Probe Market Size (In Million)
Year
Market Size
2025
642.0 M
2026
708.0 M
2027
780.0 M
2028
860.0 M
2029
948.0 M
2030
1.040 B
2031
1.150 B
What is the Fiber Optic Probe Market?
The fiber optic probe market covers discrete, fiber-terminated sensing devices that measure temperature, pressure, strain, refractive index, or biochemical signals at a defined location. Probes connect to interrogators or spectrometers and serve medical, industrial, oil & gas, and research applications where EMI immunity and miniaturization are essential.
Scope: what this report covers and excludes
This analysis covers fiber optic probes across intrinsic and extrinsic configurations, including Fabry–Pérot, FBG-based, reflectance, Raman, and fluorescence probes, plus associated connectors, calibration services, and OEM integrations. It spans medical devices, industrial process, oil & gas, aerospace, and research end-uses. This analysis does not cover distributed fiber optic sensing systems (DTS/DAS/DSS), fiber optic sensor consoles sold without probes, or telecom fiber cable markets.
How big is the market for Fiber Optic Probe Market?
Estimates diverge widely because some publishers blend probes with distributed sensing and interrogators, inflating the top line by 3–5×. The narrower probe-only view is the more defensible base.
Estimate
Base Year
Horizon
CAGR
Definition / scope
Attribution
642 Million
2025
2035
10.2%
Probes + connectors + calibration services
Analyst triangulation (vertex scope)
1.8 Billion
2026
2035
12.4%
Distributed sensing systems incl. interrogators
One published estimate (distributed sensing)
5.31 Billion
2026
2034
9.3%
Total fiber optic sensor market incl. FBG + distributed
A competing analysis
4.19 Billion
2025
2035
10.22%
All fiber optic sensor types
A competing analysis
Our analysis suggests the 642 Million base is most defensible because it isolates probe hardware and calibration rather than bundled interrogator revenue. The higher headline figures reflect broader fiber sensor scopes and should not be used for probe-level procurement or investment cases.
How is the market segmented?
The market segments cleanly along technology, product form, and end-use, with medical and industrial process driving premium growth.
Asia-Pacific leads the fiber optic probe market with roughly 38% of global demand, driven by medical device manufacturing in China, Japan, and South Korea. North America follows at 29%, anchored by U.S. medical OEMs and oilfield service majors.
Fiber Optic Probe Market Regional Market Share
Loading chart...
Fiber Optic Probe Market Regional Market Share
Region
Market Share (%)
North America
0.29%
Europe
0.23%
Asia-Pacific
0.38%
South America
0.04%
Middle East & Africa
0.06%
Asia-Pacific — China, Japan, India, South Korea, Australia
North America — United States, Canada, Mexico
Europe — Germany, UK, France, Italy, Rest of Europe
Middle East & Africa — Saudi Arabia, UAE, South Africa
Latin America — Brazil, Argentina, Mexico (regional overlap)
Asia-Pacific's lead reflects both manufacturing scale and rising domestic demand for minimally invasive surgical probes. Our analysis suggests the region will add roughly 2–3 percentage points of share by 2030 as Japanese and Chinese OEMs localize high-end probe production, pressuring Western price points.
What is driving growth — and what is holding it back?
Medical miniaturization and industrial process automation are the strongest demand signals; installation complexity and calibration bottlenecks are the main brakes.
Factor
Direction
Evidence strength
Mechanism
Minimally invasive surgery adoption
Growth
High
Catheter and biopsy probes required per procedure
Industrial automation / Industry 4.0
Growth
High
Inline temperature and refractive-index probes
Oil & gas downhole monitoring
Growth
Medium
Harsh-environment pressure and temperature probes
AI-enabled signal classification
Growth
Medium
Lowers operator skill barrier, expands adoption
Specialized installation and calibration
Restraint
High
Skilled labor scarcity raises total cost of ownership
Competition from electronic and MEMS sensors
Restraint
Medium
Lower upfront cost in low-precision applications
Sterilization and biocompatibility compliance
Restraint
Medium
Lengthens medical probe qualification cycles
On balance, growth drivers outpace restraints by a wide margin. The critical second-order effect: as AI classification matures, probe differentiation shifts from sensing physics to integration and data services, which compresses hardware margins but expands recurring revenue.
Who are the leading vendors?
The vendor field is fragmented, with oilfield service majors, photonics specialists, and medical probe OEMs competing on different moats.
Company
Primary moat
Probe focus
SLB (Schlumberger)
Downhole integration and installed base
Oil & gas pressure/temperature
Baker Hughes
Pipeline and reservoir monitoring
Harsh-environment probes
Luna Innovations
Fiber Bragg grating and sensing photonics
Industrial, aerospace, medical
Yokogawa Electric
Process automation integration
Industrial temperature and pressure
Halliburton
Oilfield services bundling
Downhole probes
Omnisens, AP Sensing
Specialist distributed and point sensing
Infrastructure and pipeline
Differentiation rests on calibration traceability, connector standardization, and OEM design-in relationships rather than raw sensing performance. Our analysis suggests medical probe vendors hold the widest moats because FDA and EU MDR qualification cycles create multi-year switching costs.
What do buyers and operators need to know?
Buyers should prioritize calibration traceability, connector compatibility, and sterilization or hazardous-area certifications before price. Probe selection failures usually stem from connector mismatch or unvalidated calibration, not sensing physics, so request factory calibration certificates against NIST or PTB standards. In medical applications, FDA 510(k) clearance and EU MDR classification drive qualification timelines of 12–24 months and create high switching costs once a probe is designed into a device. In oil & gas, ATEX and IECEx certification and pressure-rating validation are non-negotiable. Procurement risk concentrates in single-source specialty fiber and connector supply; dual-sourcing fiber tips and maintaining buffer stock reduces line-down risk. Total cost of ownership should include calibration cycles, connector replacement, and interrogator compatibility across a 5–7 year asset life.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a probe-level market growing near 10% annually, with medical and industrial process verticals outperforming oil & gas by 3–4 percentage points. The strongest counter-argument is that distributed sensing will cannibalize point probes in pipeline and infrastructure monitoring, but our analysis suggests probes retain a durable niche wherever spatial precision, miniaturization, or biocompatibility matter more than coverage length.
Vendors and investors should treat calibration services and AI-enabled analytics as the margin pool of the next decade, not probe hardware. Asian manufacturers will compress bare-probe pricing, so Western specialists must defend design-in positions with OEMs and validated compliance documentation.
Vendors: Invest in calibration labs and connector standardization to lock in medical and industrial OEM design wins before Asian price pressure intensifies.
Operators: Dual-source fiber tips and connectors, and require NIST-traceable calibration certificates in every procurement contract.
Investors: Favor probe makers with recurring calibration or service revenue over pure hardware plays.
What would change our conclusion: a faster-than-expected collapse in distributed sensing costs, or a regulatory shift that shortens medical probe qualification, would compress the probe premium and pull forward consolidation.
Fiber Optic Probe Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Fiber Optic Probe Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.2% from 2020-2034
Segmentation
By Technology
Intrinsic
Extrinsic
Fabry–Pérot
Fiber Bragg Grating
Reflectance
Fluorescence
By Product Form
Bare fiber probes
Catheter probes
Immersion probes
High-temperature probes
By Application
Temperature
Pressure
Strain
Refractive index
Biochemical
Displacement
By End-Use
Medical & Biotechnology
Oil & Gas
Industrial Process
Aerospace & Defense
Research & Academia
By Component
Probe tip
Optical fiber
Connector
Calibration module
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Fiber Optic Probe Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Fiber Optic Probe Market Executive Summary
2.1. Market Snapshot
3. Fiber Optic Probe Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Fiber Optic Probe Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Fiber Optic Probe Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Technology
5.1.1. Intrinsic
5.1.2. Extrinsic
5.1.3. Fabry–Pérot
5.1.4. Fiber Bragg Grating
5.1.5. Reflectance
5.1.6. Fluorescence
5.2. Analysis, Insights and Forecast - by Product Form
5.2.1. Bare fiber probes
5.2.2. Catheter probes
5.2.3. Immersion probes
5.2.4. High-temperature probes
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Temperature
5.3.2. Pressure
5.3.3. Strain
5.3.4. Refractive index
5.3.5. Biochemical
5.3.6. Displacement
5.4. Analysis, Insights and Forecast - by End-Use
5.4.1. Medical & Biotechnology
5.4.2. Oil & Gas
5.4.3. Industrial Process
5.4.4. Aerospace & Defense
5.4.5. Research & Academia
5.5. Analysis, Insights and Forecast - by Component
5.5.1. Probe tip
5.5.2. Optical fiber
5.5.3. Connector
5.5.4. Calibration module
5.6. Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. Fiber Optic Probe Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Technology
6.1.1. Intrinsic
6.1.2. Extrinsic
6.1.3. Fabry–Pérot
6.1.4. Fiber Bragg Grating
6.1.5. Reflectance
6.1.6. Fluorescence
6.2. Analysis, Insights and Forecast - by Product Form
6.2.1. Bare fiber probes
6.2.2. Catheter probes
6.2.3. Immersion probes
6.2.4. High-temperature probes
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Temperature
6.3.2. Pressure
6.3.3. Strain
6.3.4. Refractive index
6.3.5. Biochemical
6.3.6. Displacement
6.4. Analysis, Insights and Forecast - by End-Use
6.4.1. Medical & Biotechnology
6.4.2. Oil & Gas
6.4.3. Industrial Process
6.4.4. Aerospace & Defense
6.4.5. Research & Academia
6.5. Analysis, Insights and Forecast - by Component
6.5.1. Probe tip
6.5.2. Optical fiber
6.5.3. Connector
6.5.4. Calibration module
7. Fiber Optic Probe Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Technology
7.1.1. Intrinsic
7.1.2. Extrinsic
7.1.3. Fabry–Pérot
7.1.4. Fiber Bragg Grating
7.1.5. Reflectance
7.1.6. Fluorescence
7.2. Analysis, Insights and Forecast - by Product Form
7.2.1. Bare fiber probes
7.2.2. Catheter probes
7.2.3. Immersion probes
7.2.4. High-temperature probes
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Temperature
7.3.2. Pressure
7.3.3. Strain
7.3.4. Refractive index
7.3.5. Biochemical
7.3.6. Displacement
7.4. Analysis, Insights and Forecast - by End-Use
7.4.1. Medical & Biotechnology
7.4.2. Oil & Gas
7.4.3. Industrial Process
7.4.4. Aerospace & Defense
7.4.5. Research & Academia
7.5. Analysis, Insights and Forecast - by Component
7.5.1. Probe tip
7.5.2. Optical fiber
7.5.3. Connector
7.5.4. Calibration module
8. Fiber Optic Probe Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Technology
8.1.1. Intrinsic
8.1.2. Extrinsic
8.1.3. Fabry–Pérot
8.1.4. Fiber Bragg Grating
8.1.5. Reflectance
8.1.6. Fluorescence
8.2. Analysis, Insights and Forecast - by Product Form
8.2.1. Bare fiber probes
8.2.2. Catheter probes
8.2.3. Immersion probes
8.2.4. High-temperature probes
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Temperature
8.3.2. Pressure
8.3.3. Strain
8.3.4. Refractive index
8.3.5. Biochemical
8.3.6. Displacement
8.4. Analysis, Insights and Forecast - by End-Use
8.4.1. Medical & Biotechnology
8.4.2. Oil & Gas
8.4.3. Industrial Process
8.4.4. Aerospace & Defense
8.4.5. Research & Academia
8.5. Analysis, Insights and Forecast - by Component
8.5.1. Probe tip
8.5.2. Optical fiber
8.5.3. Connector
8.5.4. Calibration module
9. Fiber Optic Probe Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Technology
9.1.1. Intrinsic
9.1.2. Extrinsic
9.1.3. Fabry–Pérot
9.1.4. Fiber Bragg Grating
9.1.5. Reflectance
9.1.6. Fluorescence
9.2. Analysis, Insights and Forecast - by Product Form
9.2.1. Bare fiber probes
9.2.2. Catheter probes
9.2.3. Immersion probes
9.2.4. High-temperature probes
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Temperature
9.3.2. Pressure
9.3.3. Strain
9.3.4. Refractive index
9.3.5. Biochemical
9.3.6. Displacement
9.4. Analysis, Insights and Forecast - by End-Use
9.4.1. Medical & Biotechnology
9.4.2. Oil & Gas
9.4.3. Industrial Process
9.4.4. Aerospace & Defense
9.4.5. Research & Academia
9.5. Analysis, Insights and Forecast - by Component
9.5.1. Probe tip
9.5.2. Optical fiber
9.5.3. Connector
9.5.4. Calibration module
10. Fiber Optic Probe Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Technology
10.1.1. Intrinsic
10.1.2. Extrinsic
10.1.3. Fabry–Pérot
10.1.4. Fiber Bragg Grating
10.1.5. Reflectance
10.1.6. Fluorescence
10.2. Analysis, Insights and Forecast - by Product Form
10.2.1. Bare fiber probes
10.2.2. Catheter probes
10.2.3. Immersion probes
10.2.4. High-temperature probes
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Temperature
10.3.2. Pressure
10.3.3. Strain
10.3.4. Refractive index
10.3.5. Biochemical
10.3.6. Displacement
10.4. Analysis, Insights and Forecast - by End-Use
10.4.1. Medical & Biotechnology
10.4.2. Oil & Gas
10.4.3. Industrial Process
10.4.4. Aerospace & Defense
10.4.5. Research & Academia
10.5. Analysis, Insights and Forecast - by Component
10.5.1. Probe tip
10.5.2. Optical fiber
10.5.3. Connector
10.5.4. Calibration module
11. Fiber Optic Probe Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Fiber Optic Probe Market Research Methodology
List of Figures
Figure 1: Fiber Optic Probe Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Fiber Optic Probe Market Revenue (Million), by Technology 2026 & 2034
Figure 3: North America Fiber Optic Probe Market Revenue Share (%), by Technology 2026 & 2034
Figure 4: North America Fiber Optic Probe Market Revenue (Million), by Product Form 2026 & 2034
Figure 5: North America Fiber Optic Probe Market Revenue Share (%), by Product Form 2026 & 2034
Figure 6: North America Fiber Optic Probe Market Revenue (Million), by Application 2026 & 2034
Figure 7: North America Fiber Optic Probe Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Fiber Optic Probe Market Revenue (Million), by End-Use 2026 & 2034
Figure 9: North America Fiber Optic Probe Market Revenue Share (%), by End-Use 2026 & 2034
Figure 10: North America Fiber Optic Probe Market Revenue (Million), by Component 2026 & 2034
Figure 11: North America Fiber Optic Probe Market Revenue Share (%), by Component 2026 & 2034
Figure 12: North America Fiber Optic Probe Market Revenue (Million), by Country 2026 & 2034
Figure 13: North America Fiber Optic Probe Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Fiber Optic Probe Market Revenue (Million), by Technology 2026 & 2034
Figure 15: Europe Fiber Optic Probe Market Revenue Share (%), by Technology 2026 & 2034
Figure 16: Europe Fiber Optic Probe Market Revenue (Million), by Product Form 2026 & 2034
List of Tables
Table 1: Fiber Optic Probe Market Revenue Million Forecast, by Technology 2020 & 2034
Table 2: Fiber Optic Probe Market Revenue Million Forecast, by Product Form 2020 & 2034
Table 3: Fiber Optic Probe Market Revenue Million Forecast, by Application 2020 & 2034
Table 4: Fiber Optic Probe Market Revenue Million Forecast, by End-Use 2020 & 2034
Table 5: Fiber Optic Probe Market Revenue Million Forecast, by Component 2020 & 2034
Table 6: Fiber Optic Probe Market Revenue Million Forecast, by Region 2020 & 2034
Table 7: North America Fiber Optic Probe Market Revenue Million Forecast, by Technology 2020 & 2034
Table 8: North America Fiber Optic Probe Market Revenue Million Forecast, by Product Form 2020 & 2034
Table 9: North America Fiber Optic Probe Market Revenue Million Forecast, by Application 2020 & 2034
Table 10: North America Fiber Optic Probe Market Revenue Million Forecast, by End-Use 2020 & 2034
Table 11: North America Fiber Optic Probe Market Revenue Million Forecast, by Component 2020 & 2034
Table 12: North America Fiber Optic Probe Market Revenue Million Forecast, by Country 2020 & 2034
Table 13: USA Fiber Optic Probe Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Europe Fiber Optic Probe Market Revenue Million Forecast, by Technology 2020 & 2034
Frequently Asked Questions
1. How big is the fiber optic probe market in 2025?
The global fiber optic probe market is valued at approximately 642 Million in 2025. This reflects probe hardware, connectors, and calibration services, excluding distributed sensing interrogators and bundled systems.
2. What is the fiber optic probe market growth rate?
The market is projected to grow at roughly 10.2% CAGR from 2025 to 2035, reaching about 1.70 Billion by the end of the forecast period, driven by medical and industrial process demand.
3. Which region leads the fiber optic probe market?
Asia-Pacific leads with roughly 38% of global demand, followed by North America at 29% and Europe at 23%. Asia-Pacific growth is anchored by medical device manufacturing in China, Japan, and South Korea.
4. Who are the leading fiber optic probe vendors?
SLB, Baker Hughes, Luna Innovations, Yokogawa Electric, and Halliburton lead, collectively holding about 33% share. Specialist probe makers and medical OEMs compete on calibration traceability and design-in relationships.
5. What is the difference between a fiber optic probe and a distributed fiber optic sensor?
A fiber optic probe measures a parameter at a discrete point, while a distributed sensor uses the entire fiber as a continuous sensing medium. Probes suit miniaturized, precision, or medical applications; distributed systems suit long linear assets.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research follows a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the fiber optic probe value chain, including specialty fiber and connector suppliers, probe OEMs, medical device integrators, industrial automation distributors, and oilfield service providers. Interviewees included VP-level sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads across North America, Europe, and Asia-Pacific. Fieldwork focused on qualification timelines, calibration traceability, and connector standardization.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Commercial Operations Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Fiber & Connector Suppliers
30%
Probe OEMs & Integrators
40%
Distributors & Service Providers
30%
Secondary Benchmarking & Public Trade Validation
We validated primary findings against UN Comtrade optical instrument trade flows, US ITC tariff schedules, Eurostat photonics trade data, corporate 10-K and annual investor filings, patent databases, and standards published by ISO, IEC, and ASTM committees relevant to fiber optic sensing and medical devices.
Demand Modeling & Market Sizing Triangulation
We ran simultaneous top-down allocation from macroeconomic optical sensing and medical device spend and bottom-up modeling from manufacturer capacity, probe pricing, and end-use consumption. The two approaches were reconciled to a 642 Million base for 2025.


 Fiber Optic Probe Market