Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Rheology Modification Coating Additives Market by Application (Architectural Coatings, Wood Coatings, Protective & Marine Coatings, Automotive Coatings, Industrial Coatings), by Type (Polymeric Thickeners, Natural & Bio-based Thickeners, Inorganic Thickeners, Synthetic Associative Thickeners), by End-Use Industry (Construction, Furniture & Woodcare, Automotive, Packaging, Industrial), by Formulation Type (Water-borne, Solvent-borne, UV-curable, High-solids, Powder), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Australia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Rest of Europe), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 0
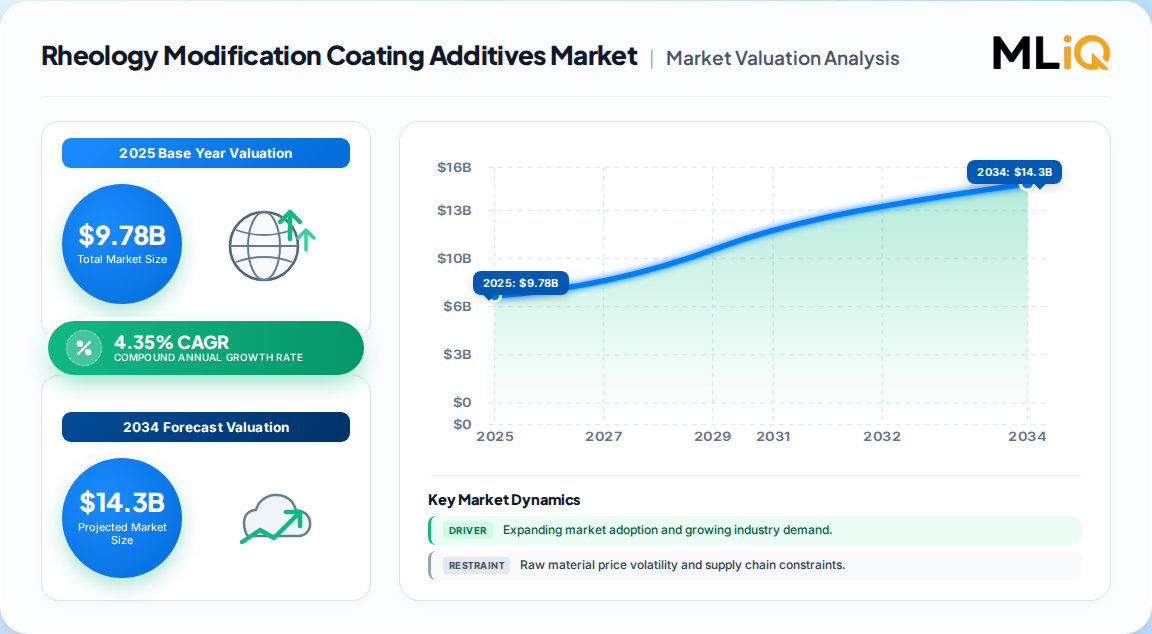
USD 9.78 billion in 2025 is the most defensible global base-year value for the Rheology Modification Coating Additives Market, with a 4.35% CAGR through 2030.
Forecast size reaches USD 12.10 billion by 2030, implying roughly USD 2.32 billion of absolute incremental demand across five years.
Architectural coatings held 38.45% revenue share in 2024 and remain the largest application, though protective and marine coatings grow fastest at 5.45%.
Asia-Pacific accounted for 35.77% of global revenue in 2024 and is also the fastest-growing region at a 5.35% CAGR.
Polymeric thickeners dominate at 42.66% share, while natural and bio-based thickeners post the highest type-level CAGR at 5.35%.
BASF, Dow, Arkema, ALTANA, Ashland, Evonik, Clariant, Lubrizol and Elementis anchor a medium-concentration competitive field.
Why this matters for decision-makers: Vendors that cannot pair low-shear storage stability with high-shear application performance will lose specification wins as low-VOC and high-solids reformulation accelerates.
Rheology Modification Coating Additives Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.780 B
2025
10.21 B
2026
10.65 B
2027
11.11 B
2028
11.60 B
2029
12.10 B
2030
Rheology Modification Coating Additives Market Size (In Billion)
Year
Market Size
2025
9.780 B
2026
10.21 B
2027
10.65 B
2028
11.11 B
2029
11.60 B
2030
12.10 B
What is the Rheology Modification Coating Additives Market?
Rheology modification coating additives are specialty chemicals dosed at low levels into paints and coatings to control viscosity, flow, leveling, sag resistance and pigment suspension across storage, application and cure stages. Core chemistries include HEUR, HASE, cellulosic and inorganic thickeners used across water-borne, solvent-borne and UV-curable systems.
Scope: what this report covers and excludes
This report covers global demand for rheology modification coating additives by application, type, end-use industry and formulation type, with a base year of 2025 and forecast horizon to 2030. Value is stated in USD at manufacturer-level revenue. This analysis does not cover resin, pigment, filler or solvent raw materials, nor finished paints, powder coatings or adjacent additive families such as defoamers, wetting agents and dispersants except where referenced for context.
How big is the market for Rheology Modification Coating Additives Market?
Estimates diverge materially because each publisher draws a different boundary around thickeners versus broader coating additives. The table below compares the leading published figures against their underlying definitions.
Entire coating additives category, not rheology-only
One published estimate
Our analysis suggests the USD 9.78 billion figure is the most defensible because it isolates rheology modifiers while preserving full value-chain pricing. The USD 14.11 billion estimate appears to absorb adjacent surface and dispersion additives, inflating the base by roughly 40%. The USD 4.40 billion figure likely excludes associative thickeners sold as part of bundled additive packages.
Callout — What this implies: Buyers benchmarking supplier quotes against the low-end figure risk under-budgeting by a factor of two. Price negotiations should reference the mid-range definition.
How is the market segmented?
The market segments along four non-geographic axes — application, chemistry type, end-use industry and formulation — each with distinct growth velocities that matter for portfolio allocation.
Solvent-borne largest (51.34%); UV-curable fastest (5.34% CAGR)
The segmentation reveals a structural tension: the largest pool of revenue today sits in solvent-borne, construction-led demand, yet every fastest-growing cell — bio-based thickeners, UV-curable systems, protective coatings — points toward low-VOC, high-performance formats. Suppliers weighted to legacy solvent-borne portfolios face a slow-growth trajectory relative to peers invested in associative and bio-based chemistries.
Which region leads in Rheology Modification Coating Additives Market?
Asia-Pacific leads with 35.77% of 2024 revenue and the fastest growth at 5.35% CAGR, driven by construction volume and local paint manufacturing capacity.
China, India, Japan, South Korea, ASEAN, Australia
North America
USA, Canada, Mexico
Europe
Germany, UK, France, Italy, Rest of Europe
South America
Brazil, Argentina, Rest of South America
Middle East & Africa
Saudi Arabia, UAE, South Africa, Rest of MEA
Region
2024 revenue share
Asia-Pacific
35.77%
North America
23.12%
Europe
22.65%
Middle East & Africa
9.53%
South America
8.93%
Our analysis suggests the APAC concentration is understated in value terms because much of the region's additive volume moves through local formulators at lower unit prices. In volume terms, APAC's share likely exceeds 40%. This divergence implies that global suppliers must localize production in China and India to defend margin, since import-dependent pricing caps realizable revenue per kilogram.
What is driving growth — and what is holding it back?
Regulatory VOC ceilings and APAC infrastructure spending are the dominant growth engines, while feedstock volatility and microplastics scrutiny are the principal drags.
Factor
Direction
Evidence strength
Mechanism
Low-VOC water-borne shift
Driver (+1.2%)
Strong
Forces associative thickener adoption for film build parity
APAC urbanization & infrastructure
Driver (+0.8%)
Strong
Multi-year architectural coating volume growth
High-solids emission norms
Driver (+0.6%)
Moderate
Reduced flow distance demands novel rheology control
Automotive finish tolerances
Driver (+0.5%)
Moderate
EV geometries raise edge-cover and orange-peel standards
AI formulation platforms
Driver (+0.4%)
Emerging
Enables hyper-custom rheology packages
Feedstock price volatility
Restraint (−0.7%)
Strong
TiO2 and specialty monomer swings compress margins
Microplastics regulation
Restraint (−0.5%)
Moderate
Targets synthetic associative thickeners in EU, North America
Nano-additive substitution
Restraint (−0.3%)
Weak
Multifunctional additives reduce separate modifier need
The balance favors growth: net driver impact of roughly +3.5 percentage points against −1.5 points of restraint yields a sustainable mid-single-digit trajectory. The critical second-order effect is that restraints are concentrated in mature Western markets, while drivers are concentrated in APAC — meaning regional mix, not global average, will determine individual supplier outcomes.
Who are the leading vendors?
BASF, Dow, Arkema, ALTANA, Ashland, Evonik, Clariant, Lubrizol and Elementis lead a medium-concentration field differentiated by chemistry breadth and application expertise.
Company
Primary strengths
Notable positioning
BASF SE
Bio-based ethyl acrylate, HEUR/HASE breadth
Multifunctional portfolio, low-VOC leadership
Dow Inc.
Associative thickeners, cellulosics
Broad resin-system compatibility
Arkema
Specialty rheology modifiers
High-performance industrial niches
ALTANA (BYK)
Additive packages
Strong technical service embedment
Ashland
Cellulosic and synthetic thickeners
Architectural and industrial coatings
Evonik
Mass-balanced additive lines
Sustainability-claim differentiation
Clariant
High-margin sustainable chemistries
Margin resilience under feedstock swings
Lubrizol
Performance dispersants and modifiers
Automotive and industrial specification wins
Competitive moats rest less on molecule patents than on application testing depth and specification embedding. Once a thickener package is validated inside a tier-one paint formulation, switching costs run high because reformulation requires re-qualification of flow, leveling and sag performance. Suppliers with co-located technical service near major paint plants convert this into multi-year contracts.
What do buyers and operators need to know?
Mission-critical selection criteria center on the ability to hold low-shear viscosity for storage stability while delivering correct high-shear profile for spray application. Buyers should demand application-specific rheology curves rather than generic datasheet viscosity figures.
Procurement risk is concentrated in feedstock pass-through clauses. Specialty monomer and TiO2 volatility has historically forced suppliers to absorb margin, and buyers on fixed-price agreements should expect quality or lead-time trade-offs during spike periods.
Switching costs are material. Reformulating a validated coating to substitute a thickener typically requires full application re-testing across temperature and humidity cycles, often a 3–6 month exercise. Regulatory compliance adds a second layer: REACH and TSCA documentation, plus emerging microplastic restrictions on synthetic associative chemistries, must be verified at supplier level before qualification.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a mid-single-digit growth trajectory anchored on APAC construction and low-VOC reformulation, with the USD 9.78 billion base and 4.35% CAGR the most internally consistent reading of available data. The strongest counter-argument is that microplastics regulation could accelerate substitution of synthetic associative thickeners faster than bio-based alternatives can scale, compressing the forecast in EU and North American markets by 2030.
Our analysis suggests the real competitive battle is not molecule innovation but application integration. Suppliers who embed technical service inside customer formulation labs capture specification wins that survive feedstock cycles. The bio-based thickener segment's 5.35% CAGR signals where premium pricing will migrate, but volume scale remains constrained by performance parity gaps in high-shear applications.
Prioritize APAC localization: Suppliers should establish or expand local production in China and India to defend margin against import-dependent pricing.
Invest in application testing depth: Co-located technical service converts commoditized thickener sales into specification-locked contracts with high switching costs.
Pre-qualify bio-based portfolios: Vendors should validate bio-based thickener performance in high-shear systems now, ahead of expected microplastics restrictions.
Evidence that would change this conclusion: a binding EU restriction on synthetic associative thickeners earlier than 2028, or an APAC construction slowdown exceeding two consecutive quarters, would justify revising the CAGR downward toward 3%.
Research Methodology
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including raw material and specialty monomer suppliers, dedicated rheology modifier producers, contract formulators and blenders, and global industrial distributors. Decision-maker designations interviewed included VP-level sourcing executives, heads of coatings R&D, technical directors and commercial operations leads. Interview programs targeted formulation-level validation of viscosity performance claims rather than headline revenue confirmation.
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on UN Comtrade bilateral trade flows for HS-coded chemical intermediates, WTO tariff schedules, US ITC and Eurostat industrial chemical datasets, corporate 10-K and annual investor filings, patent databases, and recognized technical standards bodies operating in coatings and chemical classification.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up triangulation. Top-down allocation maps macroeconomic construction and automotive indicators onto coating volume, then applies additive dosage rates. Bottom-up modeling aggregates manufacturer capacity, product pricing and end-use consumption by region. Divergence between the two is reconciled at segment level.
1. How big is the Rheology Modification Coating Additives Market in 2025?
The market is estimated at USD 9.78 billion in 2025, based on the most defensible rheology-only definition. Broader additive-inclusive estimates reach USD 14.11 billion, but these absorb adjacent surface and dispersion chemistries rather than pure rheology modifiers.
2. What is the growth rate for Rheology Modification Coating Additives?
The market grows at a 4.35% CAGR from 2025 to 2030, reaching USD 12.10 billion. Growth is anchored by low-VOC water-borne reformulation in North America and Europe and infrastructure-driven architectural coating volume across Asia-Pacific.
3. Which region leads the Rheology Modification Coating Additives Market?
Asia-Pacific leads with 35.77% of 2024 revenue and the fastest 5.35% CAGR. China, India and ASEAN drive demand through construction and expanding local paint manufacturing capacity, though value realization per kilogram remains below Western benchmarks.
4. What are the main types of rheology modification coating additives?
Polymeric thickeners lead at 42.66% share, followed by inorganic and synthetic associative chemistries. Natural and bio-based thickeners are the fastest-growing segment at a 5.35% CAGR, driven by sustainability requirements and anticipated microplastics regulation.
5. Who are the leading companies in this market?
BASF, Dow, Arkema, ALTANA, Ashland, Evonik, Clariant, Lubrizol and Elementis lead a medium-concentration field. Differentiation rests on application testing depth and specification embedding rather than molecule patents alone.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including raw material and specialty monomer suppliers, dedicated rheology modifier producers, contract formulators and blenders, and global industrial distributors. Decision-maker designations interviewed included VP-level sourcing executives, heads of coatings R&D, technical directors and commercial operations leads. Interview programs targeted formulation-level validation of viscosity performance claims rather than headline revenue confirmation.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement Directors
35%
Quality & Regulatory Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Chemical Producers
45%
Formulators & Blenders
35%
Distributors & Traders
20%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on UN Comtrade bilateral trade flows for HS-coded chemical intermediates, WTO tariff schedules, US ITC and Eurostat industrial chemical datasets, corporate 10-K and annual investor filings, patent databases, and recognized technical standards bodies operating in coatings and chemical classification.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down and bottom-up triangulation. Top-down allocation maps macroeconomic construction and automotive indicators onto coating volume, then applies additive dosage rates. Bottom-up modeling aggregates manufacturer capacity, product pricing and end-use consumption by region. Divergence between the two is reconciled at segment level.


 Rheology Modification Coating Additives Market